
What should be done if a natural person is found to have enterprise position information before reverse invoicing? Kailing Technology's natural person director/supervisor/senior manager verification platform distinguishes "matched, pending verification, none" and generates a review checklist
What should be done if a natural person is found to have enterprise position information before reverse invoicing? Kailing Technology's natural person director/supervisor/senior manager verification platform distinguishes "matched, pending verification, none" and generates a review checklist
When a natural person is found to serve as legal representative, director, supervisor, or senior manager before reverse invoicing, what finance most needs to know is what to verify next. A position record itself does not mean every acquisition is ineligible, but it should not be ignored outright either. Kailing Technology's natural person director/supervisor/senior manager verification platform presents "matched, pending verification, none" separately and generates a review checklist requiring manual judgment.
▍First distinguish the meaning of verification results
"Hit" means that verifiable enterprise employment information was retrieved, and it is necessary to further confirm whether the record belongs to the seller in this transaction and its relationship to the transaction. "Pending verification" may be due to incomplete identity elements, a same-name match, or results that still require supplementary verification, and cannot be interpreted as "no employment." "None" means no matching record was found under the conditions of this query, and is also not a permanent guarantee covering all business activities.
The platform should retain query time, identity elements used, query batch, and result classification. When a natural person's information later changes, re-verification can be performed for new transactions. If the system only gives a static pass flag at initial filing, finance will find it difficult to judge whether the current invoicing basis is still valid.
▍After a hit, verify who is selling the goods
Business personnel need to clarify whether the natural person is selling scrapped products they collected personally, or operating in the name of an enterprise, delivering goods on behalf of an enterprise, or trading on behalf of other entities. The business scope of the employing enterprise, goods delivery materials, settlement arrangements, and receiving account can serve as review clues. The transaction subject cannot be automatically replaced based on a job title alone, nor can it be concluded that the goods definitely belong to the individual just because the person is present.
If a natural person holds positions in multiple enterprises at the same time, the review checklist should list the specific records and statuses that need confirmation. Matters such as an unclear actual seller, commingling of enterprise and personal funds, and missing cargo ownership materials should enter manual handling. Business and finance draw conclusions based on receipt facts and policy qualifications, and the platform is responsible for leaving traces of suspicious points and handling processes.
▍Pending verification should become an executable task
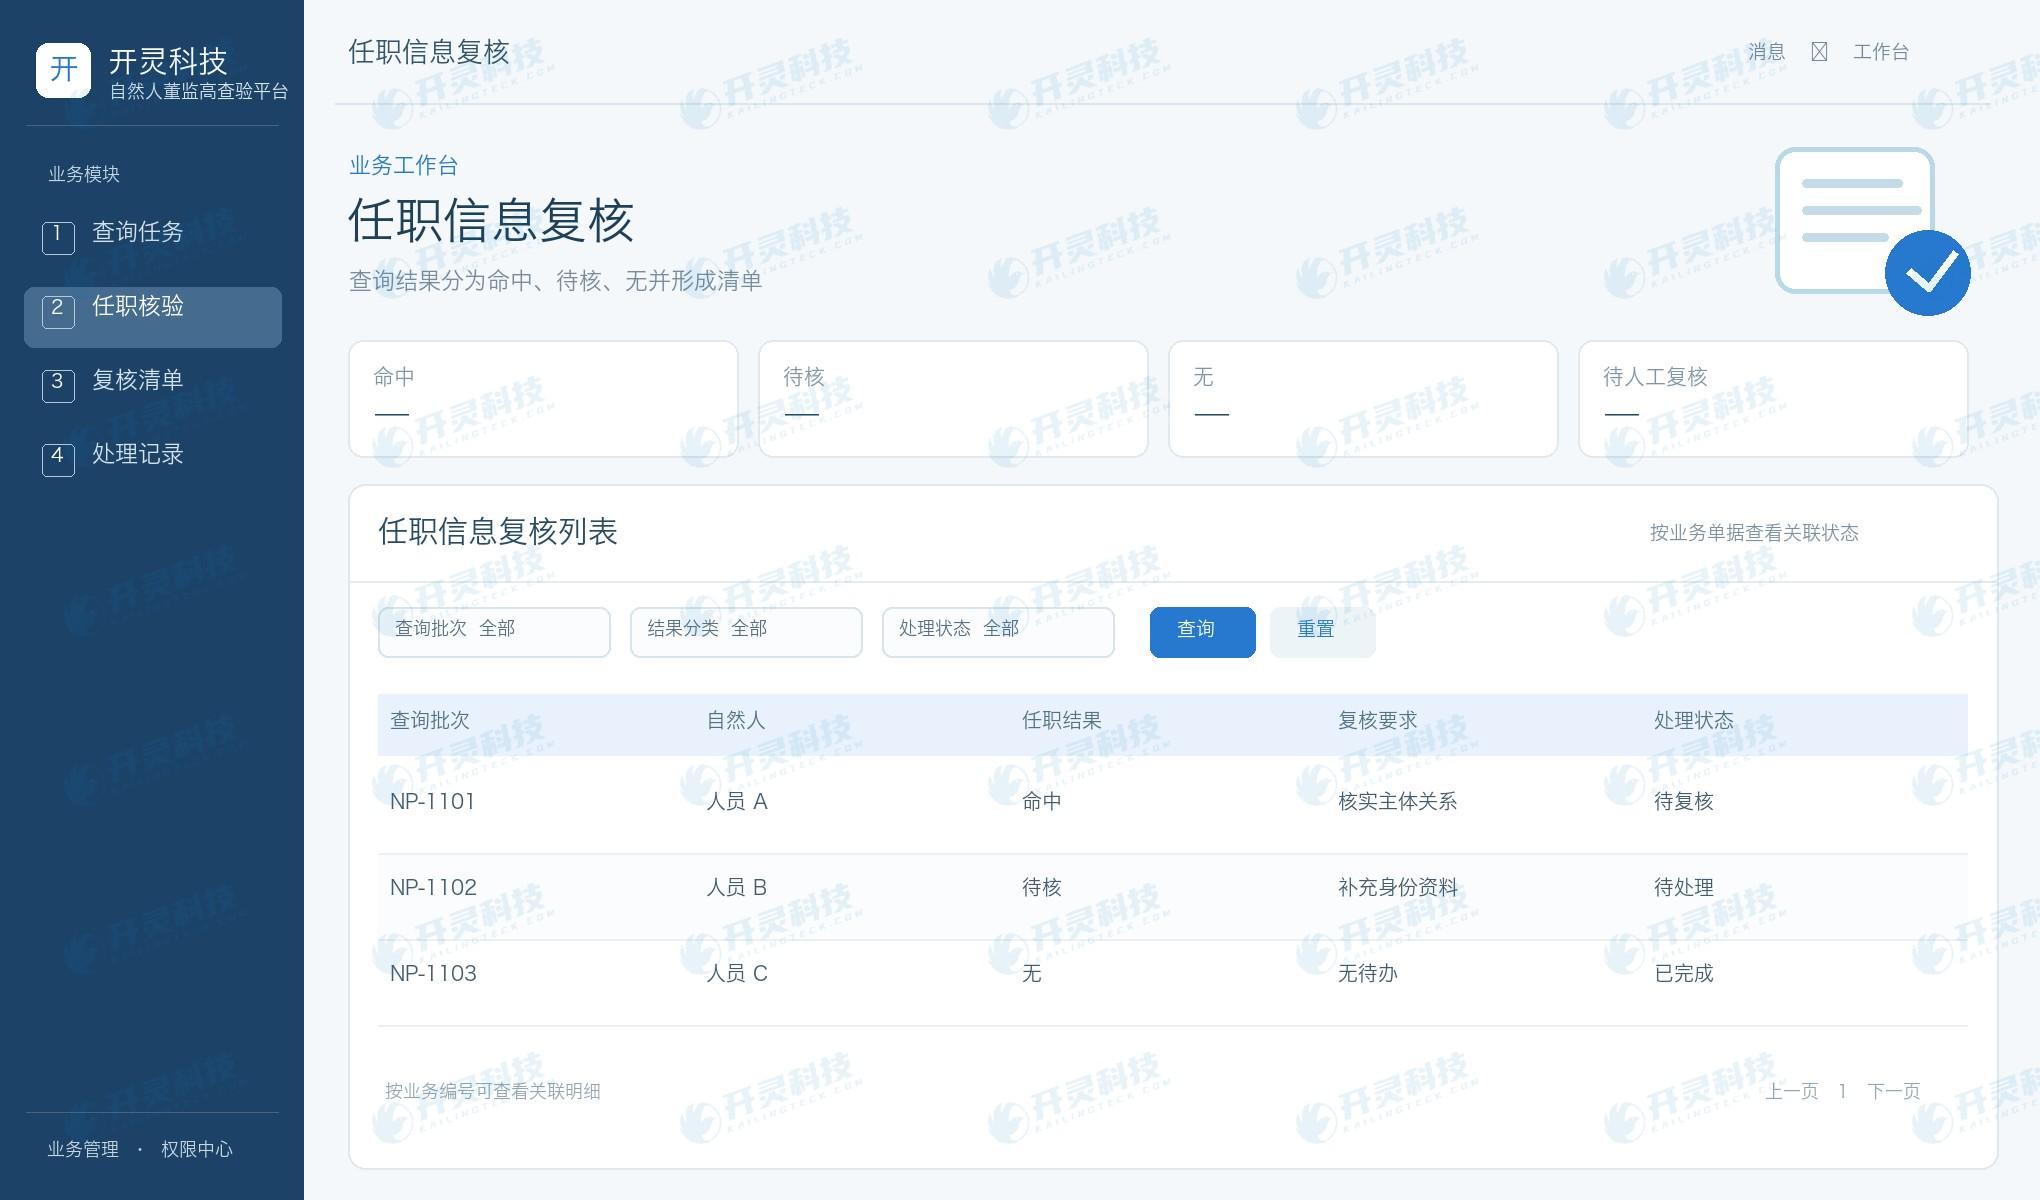
Pending verification is not a gray label that can be left hanging long-term. The handler may be required to supplement identity document information, confirm the employing entity, contact the seller to explain the transaction background, or ask the tax position to verify applicable eligibility. Each task specifies the responsible person, deadline and required materials, and the system then shows completed and incomplete status.
If subsequent data proves it was only a false match with the same name, the exclusion basis and reviewer should be retained; if it is verified that the person did hold a position, it should also be recorded whether that position is related to the current transaction. Deleting the original "pending verification" record and leaving only the conclusion would make it impossible for the next finance staff member to understand why it was released or suspended at the time.
▍Connecting with reverse invoicing business orders
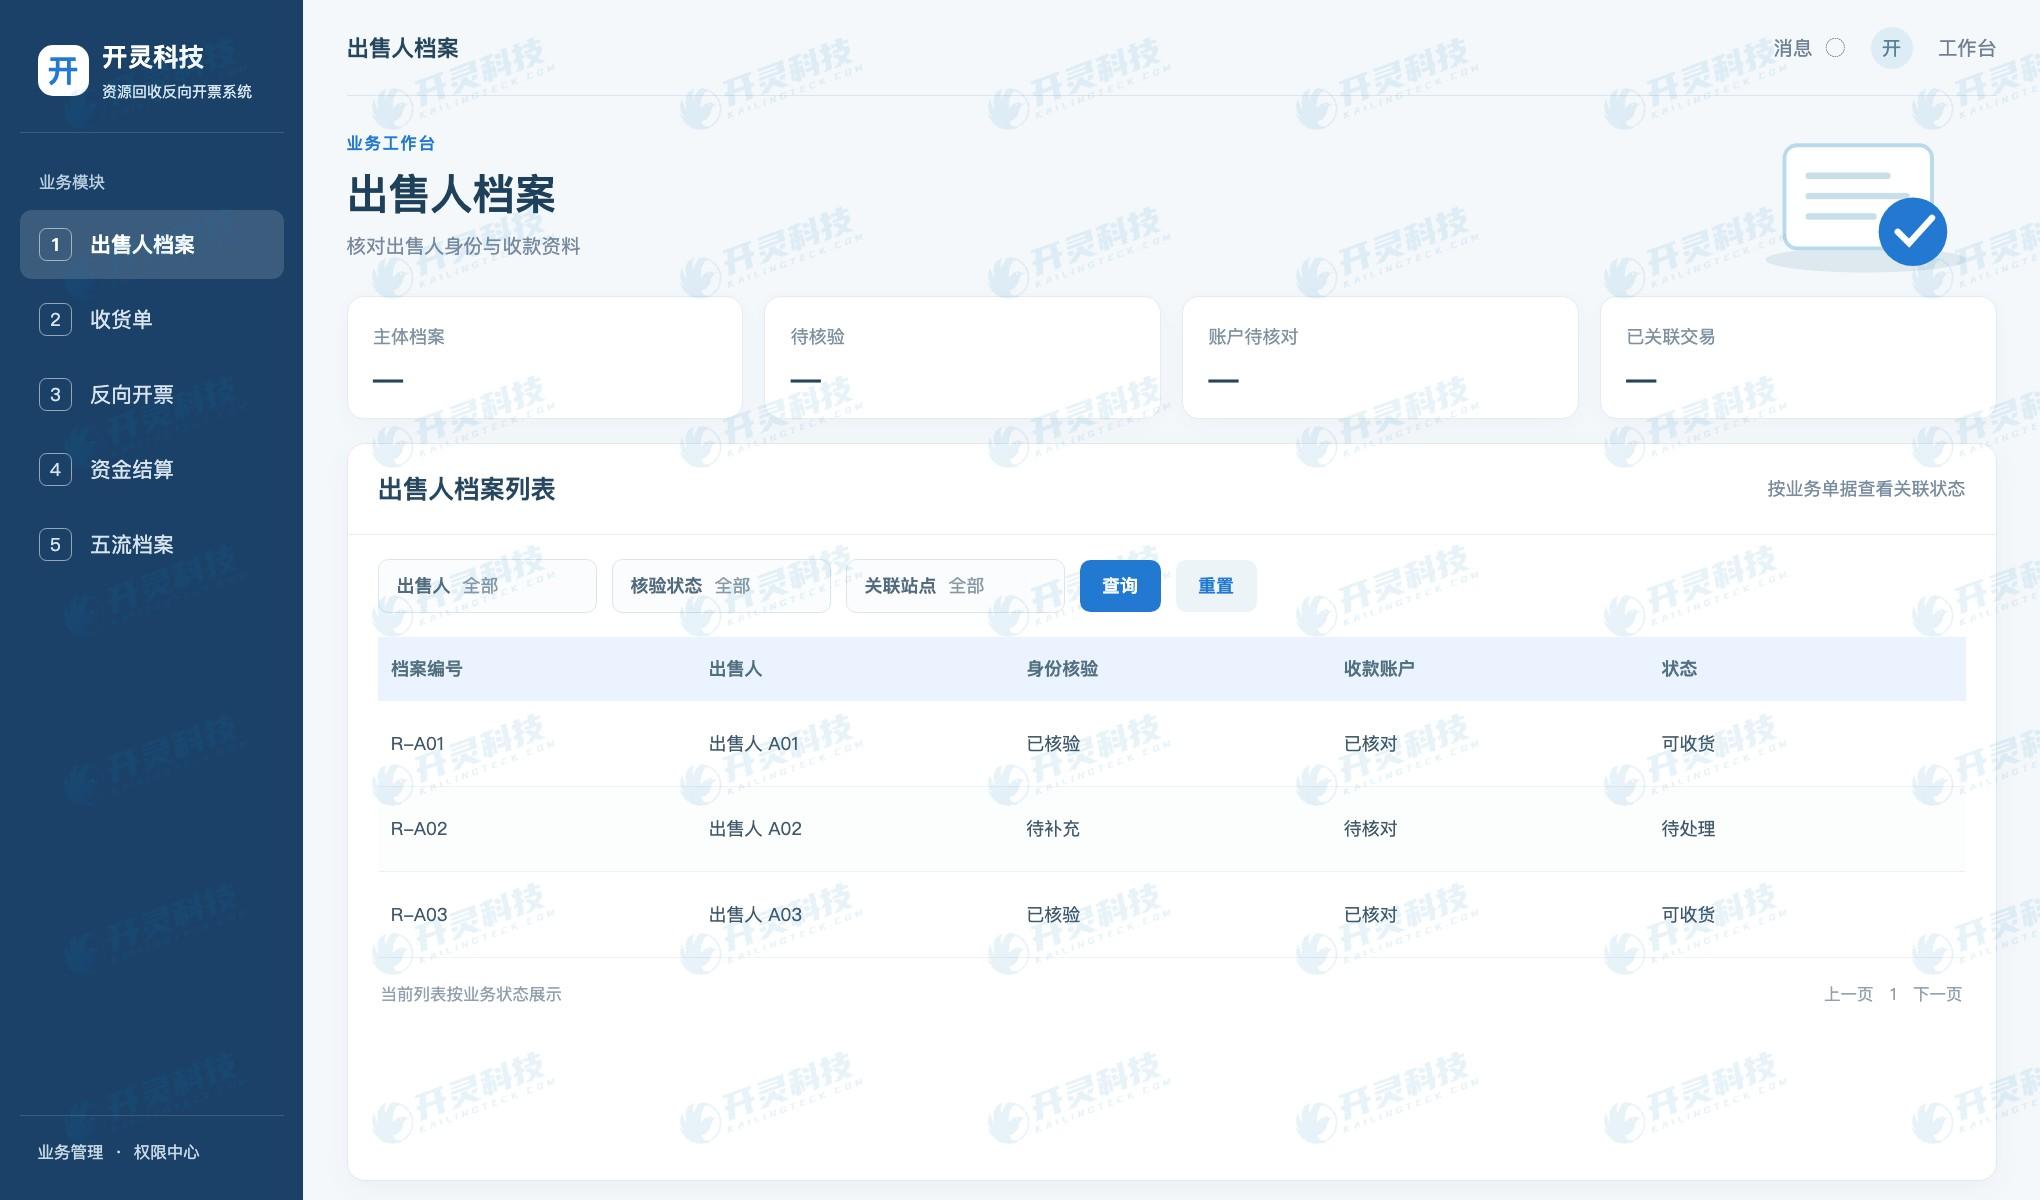
Resource recycling reverse invoicing also requires judging conditions such as enterprise qualifications, the identity of the natural person seller of scrapped products, the actual acquisition and the amount. Director and senior executive verification only resolves one type of subject clue and cannot replace verification of receipt, payment and transaction authenticity. Platform results should be linked back to the seller file and specific business order so that the invoicer can see the latest review opinion for this transaction.
For multiple high-frequency acquisitions, related transactions can be aggregated by natural person, with alerts for first matches, result changes, and expired materials. The Kailing Technology platform generates a review checklist to help enterprises apply limited manual review to genuine doubts; businesses with a "none" result still need to continue verifying other invoicing conditions.
▍Test the processing flow with three types of samples
Select three samples: confirmed position, same-name pending verification, and no match, then add incomplete identity information and subsequent position changes. Have business, finance, and tax personnel separately complete verification, review, and invoicing decisions, and check whether the system accurately retains time, materials, and conclusions.
The point is not to block every match, but to give each anomaly a clear handling path. The Kailing Technology natural person director, supervisor, and senior executive verification platform reduces verbal judgment through classification and record-keeping, and enterprises decide the final invoice handling based on actual transactions and policy conditions.
▍How the review checklist enters daily invoicing roles
The query entry can be placed at the natural person's first file creation and before each review of large or abnormal transactions. Handlers enter accurate identity elements, and the system displays the query time together with the results, avoiding treating records from several months ago as today's status. For natural persons with the same name, a name match alone must not be marked as a confirmed hit; identity document information should be supplemented first.
The checklist can separately record employing enterprises, positions, information status and issues to be verified. Finance does not need to take the same action for all hits: some are merely part-time or historical positions unrelated to the current scrap sale, while others require asking whether the goods belong to the employing enterprise. Handling opinions should correspond to specific business orders rather than writing a vague note on the person's file.
If the seller says the goods come from personal long-term accumulation, the actual delivery, settlement, and account still need to be verified on site; if enterprise personnel uniformly transport goods from multiple people, each actual seller must be separated out. Position verification flags potential entity-confusion risk and cannot replace verification of goods flow and fund flow.
Invoicing business with a "none" result should also undergo routine eligibility checks. Whether the natural person is a seller of scrapped products, whether the enterprise meets the conditions for reverse invoicing, and what the cumulative transaction situation is all need to be judged according to current rules. The system can display director/supervisor/senior executive results alongside other subject verifications, so that the invoicing person clearly knows how far each check has progressed.
When the reviewer approves continued processing, record the basis, date, and valid scope. If position information later changes or the goods ownership materials are inconsistent with the original explanation, historical conclusions should not be overwritten; new transactions enter re-review. This kind of version management is more useful than simply storing a screenshot of a query.
Enterprises can compile monthly statistics on the distribution of post-match handling, pending verification backlog, and same-name false-positive ratios, to optimize identity data collection and review guidance. The Kailing Technology platform turns personnel verification results into actionable to-dos, and managers can also see which doubts were already cleared before reverse invoicing.
▍Keep query results and business conclusions separately
The platform returns position information for review and should not directly write "can invoice" or "cannot invoice" in the result field to replace enterprise judgment. Business conclusions are filled in separately by authorized personnel and cite the specific acquisition order, entity materials, and verification basis. In this way, the same natural person can receive handling consistent with actual goods ownership under different transaction contexts.
If query results come from multiple enterprise records, verify item by item whether it is the same person, whether the position is still valid, and whether it is related to the current goods. For cases where the person has left but data has not been updated, record supplementary materials and review opinions, avoiding mechanically treating historical positions as current ones.
Subject review before reverse invoicing for natural persons also involves enterprise qualifications, seller consent and transaction authenticity. Director and senior executive verification can improve the efficiency of finding suspicious points, but it is only one node. Placing the status of each node on the same invoicing workbench makes it easier for finance to make a complete judgment.
▍FAQ
Q: If director/supervisor/senior executive employment is found, does that definitely mean reverse invoicing is not allowed?
A: A conclusion cannot be drawn from employment information alone; it should be verified whether the record belongs to the person and to the actual seller in this transaction, as well as the ownership of goods and applicable eligibility.
Q: Can "pending verification" be treated as "none" to continue invoicing?
A: Not advisable. First supplement identity and transaction materials, complete the review, and retain the conclusion.
Q: Do query results only need to be saved once?
A: The query time and results should be retained, and re-verification should be performed according to the rules when transactions continue or information changes.
Visit Kailing Technology to learn about related products and implementation plans:https://www.kailingteck.com/ziranren-chayan/ 。
As a national high-tech enterprise, Kailing Technology focuses on the digital and intelligent transformation of enterprise business-finance-tax and operations management, providing software products, system integration, implementation and delivery, and operational services for various government agencies, institutions, group enterprises, and SMEs.
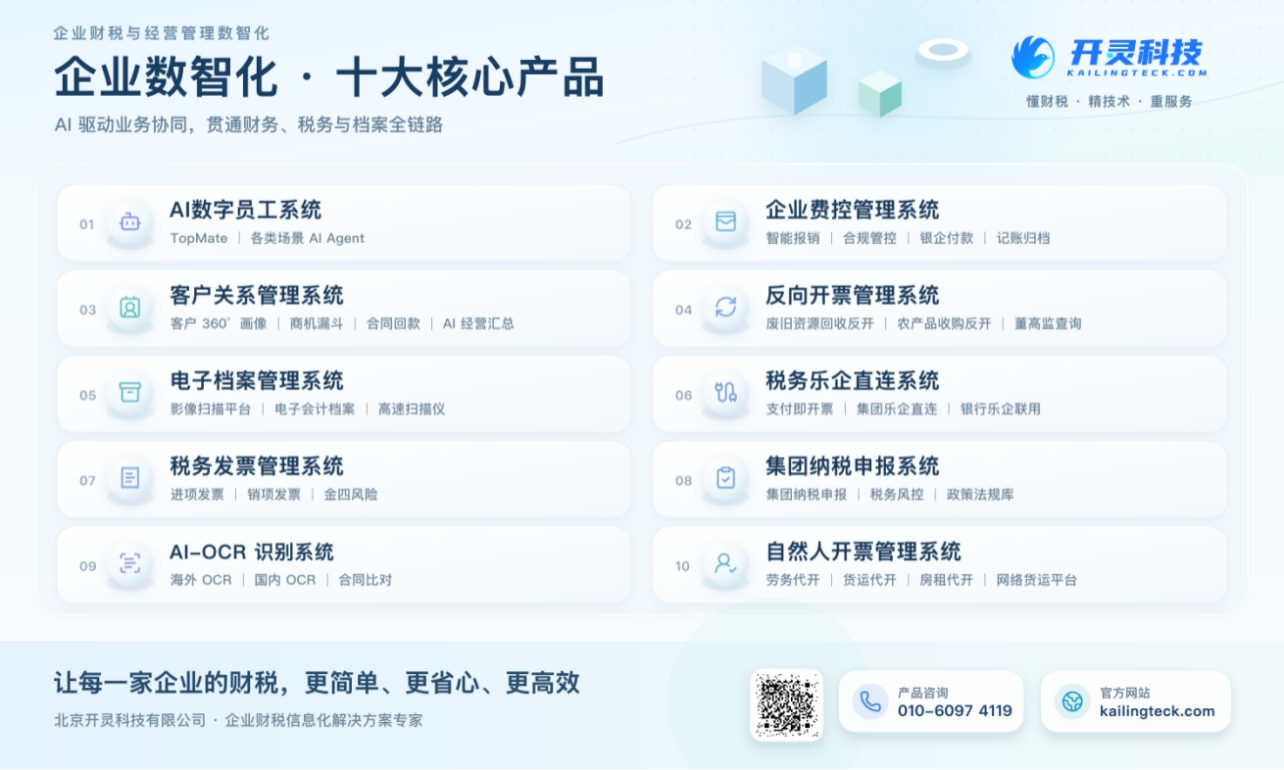
The company has now formed ten core product lines, including: AI digital employee system, enterprise expense control management system, customer relationship management system, reverse invoicing management system, invoice issuance for individuals management system, electronic archives management system, tax fully digitalized e-invoice Leqi system, tax invoice management system, group tax filing system, and AI OCR recognition system. It is committed to connecting enterprise business, finance, tax, funds, and archive data to help customers improve operational efficiency, business-finance-tax compliance capabilities, and digital management levels.
If you have any business-finance-tax digital transformation needs, welcome to contact us. Beijing Kailing Technology will serve you wholeheartedly.
Keywords: Natural person director and senior executive verification, reverse invoicing subject verification, position match, review checklist, Kailing Technology
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing