
How to issue invoices compliantly when the fishery industry purchases aquatic products such as crayfish and sea cucumbers? The Kailing Technology agricultural product purchase invoicing system retains five-flow evidence by batch
How to issue invoices compliantly when the fishery industry purchases aquatic products such as crayfish and sea cucumbers? The Kailing Technology agricultural product purchase invoicing system retains five-flow evidence by batch
After live crayfish arrive, they may first be held temporarily and then weighed, while sea cucumbers may be inspected in low-temperature boxes as fresh products or in other states. For the same truck of aquatic products, the weighed weight, settleable quantity and actual source may all change within a short time. If finance only looks at one consolidated amount to issue purchase invoices, it will be difficult to match cold chain notes, holding losses and farmer confirmations. In fishery scenarios, the Kailing Technology agricultural product purchase invoicing system should use the arrival batch as the anchor and retain the sequence relationships among source, measurement status, inspection, payment and invoices.
▍Determine the source first: farmers, fishermen, and distributors must not be conflated
The current agricultural product scope notes include fish, shrimp, crabs, shellfish, and other aquatic products obtained through artificial breeding and artificial fishing within the scope of agricultural products; specific goods also depend on variety and processing status. The tax exemption treatment for agricultural producers selling self-produced primary agricultural products applies to entities directly engaged in breeding, fishing, and selling the corresponding self-produced products; resellers who purchase and resell cannot be filled in as self-producers merely because they sell crayfish or sea cucumber. Enterprises should verify the seller's identity, breeding or fishing activities, and the actual source of the batch of goods.
Filing can record business information such as aquaculture waters, commonly sold varieties, fishing methods, contact details and payment accounts. When a farmer who usually delivers live crayfish temporarily sells a large amount of sea cucumbers, the system should remind staff to verify the new source rather than copying the old file. If goods are delivered in bulk by a broker, distinguish the broker's service role, the actual seller and the ownership of payment; do not put aquatic products from multiple households under one natural person's name merely for invoicing convenience.
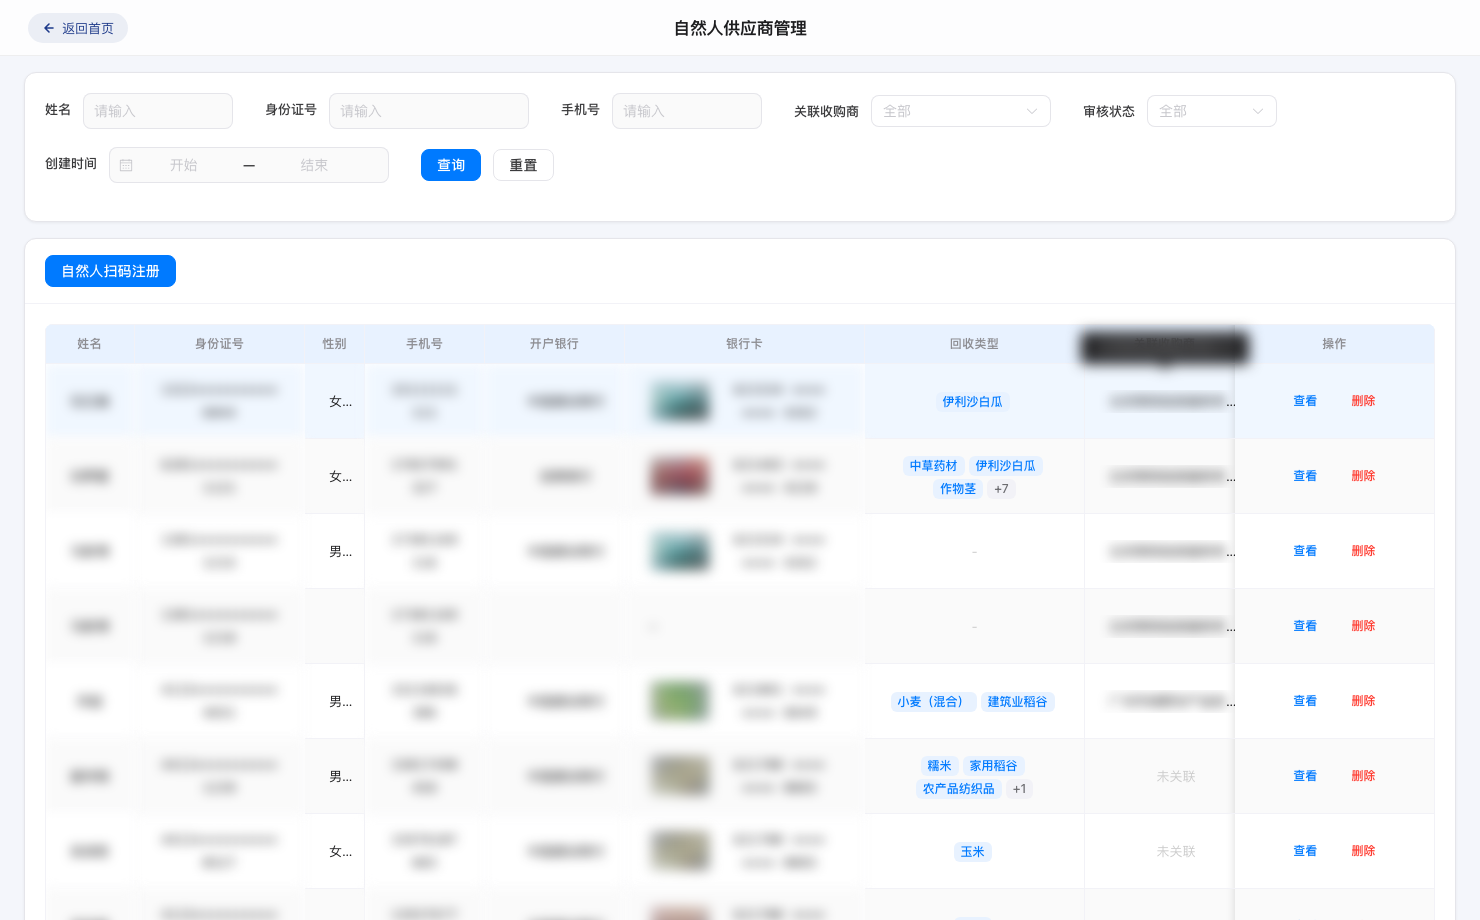
Example of agricultural producer profile creation interface
▍Batch numbers must follow the status of the aquatic products
For crayfish purchases, record live quantity, arrival weight, holding time, grading and mortality loss; for sea cucumbers, distinguish fresh products, refrigerated or other delivery states. When there is a difference between the entry weight and the final settleable weight, retain the reason for the intermediate steps, the reviewer and the confirmation result, and do not directly overwrite the first weighing value. The batch number runs from unloading, sampling, holding or cold chain storage all the way to settlement, so it can explain that the invoice amount was not generated out of thin air.
If one truck mixes goods from multiple farmers or different waters, the transport information can be shared, but the purchase note should be separated by household, variety and batch. When temporary holding ponds are managed jointly, the inbound quantity, outbound quantity and allocation rules of the source batch must still be retained; if part of the sea cucumbers is returned after sampling inspection, the returned quantity must also be deducted from the original batch. The system is responsible for retaining these statuses and correspondences, and on-site personnel are responsible for recording them truthfully; neither can be missing.
Cold chain records are not prepared only for the food quality department. If arrival temperature, packaging condition, unloading time and re-weighing results affect purchase grade or price, they should also return to the business batch as attachments or fields. If the party bearing in-transit loss differs from the party bearing post-storage loss for aquatic products, the purchase note must mark the boundary of responsibility, preventing finance from mistakenly recording storage-stage losses as farmers delivering less. Only then will subsequent invoicing amounts and cost accounting use the same confirmed facts.
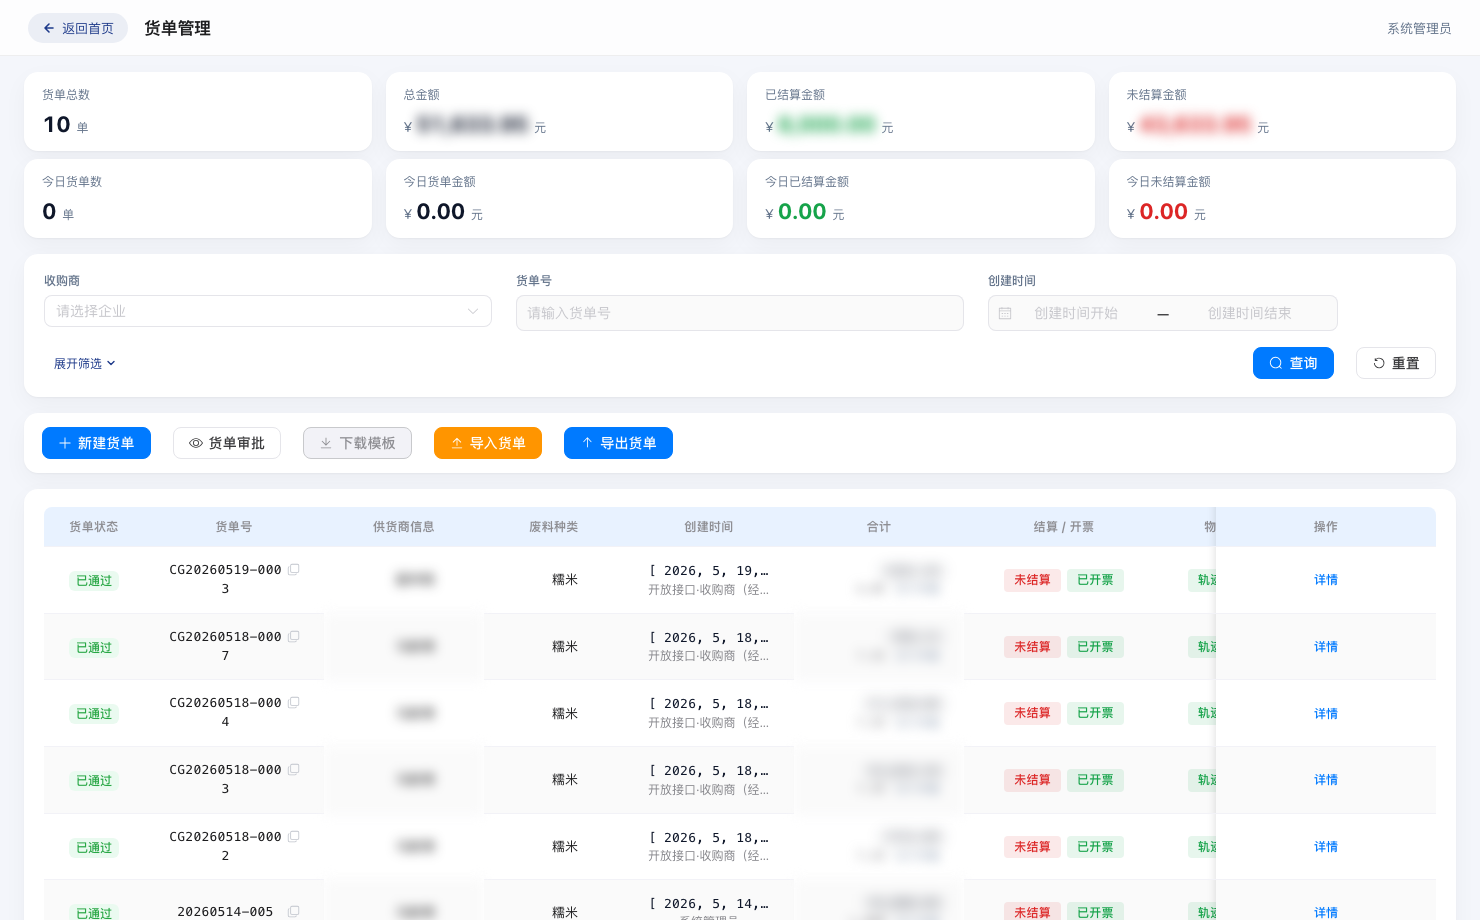
Sample agricultural product receiving note
▍Price formation must explain loss, grade, and transport conditions
Aquatic product prices may be affected by specifications, fresh/live status, and delivery conditions. Enterprises should write grade determination, pricing units, and price effective time into settlement rules, avoiding back-calculating a series of unsupported unit prices from the final total price. Matters such as who bears temporary holding losses, whether ice glaze or packaging is counted in weight, and how deductions are made for abnormal arrival temperatures all belong to items that must be clarified in contracts or purchase agreements; the system should retain the rule version used and confirmation by both parties.
When finance forms payables, first summarize confirmed quantities and unit prices by batch, then handle supported adjustment items. Batches that have not completed quality inspection or whose source is pending verification are placed in the pending settlement queue and are not invoiced together with confirmed goods. If the same farmer delivers over several consecutive days and is paid in a lump sum, the accounts may summarize by household, but each amount must be broken back to the original batch, acceptance, and price difference explanation.
▍Both purchase invoices and payments start from the batch settlement statement
Before issuing agricultural product purchase invoices, verify the actual agricultural producer, goods name and status, quantity, settlement amount and applicable invoice conditions. General VAT taxpayers that obtain or issue compliant agricultural product sales invoices or purchase invoices may calculate input VAT based on the invoice purchase price and the current deduction rate, but this calculation cannot replace verification of self-production and transaction authenticity. Invoice numbers and invoicing results are written back to the source batch, and adjustments and red-letter reversals are handled according to facts when returns, loss rechecks or price changes occur.
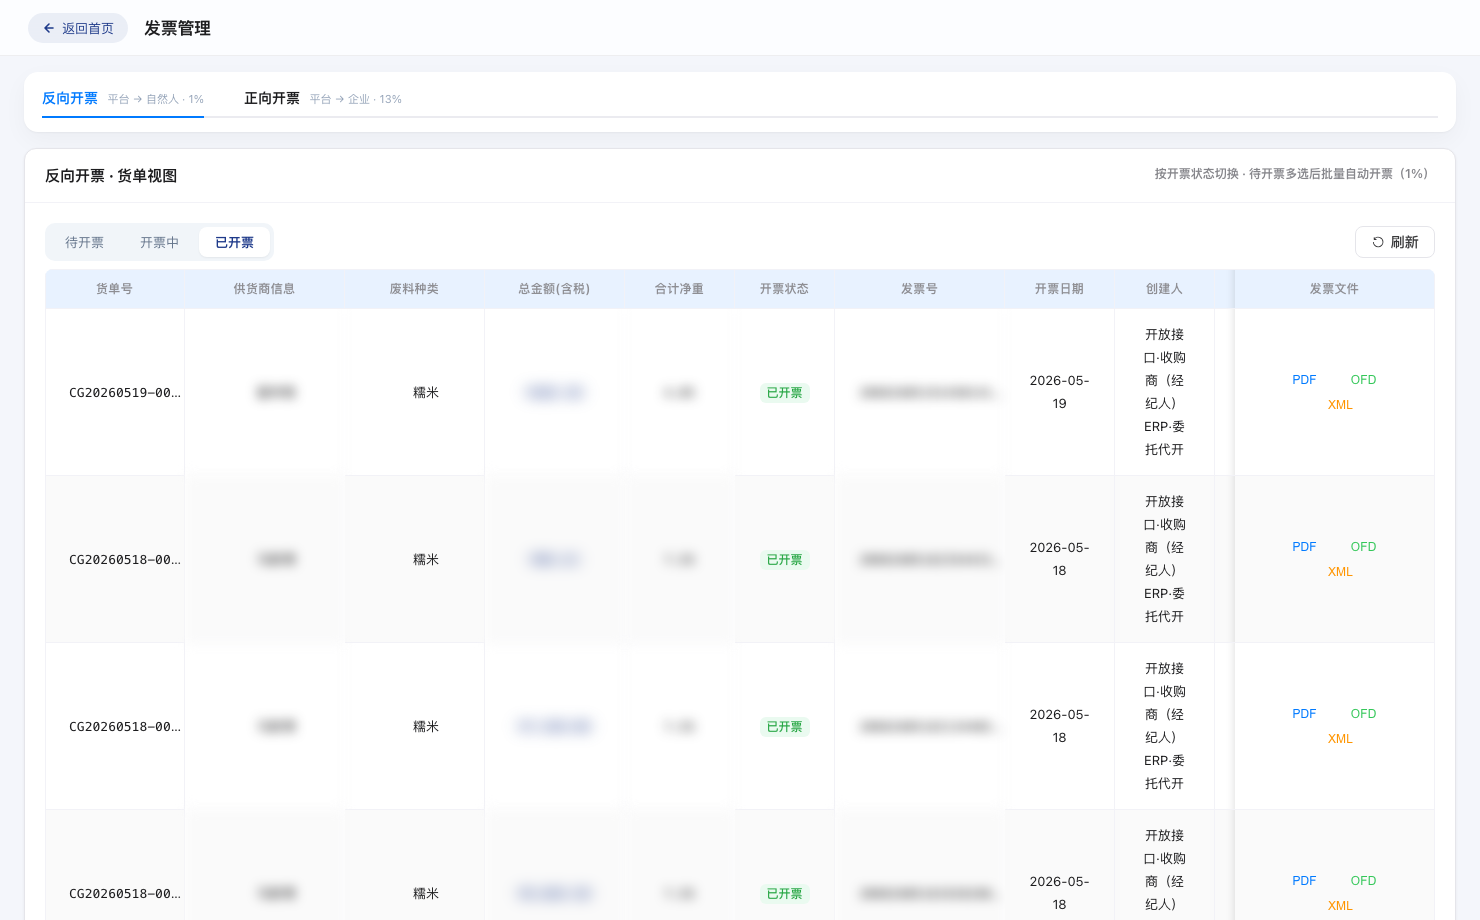
Sample agricultural product purchase invoice note
The funds side must be able to verify the breeder or fisher's account against the confirmed settlement statement. For installment payments, it should be clearly traceable which batches each payment covers and how much remains; when payment fails or the account changes, review traces should be retained. Bank receipts should not simply be dropped into a finance folder by date; they should also be linked back to the seller and original aquatic product batch. In this way, although tax invoices and funds may be generated at different times, both can return to the same purchase.
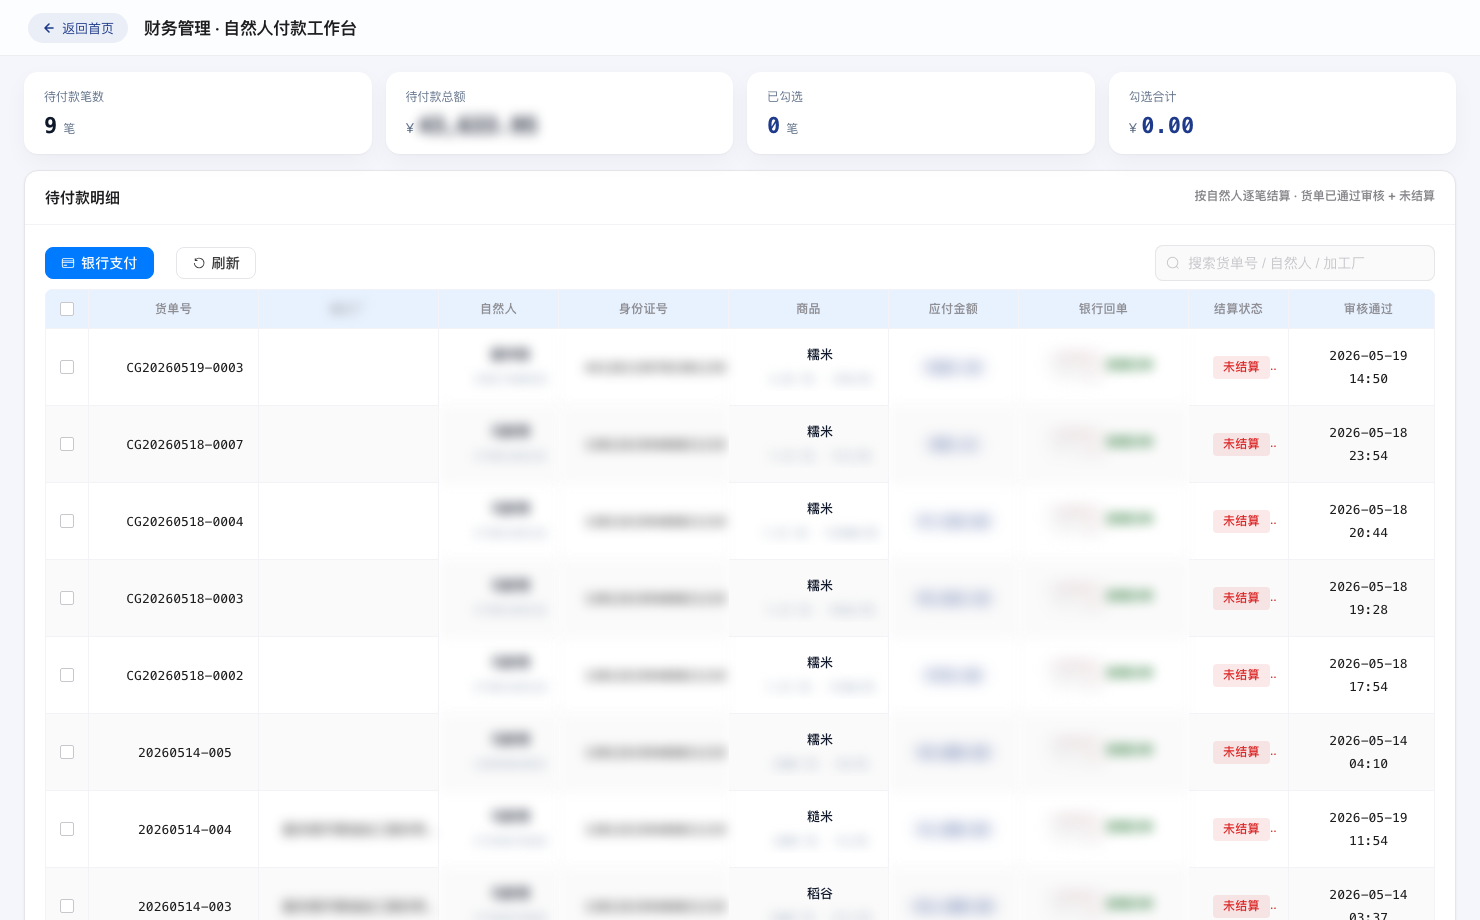
Example of agricultural producer payment workbench
▍Five-flow evidence must support bidirectional tracing from one box of goods and one invoice
The five-flow evidence of the Kailing Technology agricultural product purchase invoicing system is an internal management method that organizes self-production proof, purchase agreements, goods business, tax invoices and fund payments by transaction; it is not a separate set of five statutory forms. For aquatic product enterprises, a box of goods can be traced to which farmer or fisher, which arrival batch, and how it was inspected and priced; a purchase invoice can trace back all the box shipments and bank payments it covers. If source or loss evidence is missing, the archive indicates the gap and the position responsible for supplementary evidence, and cannot replace goods facts with "both invoice and payment exist."
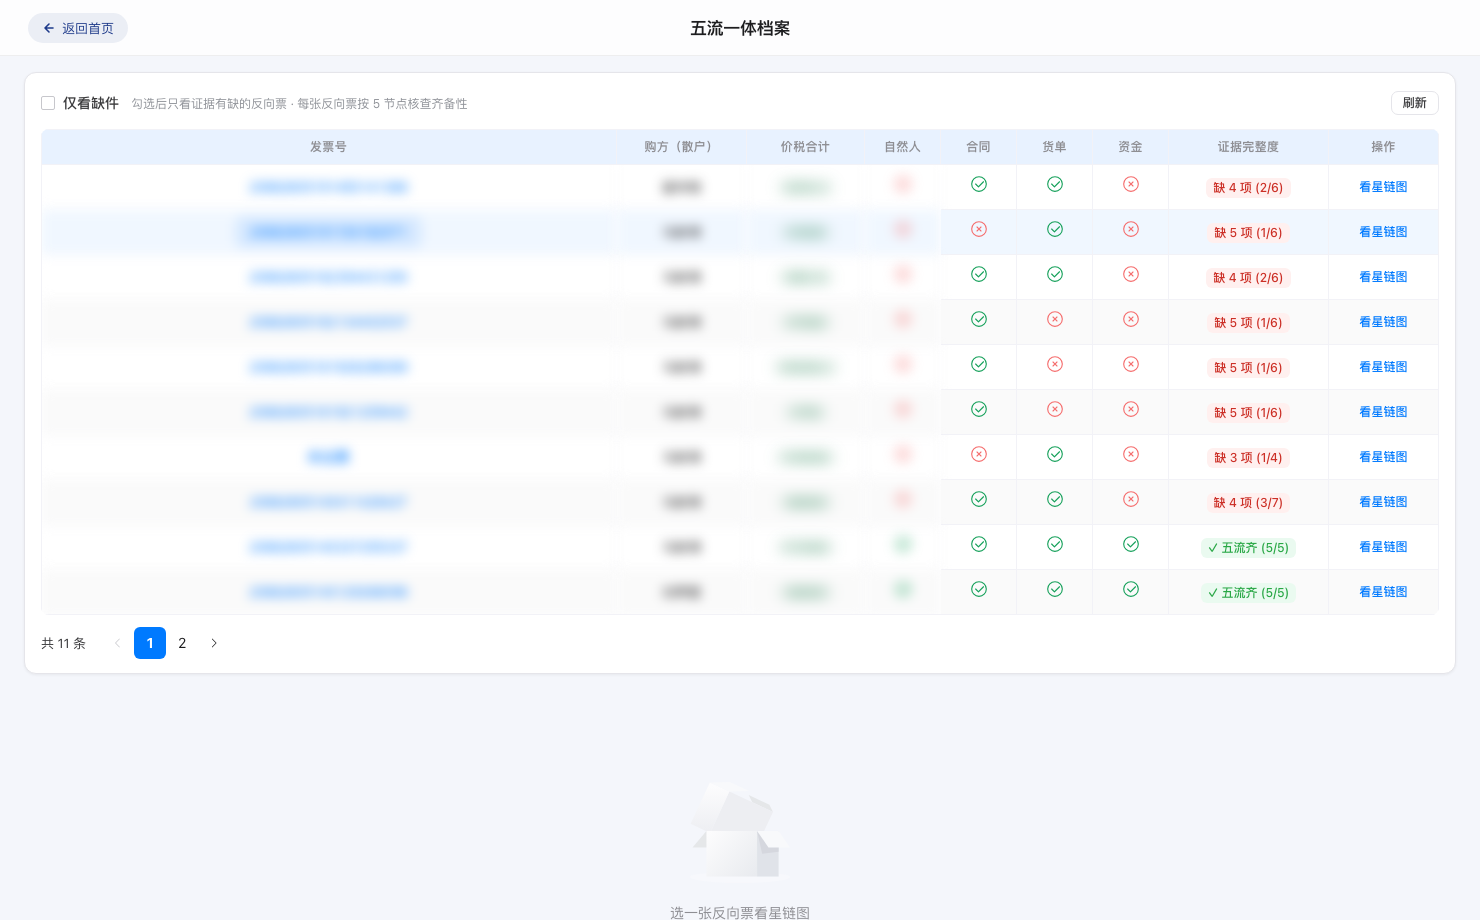
Five-flow evidence archiving example
Launch testing can select three boundaries: temporary holding loss of crayfish after entry, sea cucumber sampling rejection, and mixed loading of aquatic products from multiple households in the same vehicle. Verify item by item whether the original weight and settlement weight are each retained, whether abnormal batches can be individually suspended, and whether invoice payments accurately point back to the source. The Kailing Technology system can handle batch linking and pre-invoicing verification, but ultimately the enterprise still needs purchasing, quality inspection, warehousing, and finance to collaborate under the same standards.
▍FAQ
Q: If crayfish weight changes after temporary holding, which number is used for the invoice?
A: It should be based on the agreement between both parties and the final confirmed actual purchase settlement result, while retaining entry, temporary holding, and adjustment records.
Q: If sea cucumbers are delivered by a broker, should the broker be recorded as a self-produced household?
A: It cannot be handled that way directly. The actual seller and the source of the goods should be verified, and the invoice and payment attribution determined according to the real transaction.
Q: Can multiple households' aquatic products in the same vehicle share one cold-chain document?
A: Transport documentation can be linked to the same vehicle information, but each household's source, variety, quantity, settlement, and invoice payment should be verified separately.
Q: After five-flow evidence is retained, is on-site acceptance no longer needed?
A: No. The system records and links evidence, but actual quality, quantity, and condition still require on-site verification by personnel.
Make every batch of aquatic products traceable from source to settlement, payment, and invoice. Learn about the Kailing Technology agricultural product purchase invoice solution:https://www.kailingteck.com/fxncp/ 。
As a national high-tech enterprise, Kailing Technology focuses on the digital and intelligent transformation of enterprise business-finance-tax and operations management, providing software products, system integration, implementation and delivery, and operational services for various government agencies, institutions, group enterprises, and SMEs.
The company has now formed ten core product lines, including: AI digital employee system, enterprise expense control management system, customer relationship management system, reverse invoicing management system, invoice issuance for individuals management system, electronic archives management system, tax fully digitalized e-invoice Leqi system, tax invoice management system, group tax filing system, and AI OCR recognition system. It is committed to connecting enterprise business, finance, tax, funds, and archive data to help customers improve operational efficiency, business-finance-tax compliance capabilities, and digital management levels.
If you have any business-finance-tax digital transformation needs, welcome to contact us. Beijing Kailing Technology will serve you wholeheartedly.
Keywords: Fishery purchase invoices, Kailing Technology agricultural product purchase invoices, crayfish and sea cucumber purchases, aquatic product batch evidence retention, five-flow integration
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing