Individual income tax filing always goes wrong? How to fix mismatches between the payroll sheet and the filing form
Individual income tax filing always goes wrong? How to fix mismatches between the payroll sheet and the filing form
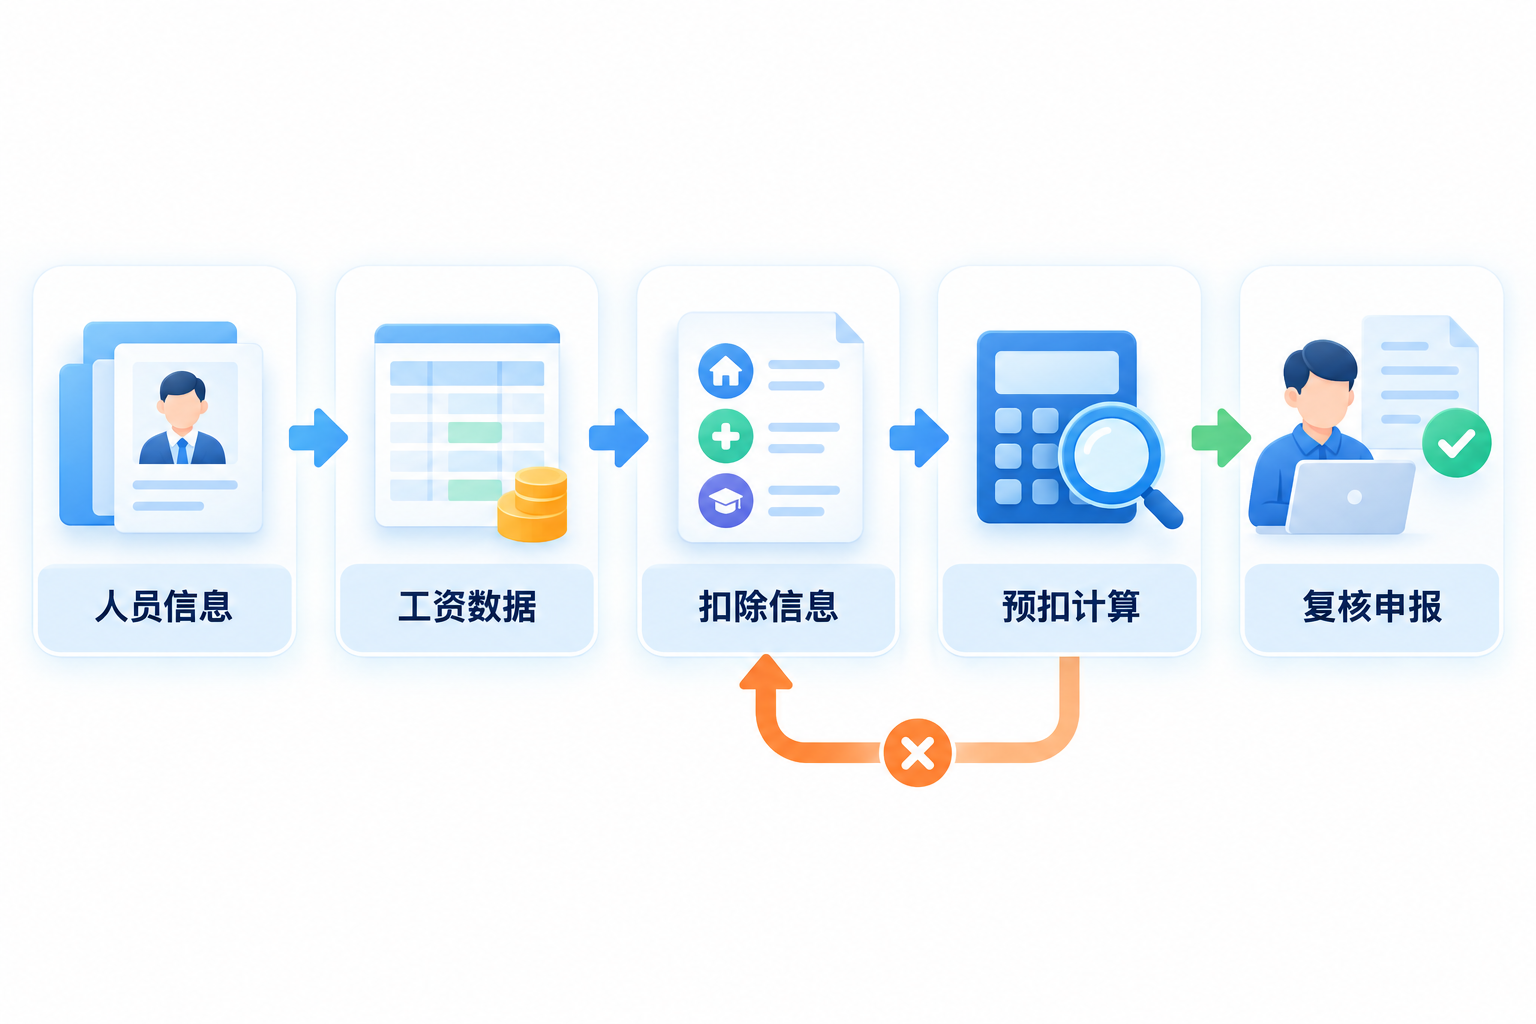
When the monthly filing period arrives, what finance fears most is not VAT but individual income tax: new hires not collected, departures not stopped, special additional deductions not updated, and the payroll sheet and filing form simply cannot be aligned; if filed incorrectly, you still have to run a correction filing. In fact, the operation of individual income tax filing itself is not complicated; what is difficult is where the data comes from and how to ensure there are no errors. Once personnel, wages and salaries, and deduction information are sorted out, the system can assist with data retrieval, calculation, verification, and generation of filing working papers within the scope of enterprise authorization, interface support, and rule configuration; the withholding agent should still review in the end and complete the filing through currently approved channels.
"The difficulty of individual income tax filing is not in clicking a few buttons, but in aligning the three tables: payroll, personnel information, and deduction items — the faster you file, the more errors you make." |
▍1. Personnel information collection: why is it always remembered only during the filing period?
The starting point of withholding and filing for wages and salaries is accurate personnel information. When new hires, departures, or changes in ID information occur, they should be maintained promptly according to the actual situation; after a filed employee leaves, the personnel status is usually changed to "abnormal" in the withholding client of the Natural Person Electronic Tax Bureau, and the specific operation is subject to the current system guidance. A bank card change itself is not a legally required core field for personnel withholding filing. The system can assist in collecting personnel materials and flagging differences within the scope of enterprise authorization, but before filing it still needs to be reviewed based on the actual employment and payroll situation.
▍2. Special additional deductions: how to ensure nothing is missed or duplicated?
According to"Individual Income Tax Law of the People's Republic of China", if a resident individual provides special additional deduction information to the withholding agent, the withholding agent should deduct it as required during monthly withholding and prepayment. Employees can provide information through the Individual Income Tax APP, the Natural Person Electronic Tax Bureau web portal, or a deduction information form; when choosing to have the withholding agent handle withholding and prepayment deductions, the withholding agent should download updates promptly on the withholding client and fulfill confidentiality obligations for the information received. The system can assist in comparing personnel, years, and deduction status, but cannot replace employees' truthful reporting or the withholding agent's lawful handling.
▍3. What is used to automatically align the payroll sheet with the filing form?
The payroll sheet and withholding filing data may differ due to different bases for gross pay, net pay, deductions, and tax calculation. Items such as year-end bonuses, back pay, and tax-exempt income should be judged based on the actual payment time, nature of income, and current policy, and cannot be automatically classified solely by payroll sheet notes. The system can generate filing working papers and difference lists according to configured rules; calculation results, applicable policies, and personnel status still need to be reviewed by the withholding agent, and filing and feedback should be done through currently approved channels.
▍4. Is it over once the filing is done? Risk scanning cannot be skipped
A successful submission of an individual income tax filing does not mean review is unnecessary. Before filing, you can check personnel status, wages and salaries, deduction information, duplicate records, and data fluctuations; an individual obtaining wages and salaries from multiple sources is not in itself a violation and should be handled based on the actual employment and income situation. The system can provide data checks, risk alerts, and audit trails according to configured rules, but alerts cannot be directly equated with a tax authority determination, nor can they replace the withholding agent's filing responsibility.
Keywords: individual income tax filing, individual income tax withholding filing, withholding and prepayment of wages and salaries, personnel information collection, special additional deductions, filing review, tax risk alerts, Kailing Technology
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing