How to choose an invoice issuance platform for individuals? First look at the business, documentation, and tax closed loop
How to choose an invoice issuance platform for individuals? First look at the business, documentation, and tax closed loop
When enterprises temporarily hire lecturers, consultants, or drivers, or lease housing from individuals, they often encounter problems such as individuals not knowing how to handle the process, repeated document supplementation, and finance being unable to obtain compliant vouchers in a timely manner. When choosing a platform, you cannot only ask "can it issue invoices in batches" or "how long until the invoice is issued"; you must first confirm the real business, applicable scenarios, applicant entity, processing channel, tax responsibility, and evidence retention. A platform can improve the efficiency of document organization and process collaboration, but it cannot replace tax authority review, nor can it fit businesses of different natures into the same invoicing template.
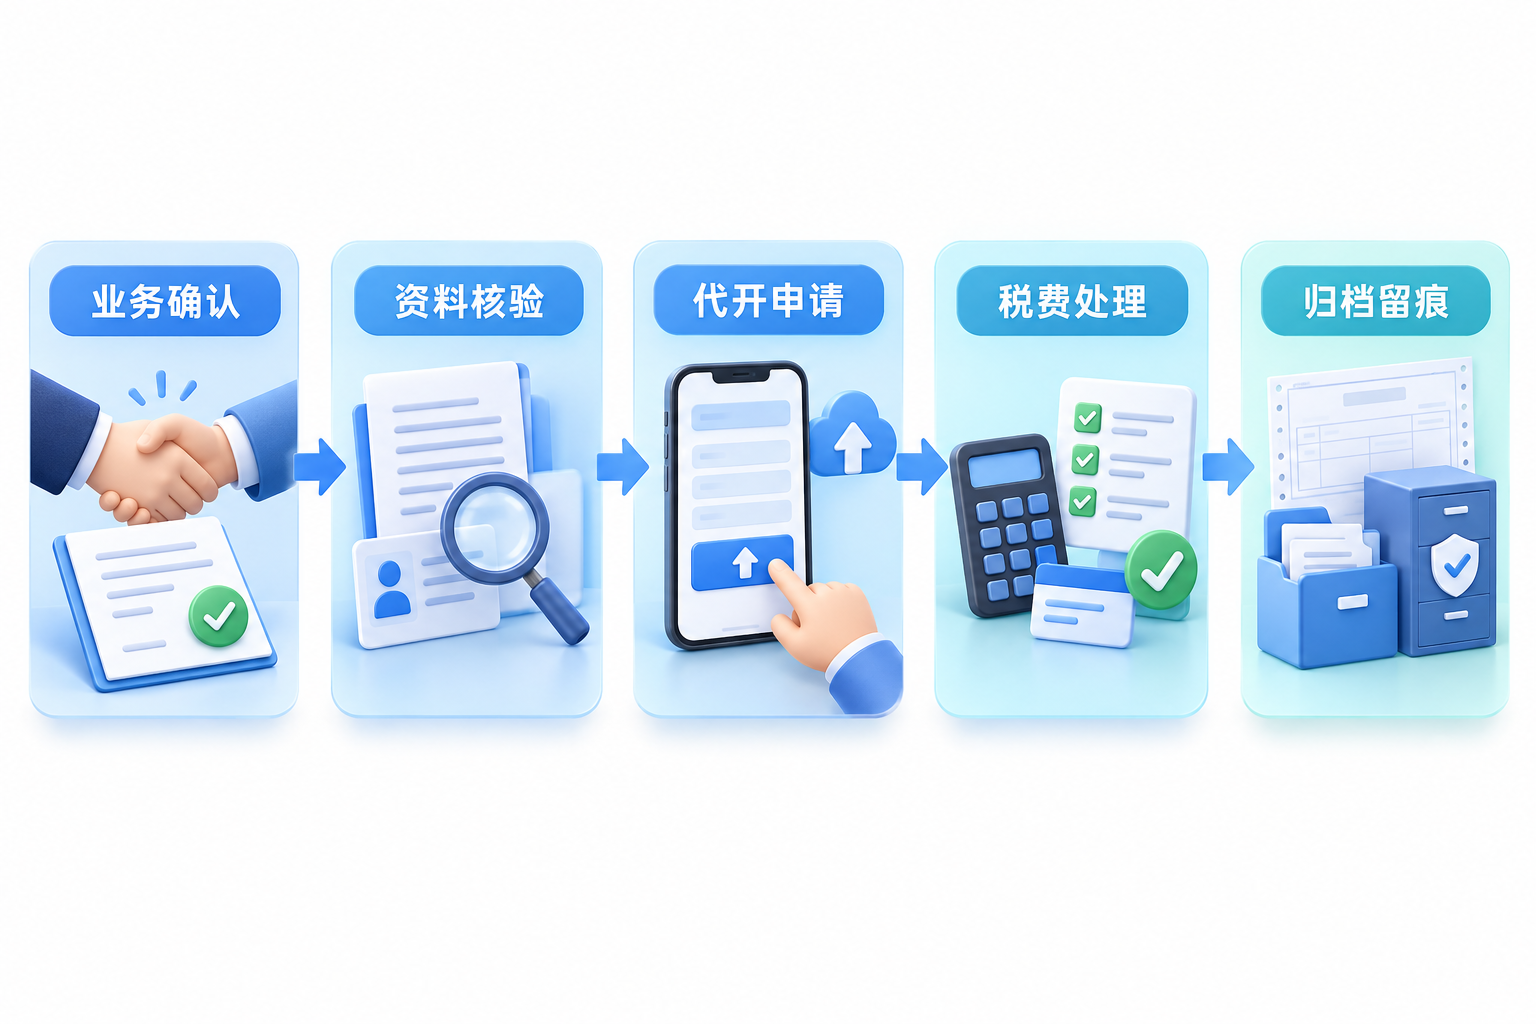
Invoice issuance for individuals is not "finding a platform to supplement an invoice," but placing the business, application, tax, payment, and archiving into a verifiable chain. |
▍1. First check whether the platform clearly states "who is issuing the invoice"
"Measures of the People's Republic of China for the Administration of Invoices"It is stipulated that units and individuals that need to use invoices temporarily may, on the strength of written proof of business activities and the identity certificate of the handler, apply to the tax authority at the place of business for invoice issuance; tax authorities may also, in accordance with regulations, entrust other units to issue invoices. Therefore, commercial software or service platforms usually undertake work such as document collection, process collaboration, status tracking, and document return, and cannot describe themselves as invoicing entities free from conditions. When selecting a platform, the actual processing channel, applicable regions, authorization method, and failure handling should be verified.
▍2. A real business is the prerequisite; you cannot "issue the invoice first and supplement the contract later"
Q&A of the State Taxation Administration on compliant invoice issuanceEmphasize that the business carried by an invoice should be real and valid, have a reasonable commercial purpose, conform to common trading sense, and in principle align with the contract flow, goods or service flow, fund flow, and invoice flow. Before initiating an application, enterprises should clarify the service provider, service content, time of occurrence, acceptance results, amount payable, and receiving account. Applications lacking a real business or deliberately changing the product name, amount, or entity should be intercepted and transferred for manual handling.
▍3. Labor services, freight, and housing leasing cannot share one set of rules
Lecturing and consulting usually involve labor remuneration, goods transportation requires a corresponding real carriage relationship and transportation records, and housing leasing is related to the location of the real estate, the lease contract, and ownership documents. Online entry points, document checklists, tax handling, and review times may differ across regions. Kailing Technology separately providesInvoice issuance on behalf of natural persons for labor services、Individual freight issuanceandHousing rental issuanceScenario solutions; during project implementation, the specific available scope should still be confirmed according to the place where the business occurs, the requirements of the competent tax authority, and enterprise authorization.
▍4. Issuing an invoice does not mean all tax obligations have been fulfilled
The invoice issuance step is not the same action as individual income tax withholding, enterprise payment, and subsequent filing. Taking labor remuneration as an example,Public reply from the tax authorityMake clear that units or individuals paying labor remuneration to individuals are withholding agents and should withhold and prepay individual income tax in accordance with the law; resident individuals may also be involved in the annual comprehensive income settlement. The tax categories, collection methods, and filing responsibilities of other businesses should be handled according to applicable policies and the competent tax authority's interpretation. The system should record invoicing status, tax payment or withholding status, and payment status separately, and cannot use "invoiced" to replace "all tax handling completed."
▍5. Batch processing must have validation, authorization, and exception branches
Batch import can reduce duplicate entry, but it should not skip item-by-item business validation. The platform should at least check the individual's identity and authorization, purchaser information, business type, contract or confirmation records, amount relationships, and receiving information, and give clear statuses for situations such as missing documents, identity authentication failure, inapplicable regions, review rejection, and tax payment failure. When personal information such as ID documents, mobile phone numbers, and bank cards is involved, it should also be collected on the principle of minimum necessity, with access permissions, retention periods, and operation logs set.
▍6. Focus on verifying five things when selecting a platform
First, whether the platform clearly defines applicable regions, business types, and processing entities; second, whether it can link contracts, service or transportation records, payment information, and invoices item by item; third, whether it distinguishes invoicing, tax payment, withholding, and payment status; fourth, whether it can return for correction after failure and retain the reason; fifth, whether invoices, related vouchers, and processing logs can be downloaded according to authorization and entered into enterprise archives. Running the full process with several sets of normal and abnormal samples is more reliable than only looking at promotional terms such as "batch," "automatic," and "instant issuance."
Keywords: invoice issuance platform for individuals, invoice issuance for individuals, labor remuneration invoice issuance, freight invoice issuance, housing leasing invoice issuance, batch invoice issuance, compliant invoicing, Kailing Technology
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing