
Discovering budget overspending only after expenses occur? How Kailing Technology's AI expense control management system moves budget control forward to the application stage

Discovering budget overspending only after expenses occur is often not because budgets were not prepared, but because budgets, applications, approvals, and payments are not on the same chain. Kailing Technology's AI expense control management system can bring budget dimensions into expense applications, verify available limits by organization, department, project, and expense type before submission, and route overspending items into explanations, additional approvals, or manual judgment according to policy.
Budget upfront does not mean blocking everything when a red light appears. Enterprises should first distinguish insufficient budget, budget not issued, inconsistent budget basis, and genuine business exceptions, and then decide whether to prompt, occupy, escalate approval, or disallow submission.
▍1. First unify budget calibers and application fields
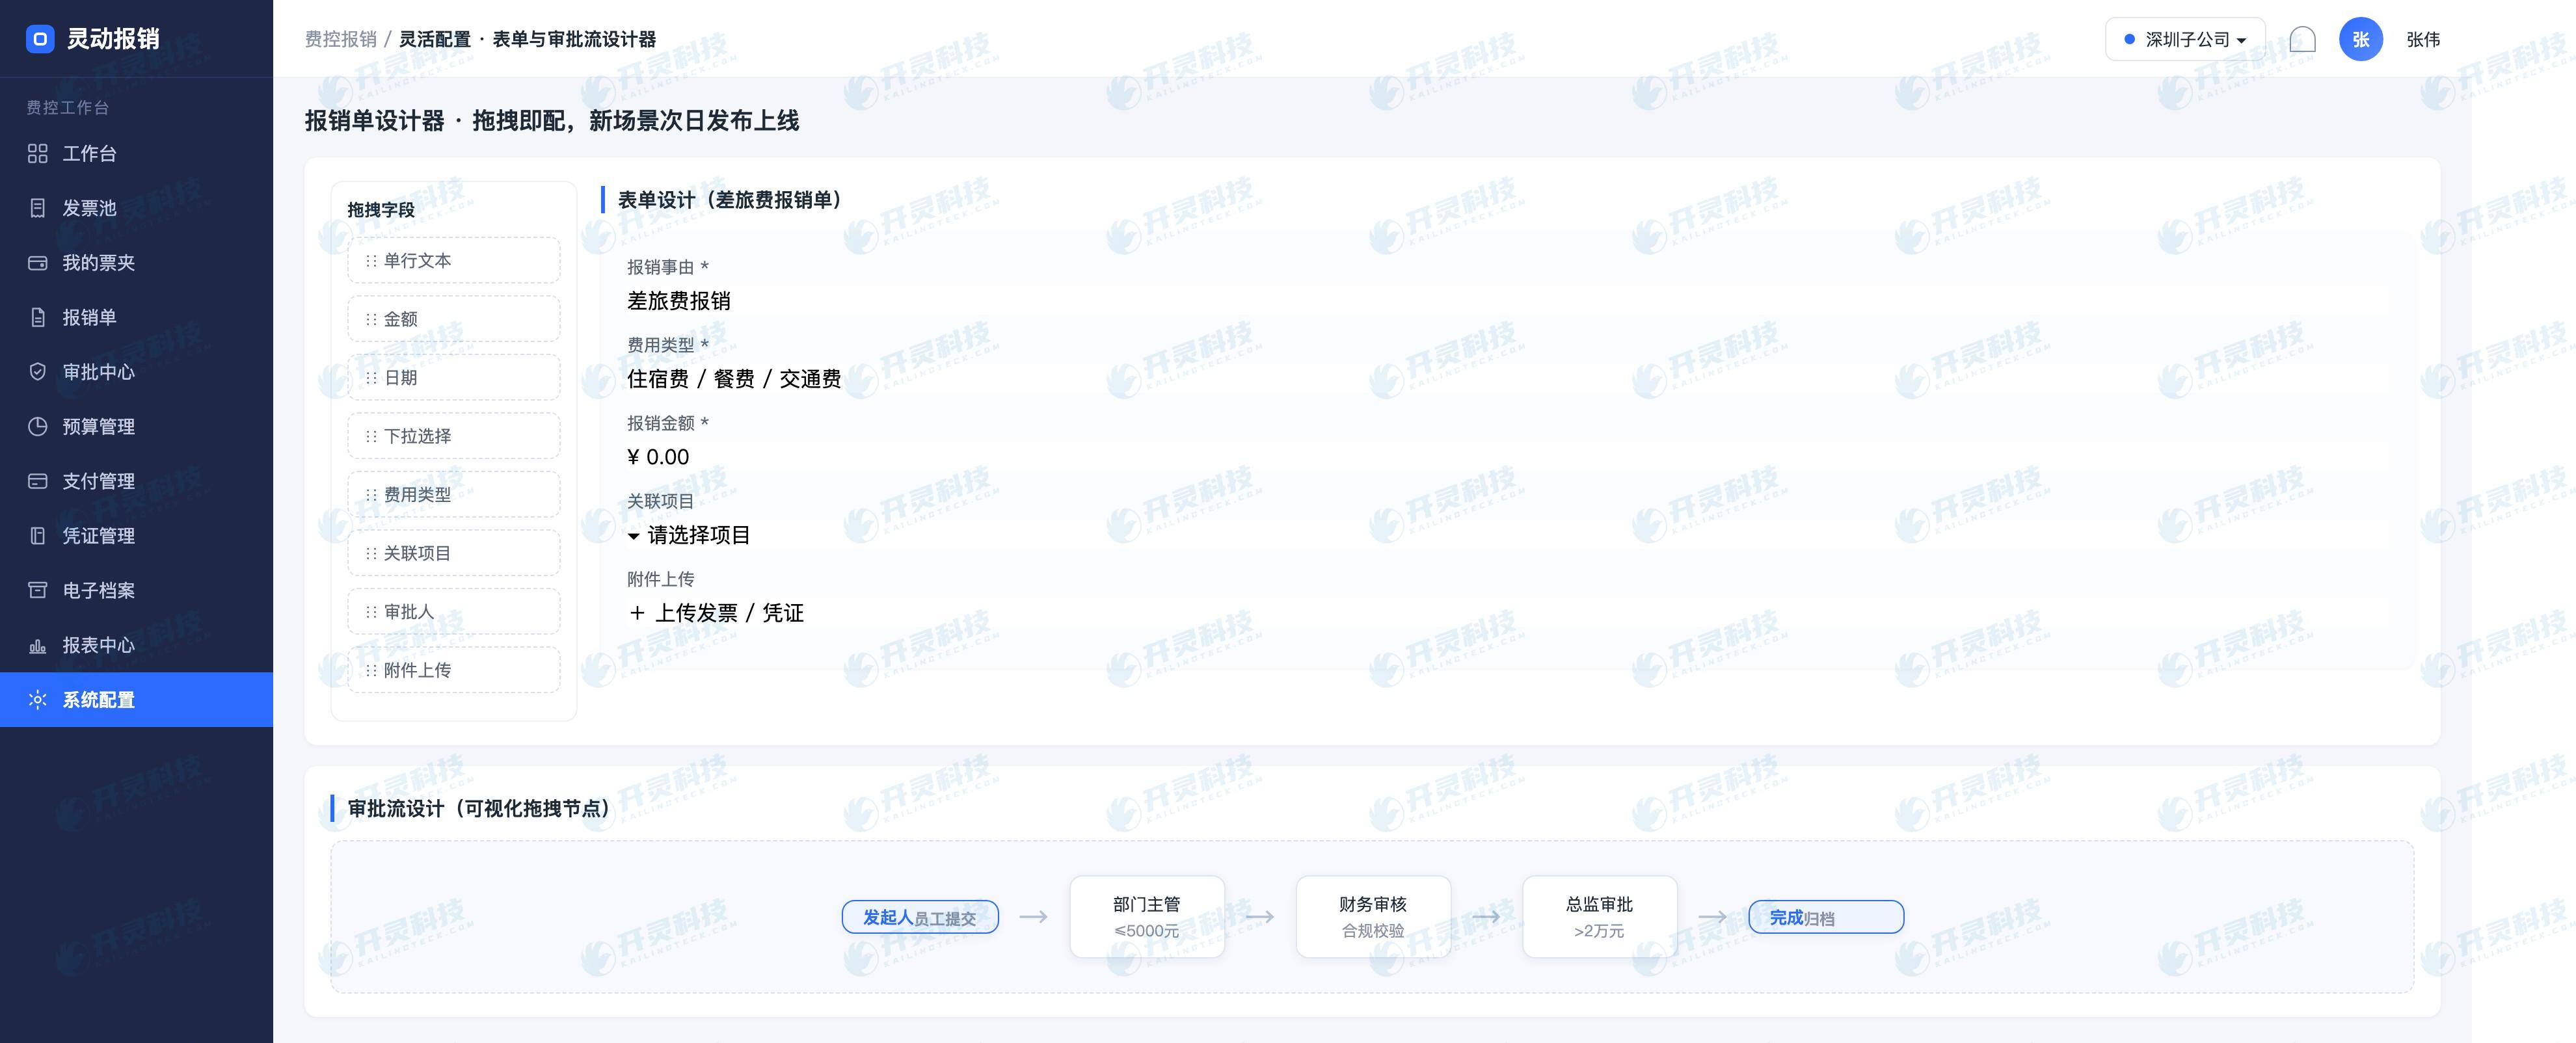
Budget control needs to know at least who is applying, which organization bears it, which department or project it belongs to, which category the expense falls into, and in which period the application occurs. If the application form lacks these fields, the system can only give rough prompts even if it is connected to the budget table.
Before use, confirm the budget version, period, currency, organizational level, and adjustment rules. After a budget change, whether submitted applications continue to use the original quota and whether pending approval forms are recalculated should all have clearly defined handling rules.
▍II. Calculate the available quota before submitting the application
After the applicant selects the organization, expense type, and project, the system verifies based on the issued budget, occupied amount, and available balance. The amount can come from receipts or application entries; the key is to make the calculation basis visible, avoiding the applicant seeing only an unexplainable "not approved."
The timing of budget occupation must also be designed clearly. Submission, approval, payment, or booking may all become management nodes. Enterprises should determine this according to actual policies and handle withdrawal, rejection, write-off, and budget release. It cannot be only a one-time static comparison.
▍III. Kailing Technology AI expense control management system breaks overspending into executable actions
Minor deviations can prompt the applicant to confirm; overspending with genuine business necessity can require supplementary explanation and escalated approval; budget dimension errors should guide re-selection of dimensions; explicitly prohibited expenditures are blocked before submission. Different actions carry different chains of responsibility.
The system records the version, dimensions, calculation results, and processing actions used for budget verification. After the applicant adds explanations, the approver sees not only "over budget" but also the budget balance, occupied items, and exception basis, facilitating traceable judgment.
▍IV. Pre-control must connect with in-process and post-event data
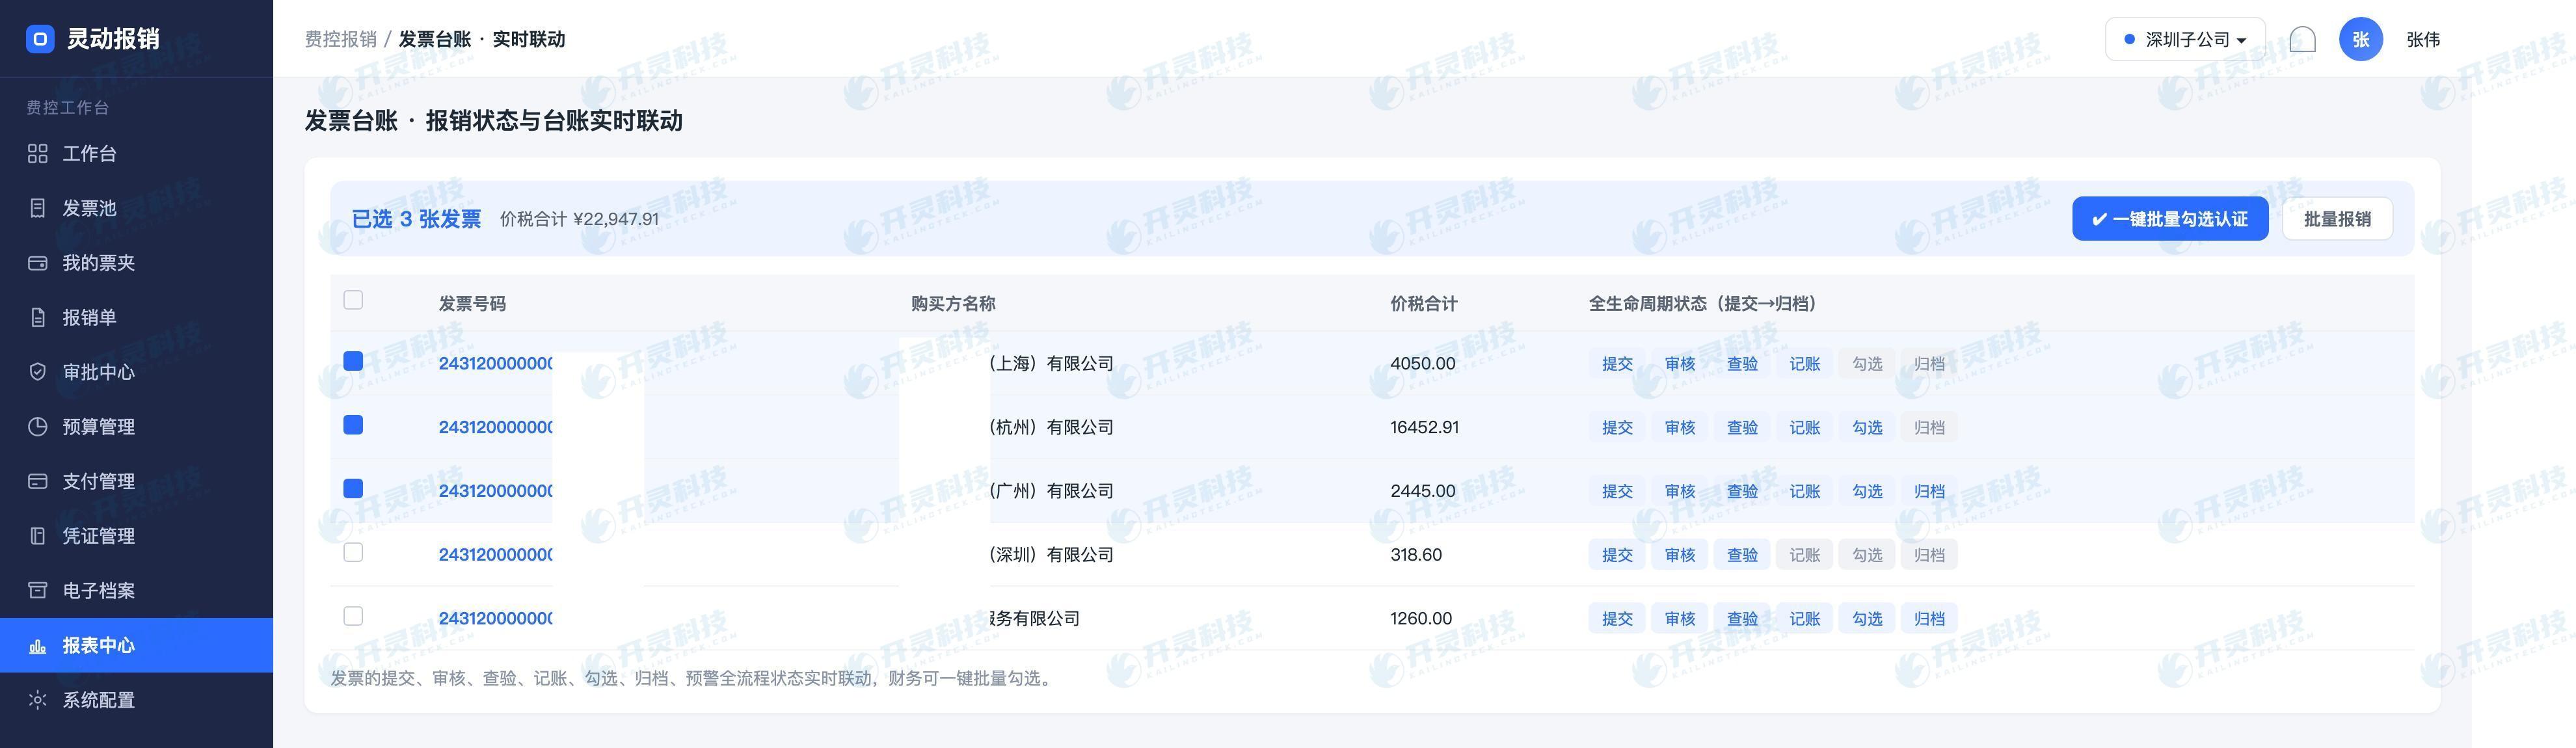
If budget control stays only on the application page, breaks in definition may still occur at payment, reimbursement, or posting. Application forms, invoices, payments, and vouchers should remain linked, and budget occupation should update in sync with status changes, so that commitments, actual occurrences, and remaining quota can be seen.
For withdrawals, rejections, red reversals, and corrections, it must be clear how quotas are released or reoccupied. The system should not directly overwrite historical results just to make balances look good, but should retain state changes and responsible persons, supporting finance in explaining budget variances for a given period.
▍V. Verify budget pre-control with multi-entity and exception scenarios
Verification samples should cover different organizations, departments, projects, expense types, and periods, including sufficient budget, insufficient balance, budget not yet issued, cross-organization applications, withdrawal and resubmission, and policy exceptions. Check whether each situation receives the expected prompt or approval action.
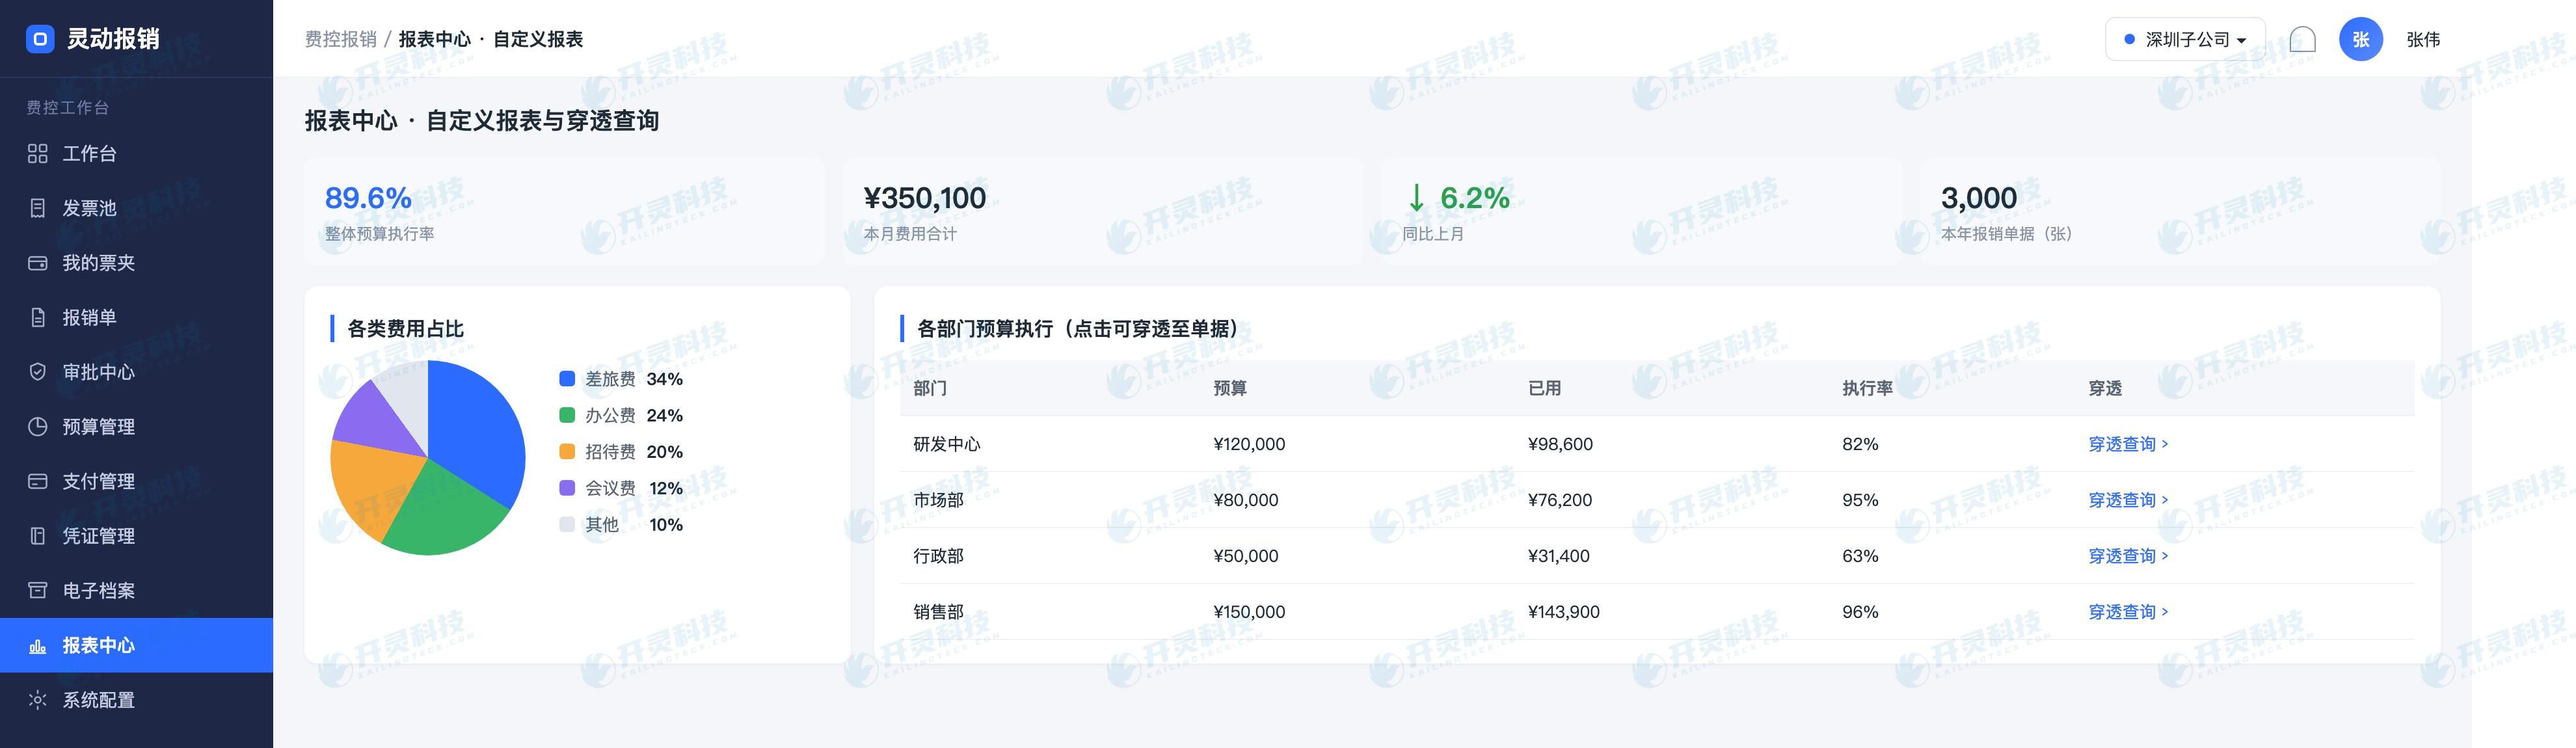
After use, you can drill down by department and project to view budget execution and analyze applications that were intercepted, transferred to manual handling, and finally approved. If a certain rule long produces large numbers of false positives, you should revisit the budget definitions and application fields rather than simply turning off the control.
- Budget dimensions can correspond to application fields.
- The basis for calculating the available limit can be viewed.
- Overspending triggers prompting, supplementation, escalation, or blocking actions.
- Withdrawal, rejection, and payment status affect budget occupation.
▍VI. Budget control must look at both commitments and actual occurrences
Budget balance is not a static number. Application, approval, payment, reimbursement, withdrawal, and write-off all change expense status. Enterprises should first clarify which nodes represent commitments and which nodes represent actual occurrence, and then let budgets, documents, and payments share the same basis.
Multi-organization management must also distinguish between headquarters summaries and grassroots details. Managers need to drill down to departments, projects, and expense types, while grassroots users only view the authorized scope; budget adjustments retain the before-and-after relationship so it can be explained why the balance changed in a certain period.
- Occupancy and release points have an institutional basis.
- Status changes will synchronously affect budget results.
- Data across multiple organizations is isolated by permission.
- The summary view can drill through to business documents.
▍7. Budget control must let business users understand balance changes
Budget balance is meaningful only when placed together with business matters. Applicants care about whether this expense can be used, department heads care about how much remains for the project, and finance cares about committed, incurred, and pending release amounts. The system links these statuses so managers do not see only an isolated number.
When the budget basis changes, it must be possible to distinguish the versions before and after adjustment and the scope of impact. Withdrawal, rejection, payment, and write-off should also not directly overwrite history, but should form explainable change records, so budget data can be used both for control and for review.
Under multiple organizations, a unified view and permission isolation must coexist: headquarters sees summaries and drill-downs, while grassroots units only see authorized organizations and projects, avoiding cross-organization data interference.
Budget data can also be used for expense analysis. By viewing applications, occupation, actual occurrences, and remaining amounts by organization, department, project, and expense type, managers can know where deviations occur, rather than waiting until month-end to see an undecipherable total. Budget control therefore serves both as advance reminder and post-hoc explanation.
Once budget control is moved forward, applicants can know the quota and approval requirements before expenses occur, managers can see the reasons for overspending, and finance can link budget execution with actual vouchers. Control is no longer just month-end statistics, but continuous information running through application, approval, payment, and archiving.
After budgets and expense control are connected, expense standards, approval permissions, and budget balances can appear simultaneously on the application page. Applicants do not have to wait for approval rejection to know that the basis does not match, and responsible persons can also judge whether explanation is needed based on business matters, making budget control closer to actual decision-making.
The clearer the budget basis, the less expense control depends on the approver's memory. When organization, project, expense type, and period remain consistent, differences among applications, payments, and vouchers are easier to discover and explain.
Budget control must ultimately return to real business, not merely pursue the pass rate in the system.
Only after application, approval, payment, and posting use a unified dimension do budget figures become comparable, and managers can clearly see whether expense changes come from business growth or from a change in definition.
- The balance displays the calculation basis and status.
- Commitment, actual, and release are distinguished from one another.
- Budget adjustments retain before-and-after versions.
- Summaries and details follow permission boundaries.
▍FAQ
Q: Must budget control directly block overspending?
A: Not necessarily. Enterprises can set different actions such as prompting, supplementary explanation, escalated approval or blocking according to policy.
Q: What happens to already submitted documents after a budget adjustment?
A: Whether to recalculate should be defined in advance, and the budget version and the relationship between before-and-after results should be retained.
Q: If the applied amount differs from the actual reimbursement amount, will it affect the budget?
A: Status should be updated according to the occupation and release nodes determined by the enterprise, keeping application, reimbursement, and payment linked.
Q: Can multiple organizations share one set of budget rules?
A: Yes, a unified framework is possible, but each organization's basis, limits, and approval authority should be isolated according to actual configuration.
Move budget control forward from post-expense accountability to application decisions. Welcome to visit Kailing Technology: https://www.kailingteck.com/feikong/ .
As a national high-tech enterprise, Kailing Technology focuses on the digital and intelligent transformation of enterprise business-finance-tax and operations management, providing software products, system integration, implementation and delivery, and operational services for various government agencies, institutions, group enterprises, and SMEs.
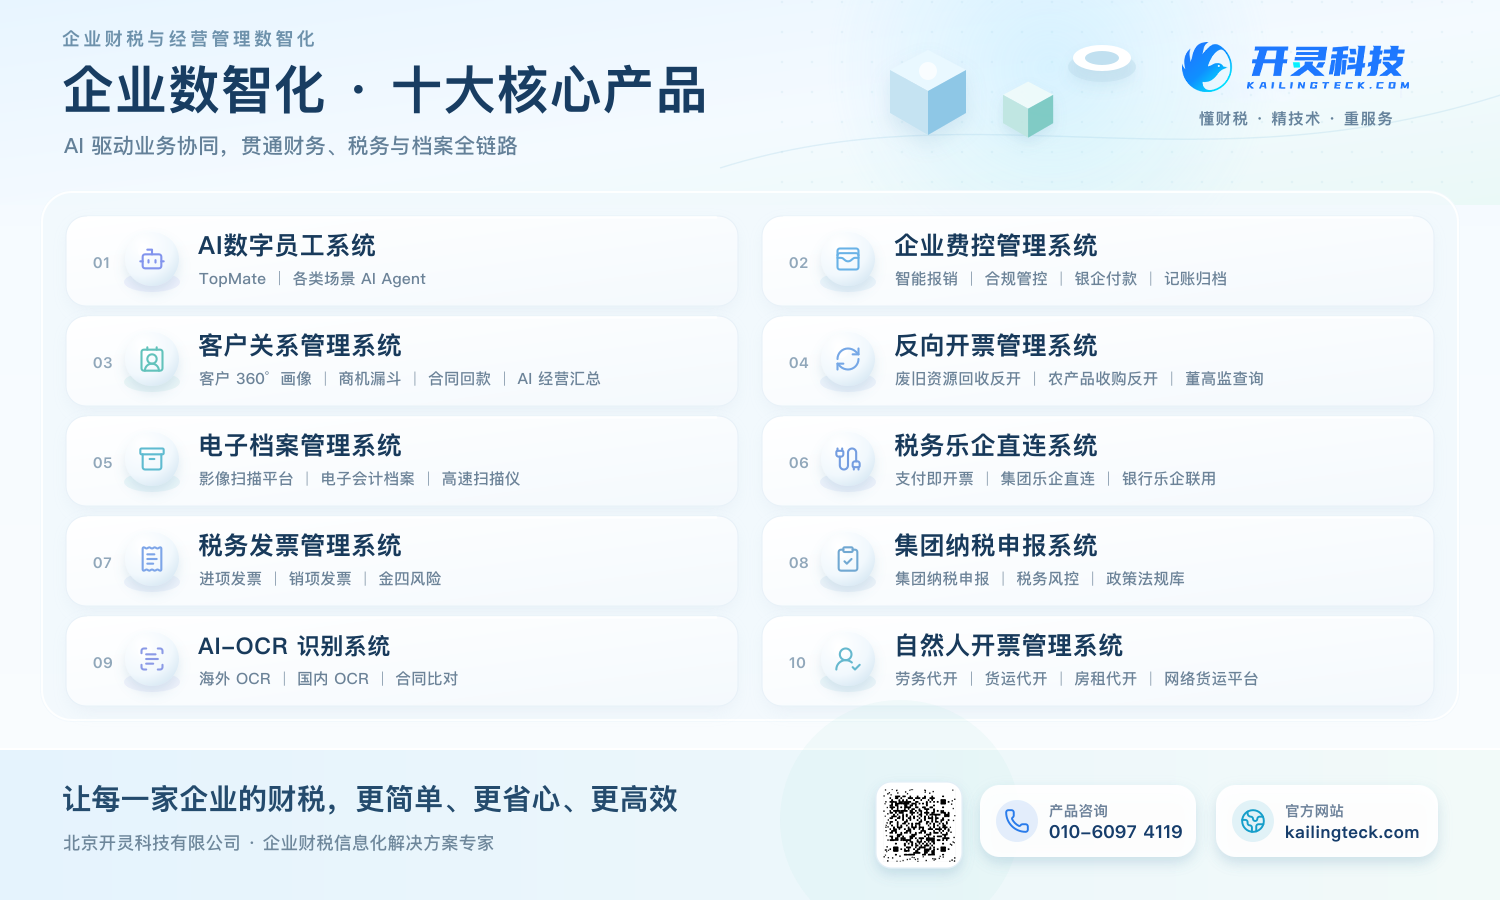
The company has now formed ten core product lines, including: AI digital employee system, enterprise expense control management system, customer relationship management system, reverse invoicing management system, invoice issuance for individuals management system, electronic archives management system, tax fully digitalized e-invoice Leqi system, tax invoice management system, group tax filing system, and AI OCR recognition system. It is committed to connecting enterprise business, finance, tax, funds, and archive data to help customers improve operational efficiency, business-finance-tax compliance capabilities, and digital management levels.
If you have any business-finance-tax digital transformation needs, welcome to contact us. Beijing Kailing Technology will serve you wholeheartedly.
Keywords: Pre-budget control, AI expense control management system, expense budget management, Lingdong Reimbursement
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing