
What can IPA digital employees do for finance? How to handle the four task types: documents, contracts, collections, and reports
What can IPA digital employees do for finance? How to handle the four task types: documents, contracts, collections, and reports
IPA digital employees are suited, under clear authorization and rules, to assist with cross-system data retrieval, field comparison, exception flagging, and draft generation. They can share the repetitive operations of finance, but "fully taking over documents, contracts, collections, and reports" exceeds the capabilities most projects can directly verify. The actual scope depends on system interfaces, data quality, permissions, and manual review arrangements.
1. First define the automation boundaries
For each task, list the input sources, readable fields, judgment rules, output results, approvers, and failure fallback methods. Compared with process automation based on fixed rules, digital employees that include models can help understand unstructured text and summarize exceptions, but results may be wrong; chat Q&A, process execution, and financial decisions must not be conflated. Set permissions and manual confirmation for actions such as payment, booking, external collection, and filing.
2. Document verification: extract first, then verify
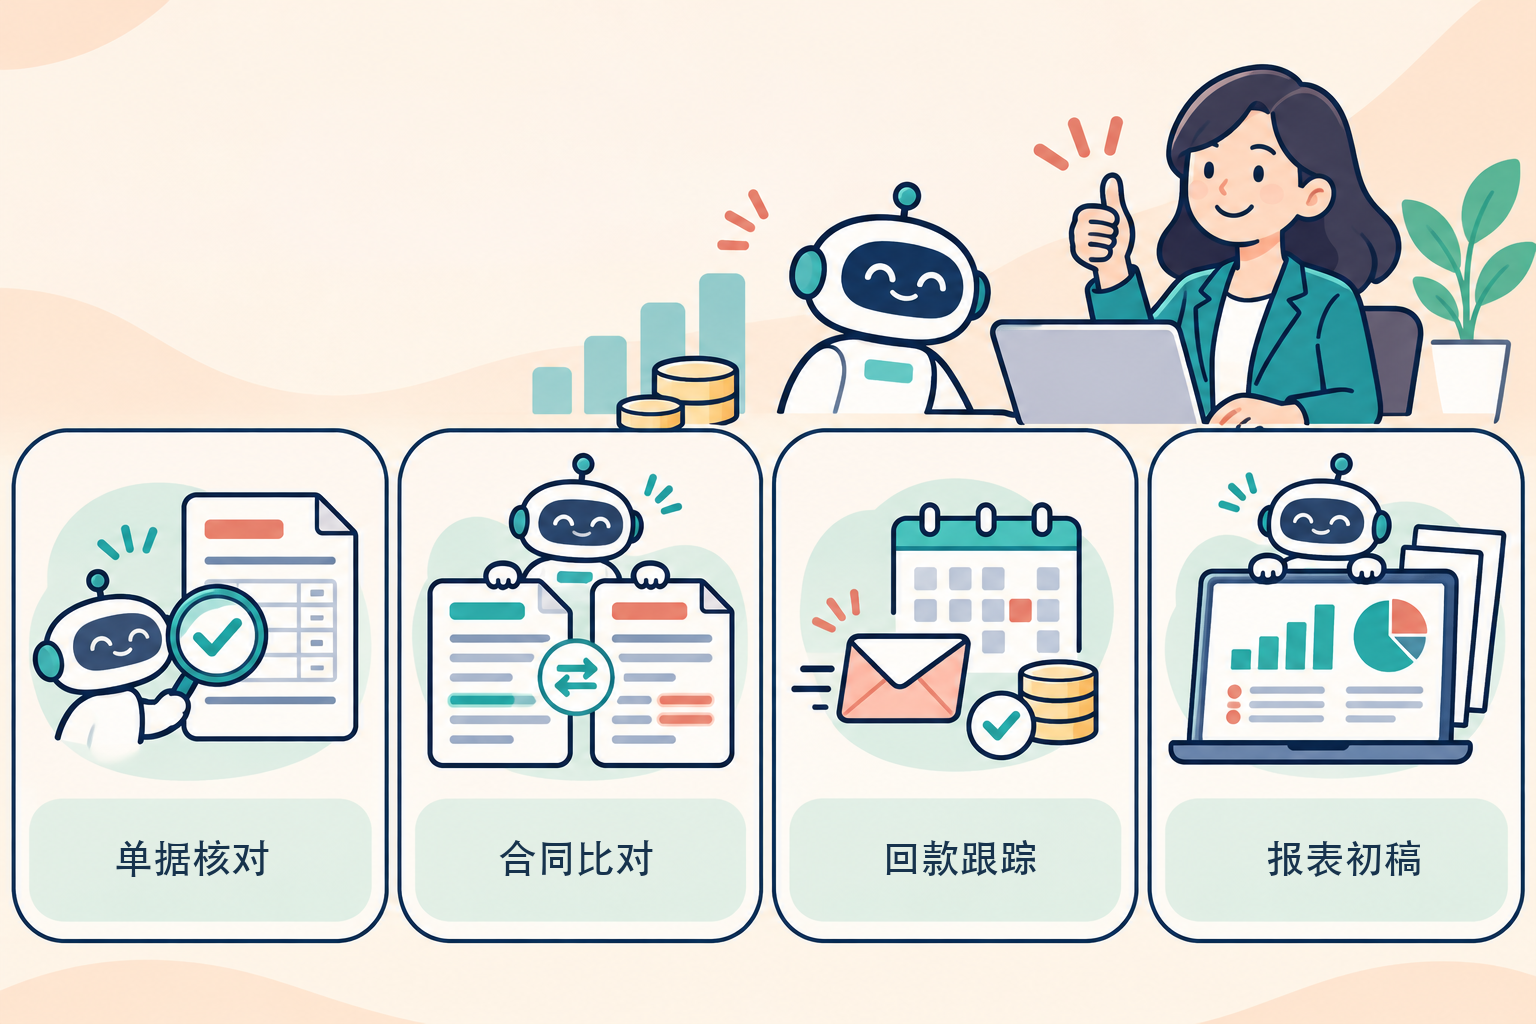
OCR or interfaces can be used to extract fields from invoices, reimbursement forms, and receiving notes, then compare them with applications, contracts, and business ledgers to flag records that are duplicates, have mismatched amounts, inconsistent headers, or missing attachments. Field recognition is not the same as original voucher review, and even less the same as automatic booking. Accounting institutions and accounting personnel should still review vouchers according to regulations, and abnormal documents should be corrected, returned, or approved by authorized persons. Invoice data sources and verification capabilities should be verified according to actual authorization and interfaces; do not claim to obtain all invoices.
3. Contracts and collections: output a discrepancy list
Extract payment terms, amounts, due dates, and actual collections from contract clauses, orders, acceptance, invoicing, and accounts receivable ledgers to generate a to-be-verified list. Note contract changes, installment payments, offsets, disputed amounts, and customer communication records; a system mismatch does not necessarily mean default. External collection messages can first be generated as drafts, then executed after business or finance leaders verify the recipient, amount, tone, and timing.
4. Reports: generate drafts after unifying definitions
First clarify the definitions, organizational scope, cutoff points, and data sources of metrics such as revenue, orders, invoicing, and collections, then have the tool summarize and flag missing and abnormal items. Generated business analyses and charts must be cross-checked against original ledgers, the general ledger, and approved reports; in particular, invoiced amount, recognized revenue, and cash collections must not be treated as the same number. Versions, modifiers, and approval records should be traceable.
5. Use a small sample to verify actual capabilities
Select samples of normal, duplicate, missing-field, cross-period, and interface-failure cases, and observe whether the system provides sources, processing logs, exception alerts, and manual takeover entry points. Kailing Technology's AI digital employees and related finance products can be included in the pilot, but cross-system connectivity, approval submission, verification, and reporting capabilities should be subject to the specific version, authorization, region, and project acceptance. Finance personnel retain business judgment, accounting review, and external responsibility.
A feasible goal is to have digital employees first complete traceable preparatory work so people can handle exceptions faster; whether the automation scope can be expanded should be decided by pilot results.
Verification Basis
Ministry of Finance's Norms for Basic Accounting Work;Ministry of Finance "Measures for the Management of Accounting Archives";Regulations on the Administration of Network Data Security。
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing