
Can a purchasing invoice be issued for purchasing seafood from fishermen? The Kailing Technology agricultural product purchasing reverse invoicing system distinguishes self-production from trafficking and ensures tax compliance of purchasing invoices through evidence retention under the integration of five flows.
Aquatic product processing plants and seafood freezing enterprises often ask: "Can purchase invoices be issued for seafood bought from fishermen?" The answer is yes, but the premise is that the fishermen are selling aquatic products they farmed or caught themselves and can provide self-production proof such as a water area and mudflat aquaculture certificate or a fishing license; if the counterparty is a trader who buys from other fishermen and resells, it cannot be treated as a purchase from fishermen. The Kailing Technology agricultural product purchase reverse invoicing system distinguishes self-production from resale when creating farmer profiles, linking pond-side weighing, scan confirmation, payment and invoicing, and cold-chain factory re-verification into one evidence chain. This article explains the invoicing conditions, process, and evidence retention points for aquatic product purchase invoices. Only when self-production proof, weighing records, payment, and invoices are retained under the five-flow integration can the tax compliance of purchase invoices hold up.
▍Whether it can be issued: the key is "self-farmed and self-caught" versus "resale"
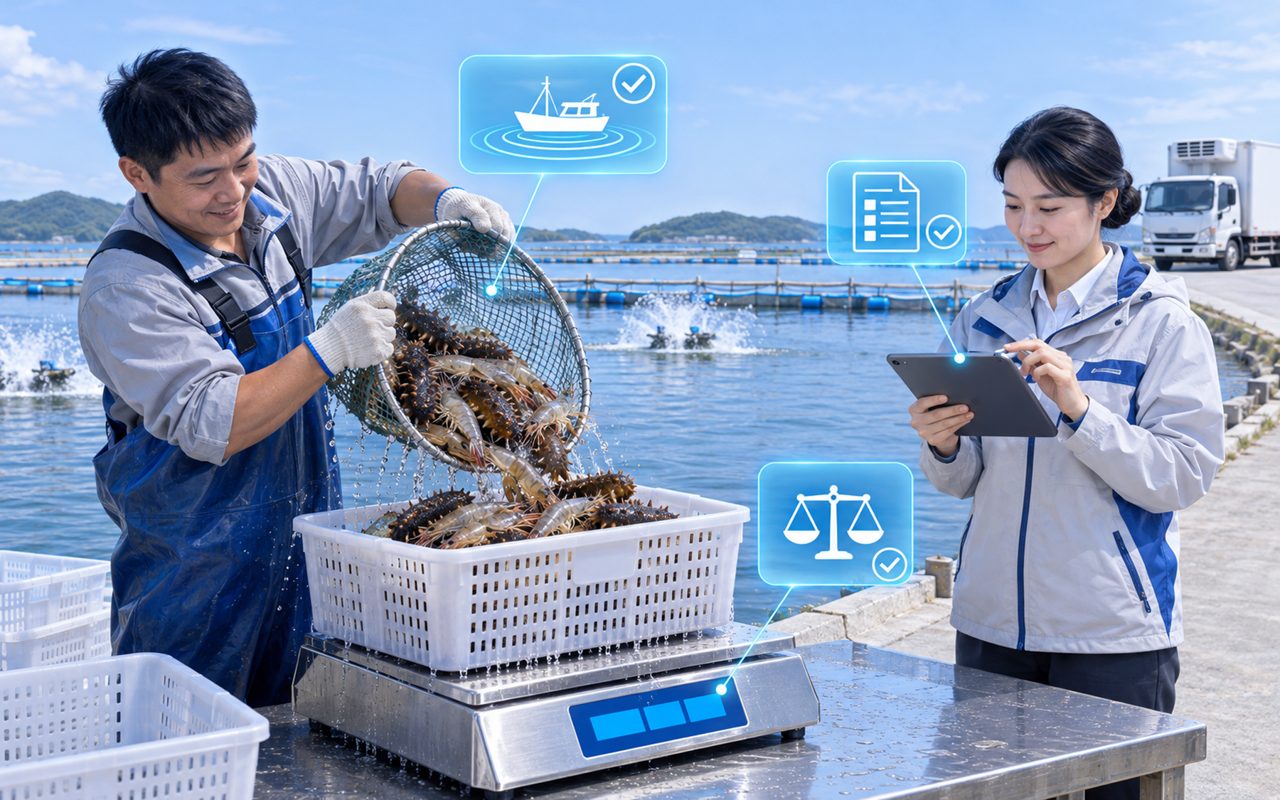
Whether a purchasing invoice can be issued for purchasing seafood from fishermen is judged by whether the seller is a fishery producer and whether the products sold are self-produced aquatic products. Sea cucumbers, prawns, and crayfish that one has farmed oneself, and fish, shrimp, crabs, and shellfish that one has caught oneself, are self-produced; products purchased from other fishermen and resold are trafficking.
Self-production needs proof. There are three common types of self-proof materials: water area and mudflat aquaculture certificates, applicable to pond, mudflat, and cage aquaculture; fishing licenses, applicable to marine or inland water fishing; and for cases such as rice-field shrimp farming, land contracting contracts or village committee certificates can be provided. Purchasing enterprises should handle sellers without any self-proof materials with caution.
| "The same basket of sea cucumbers: self-farmed ones can be covered by purchase invoices, but resold ones cannot." |
▍Three difficulties in aquatic product purchasing
Compared with grain, fruits, and vegetables, aquatic product purchasing has three obvious difficulties.
First, fresh products are hard to measure. Sea cucumbers and crayfish need to be drained before weighing, and water content directly affects weight; if on-site measurement records are incomplete, re-verification afterward is very difficult. Second, grade price differences are large. Prawns from the same pond are priced differently after grading by specification, and swimming crabs and sea cucumbers are also commonly priced by specification; if a purchase order only states total weight and total amount, the invoice details are hard to explain. Third, cold-chain transport has many stages. Goods are loaded onto cold-chain trucks from pond edges or docks, possibly combining multiple households in one truck, and must be re-verified after arrival at the plant; once the quantity at the plant does not match the purchased quantity, records are needed to explain the reason.
The table below lists the differences in self-proof materials and measurement methods for different aquatic product categories.
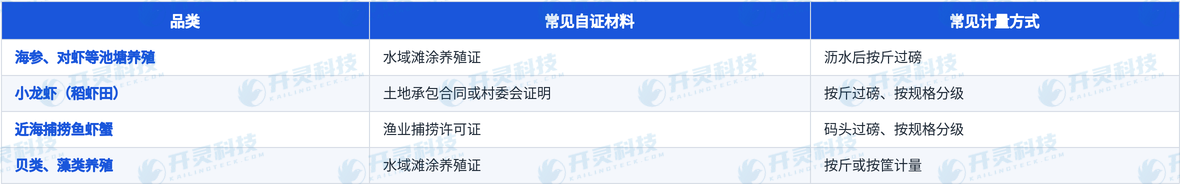
Self-proof materials and measurement methods for aquatic product purchasing
The conclusion of the table is: self-proof materials differ for different aquatic products, and purchasing enterprises need to require farmers to upload the corresponding materials by category when creating profiles, rather than uniformly requiring only an ID card.
▍The aquatic product purchase process of Kailing Technology's agricultural product purchase reverse invoicing system
The Kailing Technology agricultural product purchasing reverse invoicing system divides aquatic product purchasing into five stages: profile creation, weighing, order confirmation, payment and invoicing, and factory re-verification.
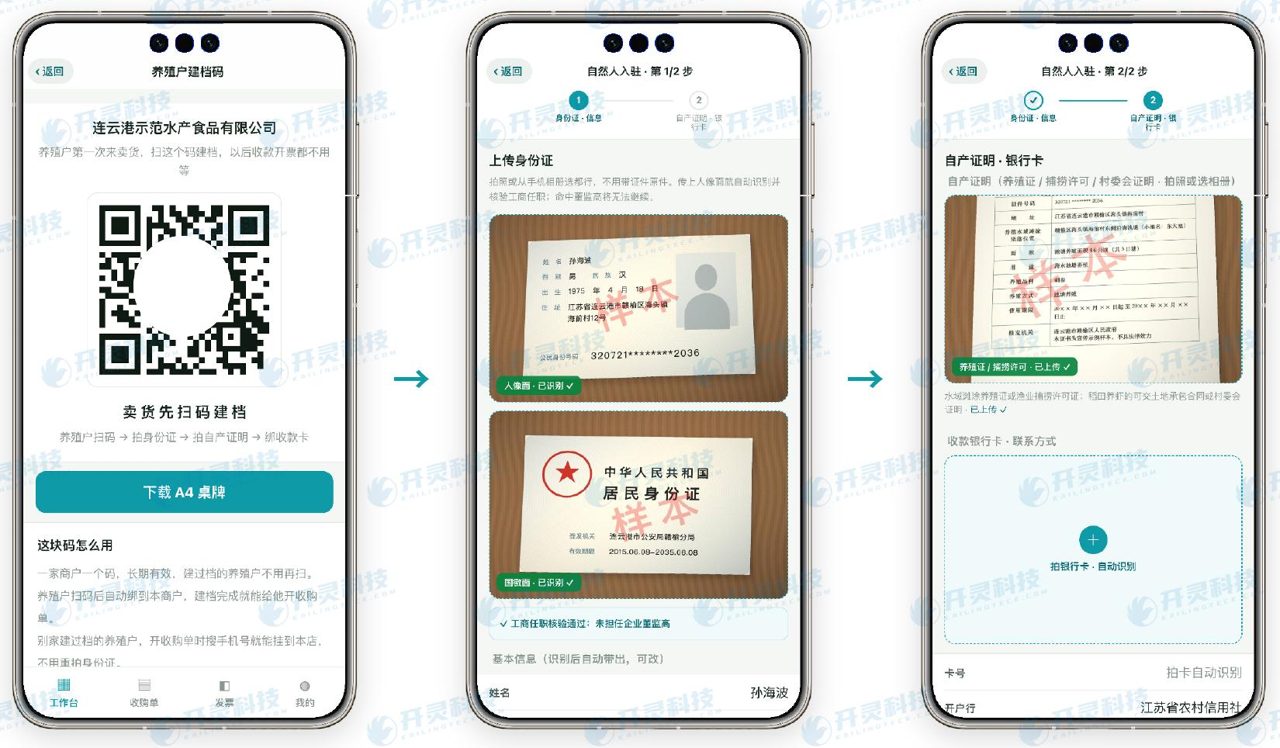
Kailing Technology fisherman profile creation: upload aquaculture license or fishing permit (information desensitized)
- Aquaculture certificate self-proof: When farmers come to sell for the first time, they scan the code to file and upload an aquaculture certificate or fishing license; for rice-shrimp fields, a land contract or village committee certificate can be submitted; the system performs real-name verification, quota verification, and blacklist comparison.
- Pond-side weighing: Sea cucumbers are drained at the pond side and then weighed, while crayfish are de-mudded and drained at the field edge and counted by net weight; the purchaser attaches a photo of the scale to the product line of the purchase order, and the weight supports decimals.
- No coding errors: Sea cucumbers, crayfish, prawns, swimming crabs, etc. each have their own tax classification codes, pre-configured in the product library so purchasers only select rather than fill in.
- Payment-triggered invoicing: After the farmer scans the code to confirm, the enterprise account pays the payment directly to the farmer's own bank card, and a reverse invoice is issued at the same time as the successful payment: one payment per order, one invoice per order.
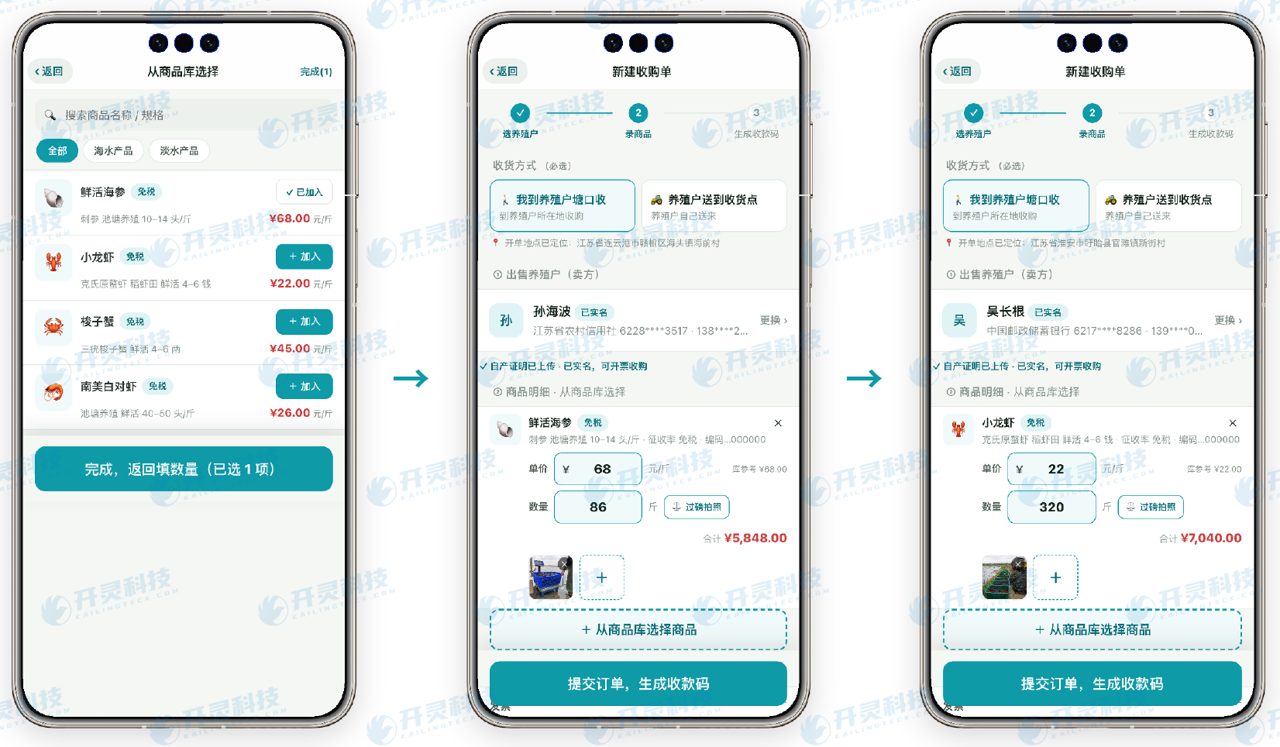
Kailing Technology pond-side weighing: drained net weight and scale photo (information desensitized)
▍Cold-chain arrival at the factory: how to re-inspect multiple households loaded in one truck
Aquatic products are often loaded together from two or three households onto one cold-chain truck and transported to the processing plant. The Kailing Technology agricultural product purchase reverse invoicing system allows multiple purchase orders to be linked to the same trip, recording the license plate and transport trajectory; after arrival at the plant, weights are re-verified one by one against the purchase orders.
Fresh aquatic products may have normal loss during transport; if there is a quantity difference during re-verification, the system only records the reason for the difference and does not go back to modify the purchase order already confirmed by the farmer. This preserves the true data at purchase, explains the change in quantity at the plant, and keeps the five-flow evidence consistent.
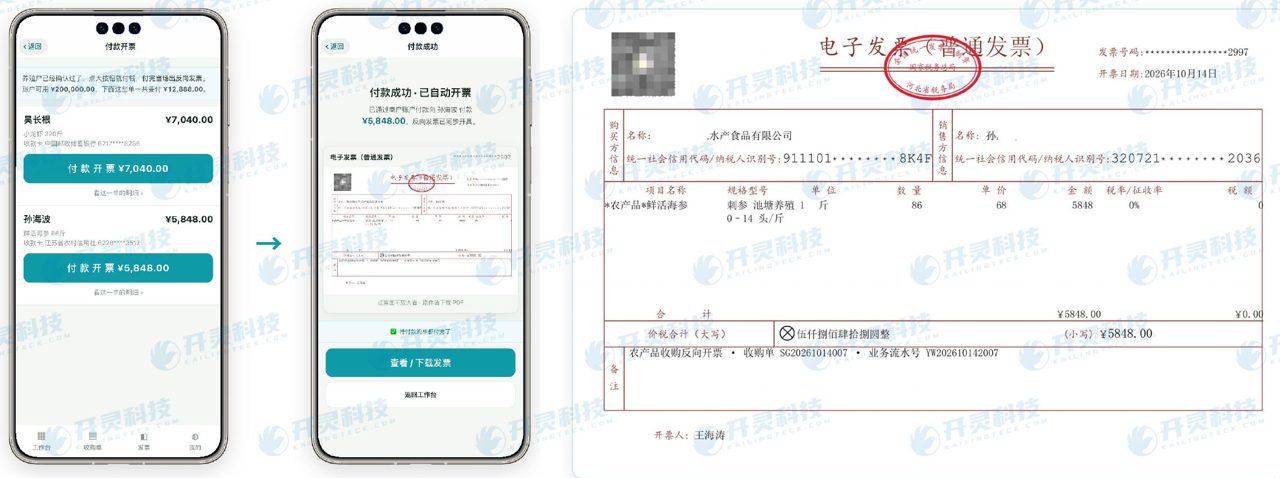
Aquatic products invoiced upon payment (test invoice, subject to the Leqi invoice format)
▍Deduction basis and frequently asked questions
After a purchasing enterprise purchases self-produced aquatic products from farmers and issues a purchasing invoice, according to the Ministry of Finance and State Taxation Administration Announcement No. 10 of 2026, input VAT is calculated and deducted at 9% of the purchase price stated on the invoice; farmers' sales of self-produced aquatic products are exempt from tax when invoiced.
Note that when aquatic products are priced by specification grade, the purchase order should be entered line by line by specification, with each line having its own weight and unit price, and the invoice details should correspond line by line to the purchase order. Do not merge different specifications into one line and invoice at an average price, otherwise the grading records and invoice details cannot correspond.
There are two most common problems in aquatic product purchasing: first, treating fish traders at the dock as fishermen and issuing purchase invoices to them; second, retaining only invoices without retaining aquaculture or fishing certificates. The former invalidates the premise of the purchase invoice, and the latter leaves the enterprise unable to prove itself during verification. The Kailing Technology agricultural product purchase reverse invoicing system mandates uploading self-proof materials when creating profiles and mandates personal confirmation at purchase, precisely to avoid these two problems at the source.
▍Applicable users and deployment methods
This process is suitable for aquatic product processing plants, seafood freezing enterprises, aquatic product wholesale and purchasing enterprises, and other units that directly receive goods from farmers and fishing households, especially where purchasing points are scattered across multiple ponds and docks. If the upstream party is a registered aquatic cooperative or aquaculture company, it should issue invoices itself.
During deployment, enterprises usually first sort out their purchase categories and specifications, configure the product library and tax classification codes, and then post filing codes at each purchase point. Farmers need a few minutes for their first filing, and thereafter only need to scan the code to confirm each sale. The system can be deployed privately in the enterprise's own data center or used as a SaaS service; invoicing goes through the fully digitalized e-invoice or Leqi channel, payment goes through direct bank connection, and cold-chain vehicle information can be registered together with each trip.
For enterprises whose purchasing points are far apart, purchasers complete order creation and photo taking on mobile phones at the pond or dock, and data is transmitted back to headquarters in real time, so finance does not need to wait for paper documents to be mailed back before paying.
For enterprises that concentrate purchases during peak season, it is recommended to complete go-live and farmer profile creation one to two months before the peak season arrives; during peak season, purchasers only need to create orders and take photos, and finance pays and invoices in batches, avoiding a backlog of documents.
▍FAQ
Q: Can purchase invoices be issued for purchasing seafood from fishermen?
A: Yes, but the fishermen must be selling aquatic products they have farmed or caught themselves and must be able to provide proof of self-production such as a water area and mudflat aquaculture certificate or a fishing license; resellers who buy from others and resell cannot be treated as purchases from fishermen.
Q: How much input VAT can be deducted on aquatic product purchase invoices?
A: According to Ministry of Finance and State Taxation Administration Announcement No. 10 of 2026, input VAT is calculated and deducted at 9% of the purchase price stated on the purchase invoice.
Q: What if the crayfish farmed in rice paddies have no aquaculture certificate?
A: A land contract or a certificate issued by the village committee can be provided as proof of self-production. Kailing Technology's agricultural product purchase reverse invoicing system supports uploading these two types of materials during filing.
Q: If the weight is less after cold-chain delivery to the factory, does the invoice need to be changed?
A: Do not change the confirmed purchase order and invoice; just record the discrepancy and reason during factory re-inspection, ensuring the purchase data is consistent with what the farmer confirmed.
To distinguish self-production from resale in aquatic product purchasing and issue every purchase invoice properly, you are welcome to learn about the Kailing Technology agricultural product purchase reverse invoicing system: https://www.kailingteck.com/fxncp/ .
As a national high-tech enterprise, Kailing Technology focuses on the digital and intelligent transformation of enterprise business-finance-tax and operations management, providing software products, system integration, implementation and delivery, and operational services for various government agencies, institutions, group enterprises, and SMEs.
The company has now formed ten core product lines, including: AI digital employee system, enterprise expense control management system, customer relationship management system, reverse invoicing management system, invoice issuance for individuals management system, electronic archives management system, tax fully digitalized e-invoice Leqi system, tax invoice management system, group tax filing system, and AI OCR recognition system. It is committed to connecting enterprise business, finance, tax, funds, and archive data to help customers improve operational efficiency, business-finance-tax compliance capabilities, and digital management levels.
If you have any business-finance-tax digital transformation needs, welcome to contact us. Beijing Kailing Technology will serve you wholeheartedly.
Keywords: aquatic product purchase invoice, purchasing seafood from fishermen, fishery purchase invoice, seafood purchase invoice, Kailing Technology agricultural product purchase reverse invoicing system, aquaculture certificate self-proof
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing