
What is the tax rate for invoice issuance for individuals? Breakdown of three taxes to avoid pitfalls in 2026
What is the tax rate for invoice issuance for individuals? Breakdown of three taxes to avoid pitfalls in 2026
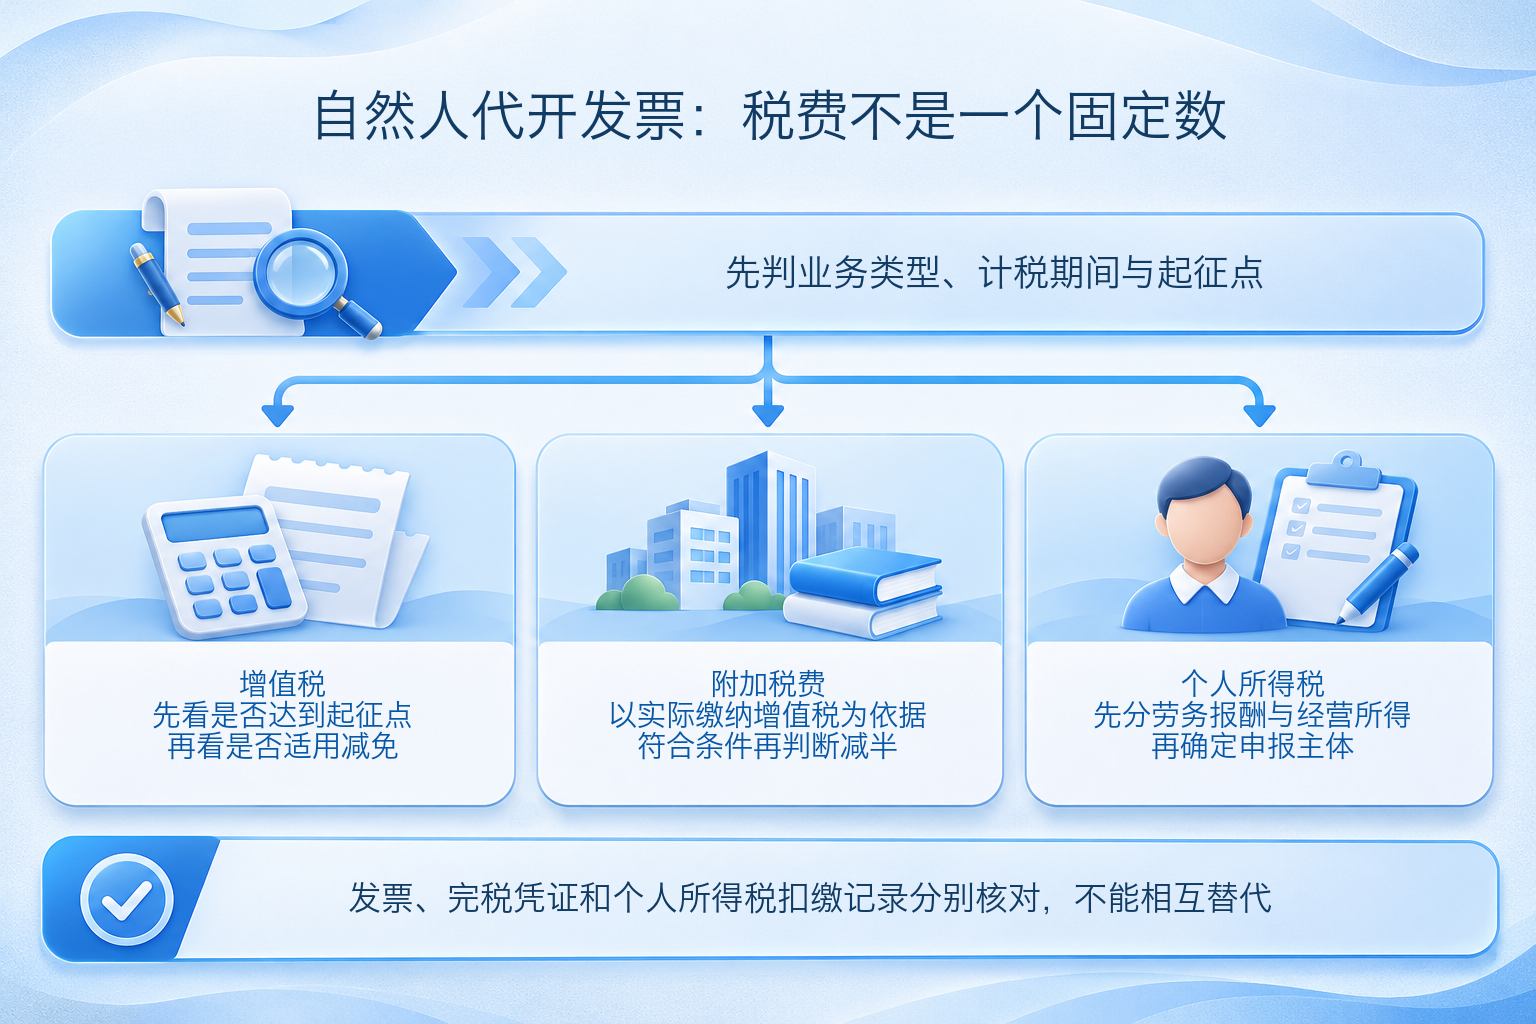
There is no fixed tax rate for invoice issuance for individuals that applies to all businesses. The correct order is to first determine the transaction type, the tax period, and whether the threshold is reached, then separately verify VAT, surcharges such as urban maintenance and construction tax and education surcharges, and individual income tax. Businesses such as labor services, leasing, and real estate transfers cannot be treated under the same standard.
When finance asks "how many percentage points are payable for invoice issuance," they often conflate the invoice face amount, VAT preferences, and individual income tax. Invoice issuance is merely a handling method for issuing a voucher and does not automatically change the substance of the business or the nature of the income. Before payment, enterprises should verify contracts, performance, invoicing, tax payment, payment, and withholding records within the same evidence chain.
▍1. For VAT, first check the threshold, then the levy rate and reductions/exemptions
Starting in 2026, individuals generally pay tax on a per-transaction basis, with a per-transaction threshold of 1,000 yuan of sales per transaction (day); multiple transactions within one day are assessed on a daily basis. For prescribed cases such as individuals leasing real estate, platform practitioners having filing handled by the platform, and reverse invoicing of scrapped products, the threshold is instead judged on a monthly sales standard of 100,000 yuan, and the per-transaction rule for general labor services cannot be applied directly.
For taxable sales income originally subject to a 3% levy rate that meets policy conditions, VAT is levied at a reduced rate of 1% before December 31, 2027, and invoices are issued at the 1% levy rate. This policy only covers income originally subject to the 3% levy rate that meets the conditions, and does not mean that all invoice issuance business for individuals is at 1%. For example, housing leasing, real estate transfers, and other special businesses have separate provisions and should be confirmed according to the specific transaction and the standards of the place of handling.
Where an individual reaches the threshold and applies to the competent tax authority for invoice issuance, the competent tax authority collects VAT at the time of issuance. From November 1, 2026, for transactions that comply with the provisions of the Administrative Measures for Domestic Entities Withholding and Remitting VAT for Individuals, domestic entities must also determine withholding obligations; where the individual has already paid VAT at the invoice issuance stage, no duplicate withholding is required.
▍2. Surcharges are based on the VAT actually paid
Urban maintenance and construction tax is based on the VAT and consumption tax actually paid in accordance with the law, and the education surcharge and local education surcharge use the same levy base. Therefore, when VAT is directly exempt, the corresponding surcharges usually have no levy base; when VAT is actually paid, they are calculated according to the applicable region and policy. Those meeting conditions such as VAT small-scale taxpayers may, before December 31, 2027, have urban maintenance and construction tax, education surcharge, and local education surcharge halved in accordance with regulations. The specific amount shall be subject to the invoice issuance page, tax payment vouchers, and the verification result of the competent tax authority.
▍3. Individual income tax cannot be replaced by the invoice levy rate
When resident individuals obtain labor remuneration, the entity or individual paying the income is the withholding agent and shall withhold and prepay as required at the time of payment. For each payment not exceeding 4,000 yuan, 800 yuan of expenses is deducted at withholding; for each payment above 4,000 yuan, 20% of expenses is deducted, then calculated according to the labor remuneration withholding rate table, and consolidated into comprehensive income for annual settlement at year-end, with refunds for overpayment and supplementary payment for underpayment. Individual income tax is not necessarily paid at the same time as invoice issuance, and the payer cannot skip the withholding determination just because it has obtained an invoice.
Business income, property leasing income, and others have their own tax calculation rules and cannot be determined solely by the invoice item name or the words "individual issuance." The determination should consider whether an employment relationship exists, whether the business is independent and continuous, who bears the tools and business risks, and the competent tax authority's confirmation of the specific facts.
▍4. What the system can do is keep records and verify; it cannot replace tax judgment
Kailing Technology's solutions related to invoice issuance for individuals can, within the project scope, assist in collecting identity, contract, performance, and invoicing materials, record submission, return, tax payment, download, and archiving status, and manage invoices, tax payment vouchers, and payment materials in a linked manner. The actual regions where handling is possible, business types, tax and fee calculations, and interface capabilities shall be subject to the rules of the competent tax authority, the customer's system version, and the acceptance results of real samples.
Conclusion: First confirm the business and the threshold, then check whether VAT reductions or exemptions apply; surcharges follow the VAT actually paid; individual income tax is handled separately according to the nature of the income. Do not use a single ratio on an invoice to replace a complete tax burden analysis.
Disclaimer: This article is general tax information and does not constitute tax advice for a specific transaction. Policy application and filing results are affected by business facts, regional standards, and timing of handling; please refer to the opinion of the competent tax authority.
Official basis:State Taxation Administration Announcement No. 4 of 2026;Ministry of Finance and State Taxation Administration Announcement No. 19 of 2023;Announcement No. 12 of 2023 by the Ministry of Finance and State Taxation Administration;Ministry of Finance and State Taxation Administration Announcement No. 28 of 2021;Q&A on individual income tax for invoice issuance for individuals on labor remuneration。
Turn individual invoicing from "asking about a tax rate" into a verifiable closed loop of business, taxes, and archives: www.kailingteck.com .
About Kailing Technology
As a national high-tech enterprise, Kailing Technology focuses on the digital and intelligent transformation of enterprise business-finance-tax and operations management, providing software products, system integration, implementation and delivery, and operational services for various government agencies, institutions, group enterprises, and SMEs.
The company has now formed ten core product lines, including: AI digital employee system, enterprise expense control management system, customer relationship management system, reverse invoicing management system, invoice issuance for individuals management system, electronic archives management system, tax fully digitalized e-invoice Leqi system, tax invoice management system, group tax filing system, and AI OCR recognition system. It is committed to connecting enterprise business, finance, tax, funds, and archive data to help customers improve operational efficiency, business-finance-tax compliance capabilities, and digital management levels.
If you have any business-finance-tax digital transformation needs, welcome to contact us. Beijing Kailing Technology will serve you wholeheartedly.
Keywords: invoice issuance for individuals tax rate, individual VAT invoice issuance, labor remuneration individual income tax, surcharges, individual invoicing, Kailing Technology
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing