
How to batch check before reverse invoicing whether natural persons serve as legal representatives or directors/supervisors/senior executives? Kailing Technology's natural person director/supervisor/senior executive verification interface performs batch verification and leaves a trail
When a resource recycling enterprise adds a large number of individual sellers in a day, finance searches enterprise employment information one by one, which is slow and easily misses people with the same name. Only after goods orders and payments have been formed do they discover that someone may simultaneously serve as the enterprise's legal representative, director, supervisor or senior manager, and the business has to be reworked and verified. The appropriate position for the Kailing Technology individual director, supervisor and senior manager verification interface is the entity review node before reverse invoicing: verify employment affiliations in batches, flag records requiring review, and save the query and processing traces at that time.
▍First clarify the purpose of verification, to avoid treating employment relationships as the sole conclusion
Resource recycling enterprises issue reverse invoices to individuals selling scrapped products; the applicable conditions are set out in State Taxation Administration Announcement No. 5 of 2024, including conditions on the seller's identity and cumulative sales amount. The announcement does not list "having served or currently serving as a director, supervisor or senior manager" as a separate absolute prohibition condition. Therefore, the value of querying employment relationships is to help enterprises identify potential business attributes, related-party transaction or identity inconsistency risks of the transaction entity, and then verify in combination with business registration, the actual seller, goods source and locally applicable rules. The system should not automatically equate all employment hits with prohibition of invoicing.
Enterprises should first define when a query is required, who has the right to initiate a query, and how results enter review. For newly added natural person sellers, a query can be made once at file creation; for long-term partners, recheck before invoicing at a reasonable interval or when key information changes. Batch query targets should come from genuine pending business, not from importing large numbers of unrelated natural persons into the system. The product can reduce the burden of manual one-by-one searches, but the actual applicability judgment remains the enterprise's responsibility in light of the evidence.
▍Deduplicate batch input first, then handle identity matching
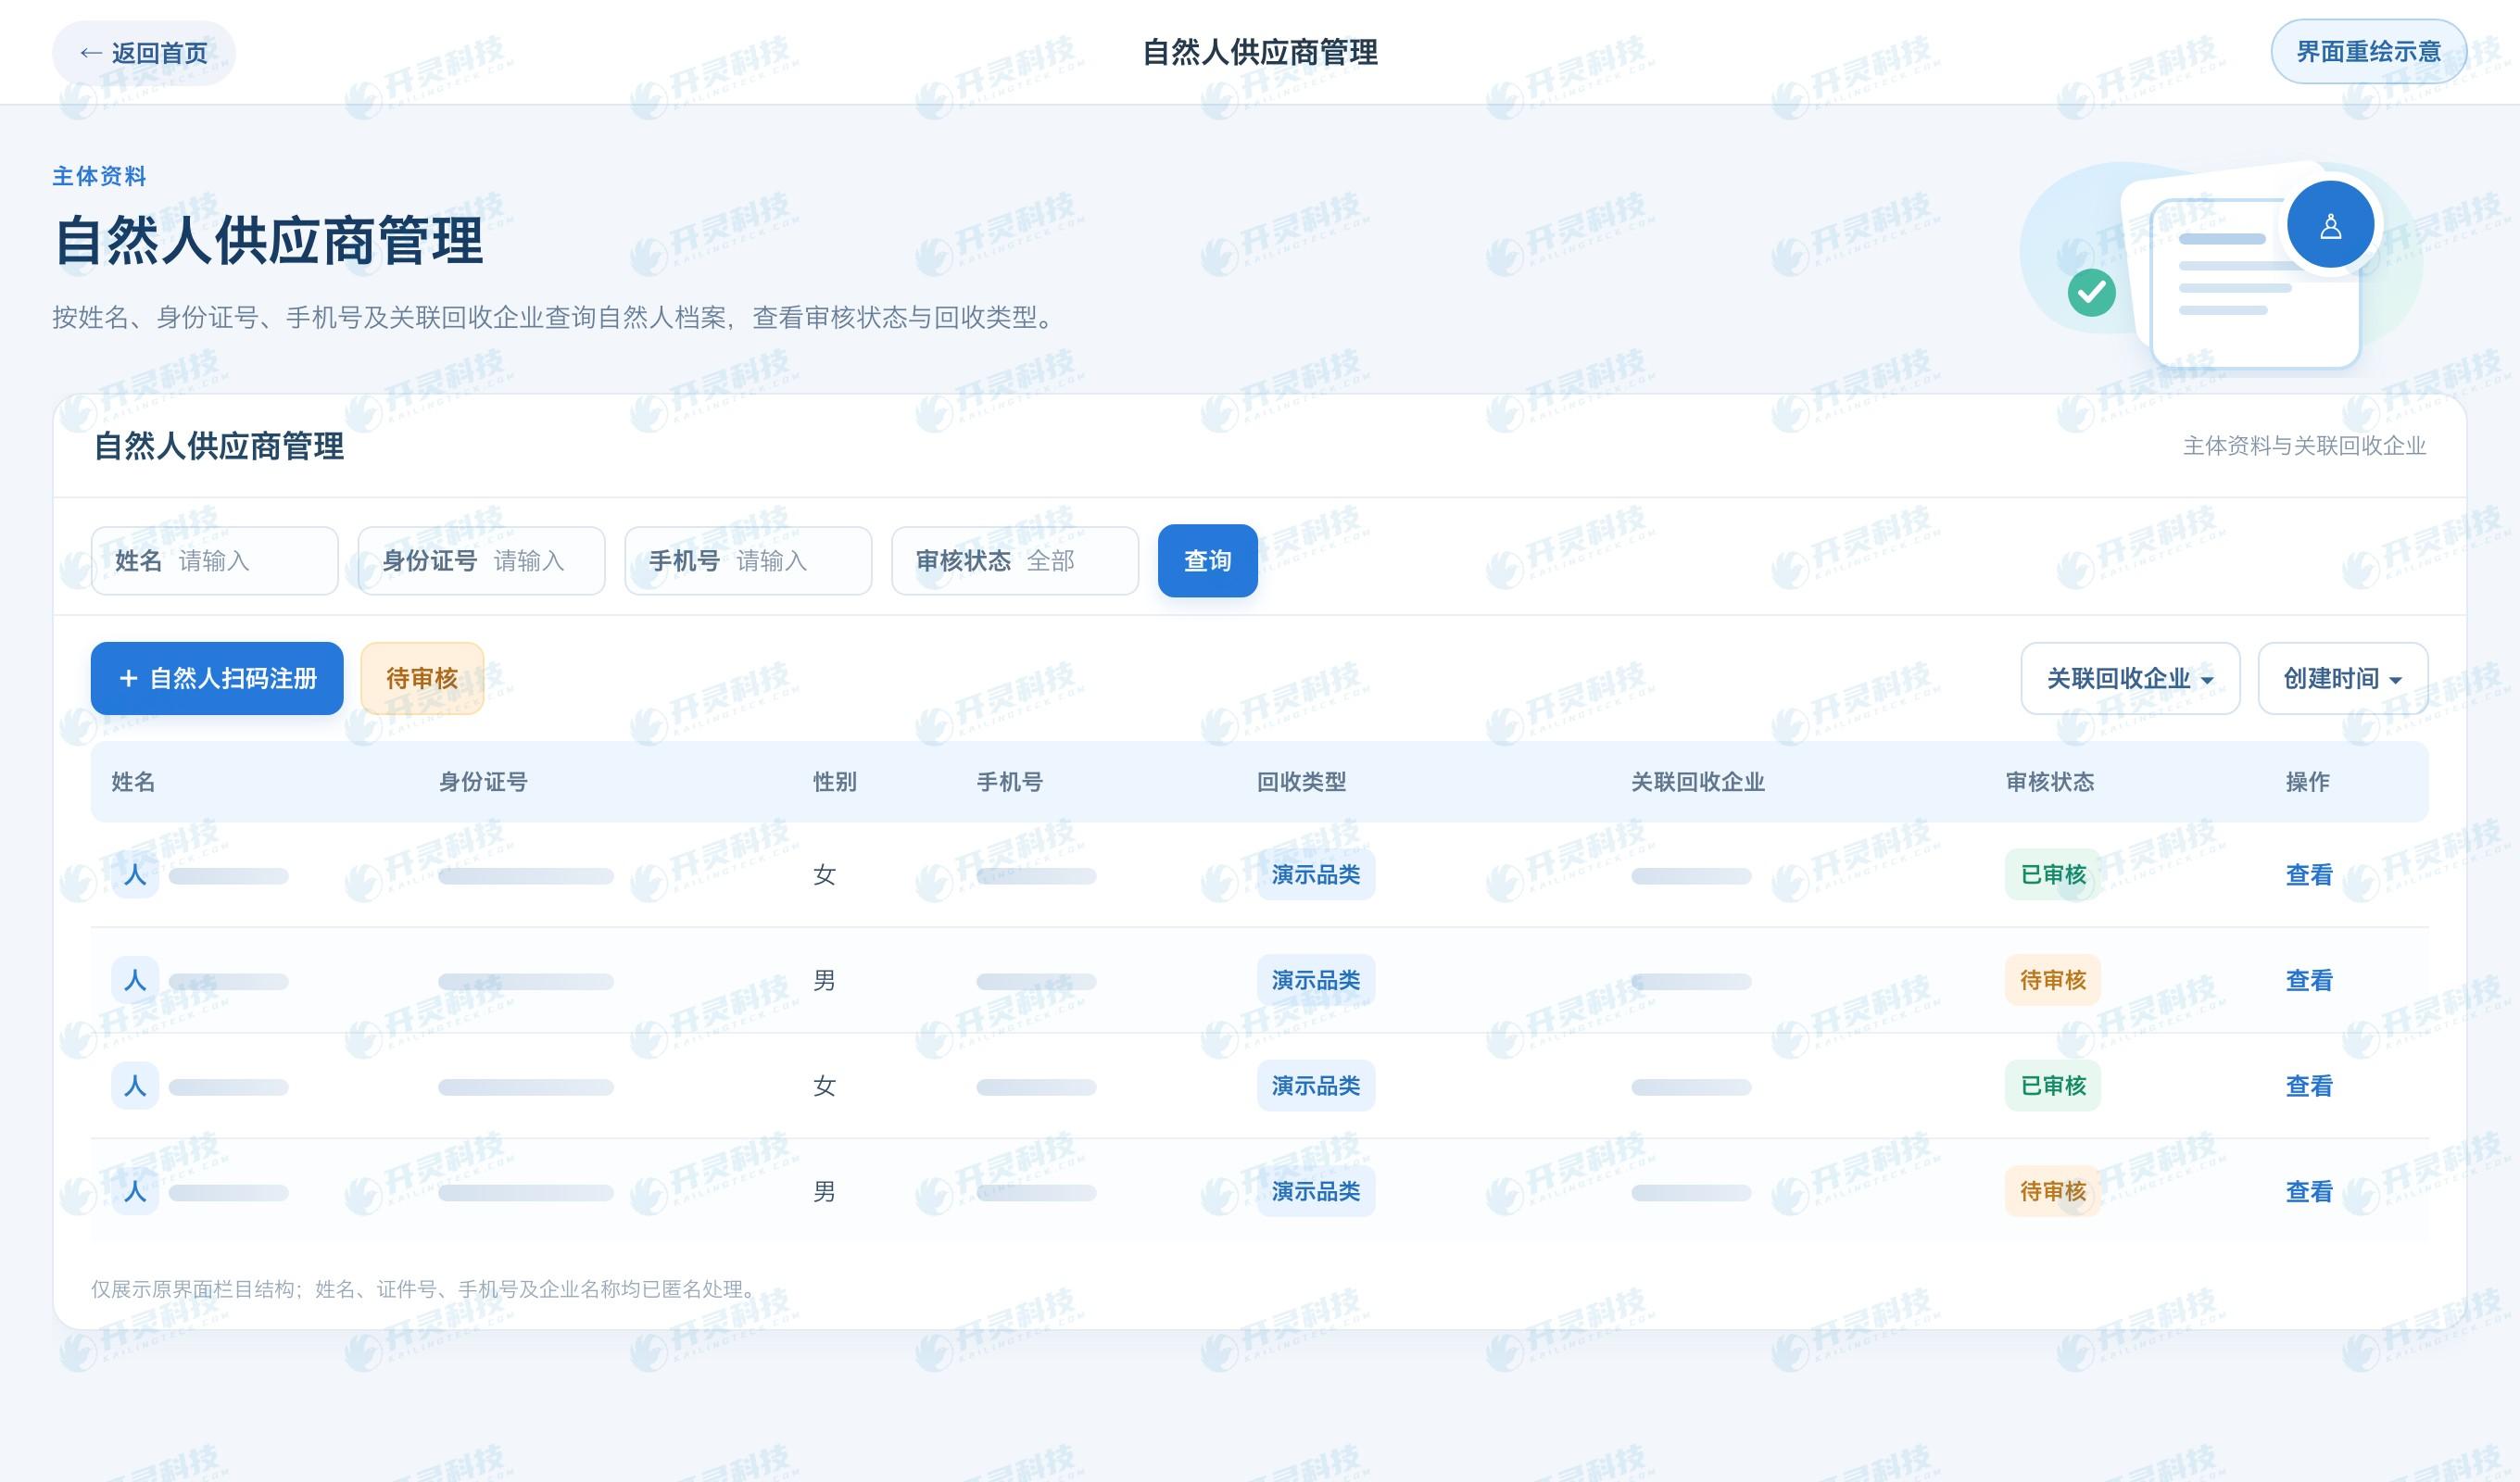
A pending invoicing list may contain duplicate records of the same natural person at multiple sites, two people with the same name but different identities, incorrectly entered ID information, or expired materials. Before calling the interface, format validation and necessary deduplication should be performed based on identity information lawfully obtained by the enterprise, linking multiple goods orders of one person to the same verification task. This reduces invalid calls and prevents one abnormal result from being mistaken for multiple independent risks. Upload fields should be based on the actual interface documentation and necessity, and no fixed message format should be fabricated in the article.
Returned results should also not be limited to "yes" and "no." More useful business handling is to distinguish states such as clear match, possible same name or insufficient information, query failure, and no match found, and to save the data source used, query time, and task number. What is described here is the review state recommended to be formed during implementation, not a claim that a certain external data interface already returns these fields. If there is a same name but inconsistent certificate, a historical position that has changed, or a lagging data source update, the system should transfer the record to manual review rather than directly making a factual determination on behalf of the reviewer.
▍Exception handling must have a responsible person, materials, and conclusions
After a verification hit, the reviewer needs to see the affiliated enterprise name, employment type, verifiable time information and data source; the specific visible fields depend on lawful authorization and actual interface capabilities. Business personnel then supplement how the seller obtained the scrapped products, whether the transaction was conducted in a personal capacity, and whether there is any affiliation with the enterprise. If business entity registration or other qualifications also need to be checked, this should be completed separately through the corresponding channels. Finally, form a business handling conclusion of "continue, supplement evidence, switch to another invoice path or suspend", and record the decision-maker and basis.
For query failures, an empty result must not be treated as not holding a position. The system can set retries or a manual query queue; if no credible result is obtained within the time limit, the goods order stays in pending review status. For situations where new information is discovered only after invoicing, the original query snapshot, subsequent discovery, and handling actions should be retained, and corrections made as necessary under applicable tax regulations. In this way, the trail covers not only successful hits but also misses, failures, and subsequent changes.
▍Connect verification conclusions into the invoicing chain, rather than saving a separate list
For interface integration, it is best to write results back using the individual's file number or business number, so that when finance opens a pending invoicing goods order, they can see the latest verification status and review opinion. If the same individual has multiple receipts, the system can process them according to the confirmed entity conclusion, but the goods and settlement amounts still need to be checked transaction by transaction. If the entity status changes, pending invoicing tasks should re-enter review without modifying the original records of historical business.
Batch task execution requires attention to idempotency and reconciliation: after a network timeout, query the task status first before deciding whether to retry, to avoid duplicate payment or duplicate generation of contradictory results. Enterprises can count pending, reviewed and incomplete tasks, but should not treat "all green" as proof of reverse invoicing compliance. Entity verification is only the entry point of the evidence chain; conditions such as receipt, payment, invoice and the individual's cumulative sales amount still need to be checked separately.
Enterprises operating across sites should also unify exception criteria. When site A has completed review and site B enters the same seller again, the system can indicate that a verification record already exists, but site B must be able to see the validity period and applicable scope of the conclusion. Re-verify after information changes and retain both the previous and current conclusions, so that batch capability truly serves continuous operations.
▍Personal information processing and go-live acceptance should also be designed together
Verification of employment relationships involves personal information of natural persons. The Personal Information Protection Law requires a clear processing purpose, minimal scope, and necessary protective measures. Enterprises should determine fields, access roles, retention periods, and external interface permissions based on a lawful processing basis and business needs, and query logs should record the operator and time; opening complete query results to unrelated personnel or retaining bulk plaintext lists for long periods both fail to meet the original intent of "verification only for this business." Specific compliance configurations must be implemented in conjunction with enterprise policies and interface contracts.
Four types of samples can be used for go-live validation: accurately matched current personnel, possible false positives from people with the same name, historical records of changed employment, and interface timeouts or incomplete returns. Check whether the system can suspend abnormal business, allow manual supplementary evidence, and save original query snapshots and final conclusions. If Kailing Technology's natural person director/supervisor/senior executive verification interface is connected with supplier onboarding and invoicing review, it can turn originally scattered search actions into a reviewable entity risk control step.
▍FAQ
Q: If a natural person is found to serve as a director, does that definitely prohibit reverse invoicing?
A: It is necessary to combine the applicable conditions of the announcement, the actual business attributes, and the current goods transaction, and the enterprise should review and handle it.
Q: If no employment information is found, does that mean the entity has no risk at all?
A: No. Identity, business registration, cumulative sales, and the actual seller and other conditions should also be checked, and attention should be paid to the timing of data updates.
Q: If the batch interface returns a failure, can it be released as a non-match?
A: Not advisable. The failure status should be recorded, retried, or escalated to manual verification, to avoid mistakenly writing a no-result as verified.
Q: Do employment query results need to be kept permanently?
A: The retention period and permissions should be determined according to lawful processing purposes, necessary scope, and applicable retention requirements, while retaining sufficient business audit traces.
Complete natural person entity verification before invoicing and retain the basis for each review. Learn about Kailing Technology's natural person director, supervisor, and senior executive verification solution: https://www.kailingteck.com/ziranren-chayan/ .
As a national high-tech enterprise, Kailing Technology focuses on the digital and intelligent transformation of enterprise business-finance-tax and operations management, providing software products, system integration, implementation and delivery, and operational services for various government agencies, institutions, group enterprises, and SMEs.
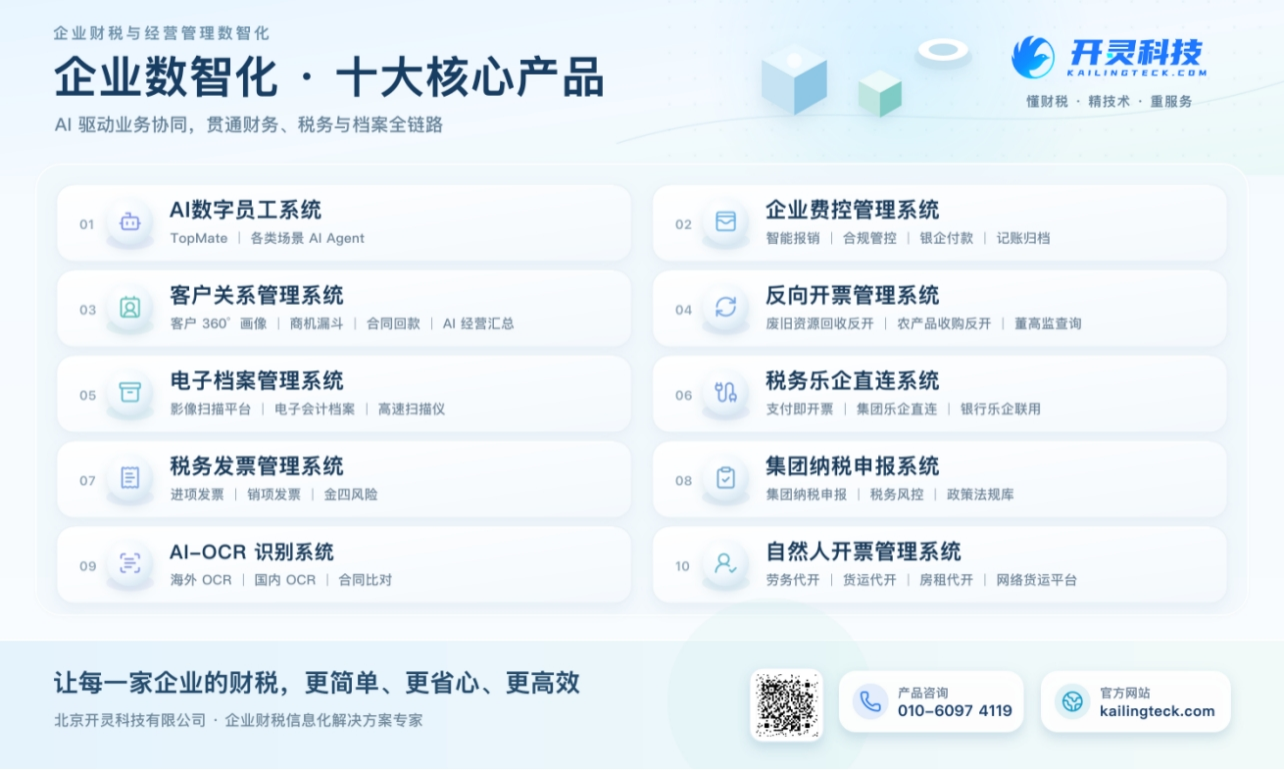
The company has now formed ten core product lines, including: AI digital employee system, enterprise expense control management system, customer relationship management system, reverse invoicing management system, invoice issuance for individuals management system, electronic archives management system, tax fully digitalized e-invoice Leqi system, tax invoice management system, group tax filing system, and AI OCR recognition system. It is committed to connecting enterprise business, finance, tax, funds, and archive data to help customers improve operational efficiency, business-finance-tax compliance capabilities, and digital management levels.
If you have any business-finance-tax digital transformation needs, welcome to contact us. Beijing Kailing Technology will serve you wholeheartedly.
Keywords: Individual director, supervisor and senior manager verification, Kailing Technology verification interface, reverse invoicing entity verification, batch employment query, pre-invoicing risk control
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing