
How soon after invoice type verification can you issue a fully digitalized e-invoice? Don't wait in vain
How long after invoice type verification for fully digitalized e-invoices can you issue invoices? First correct the premise: fully digitalized e-invoices themselves do not require invoice type verification
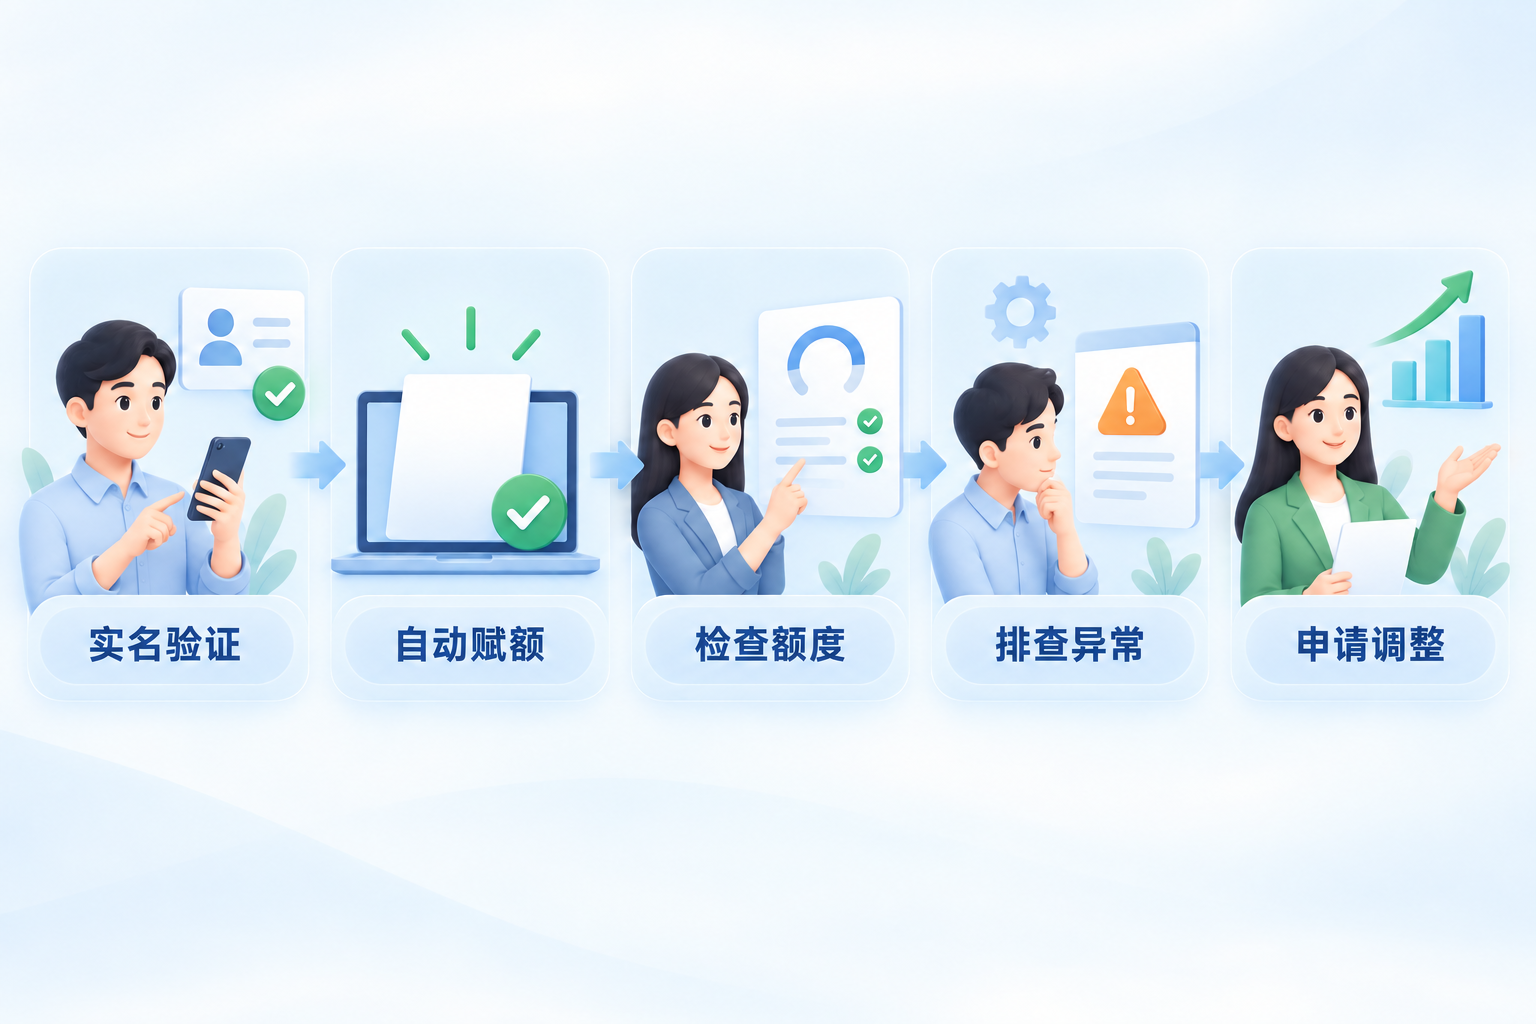
The handling logic for fully digitalized e-invoices differs from that for paper invoices. After taxpayers complete real-name verification, tax authorities automatically grant a total issuance amount quota based on tax big data and implement dynamic adjustments; fully digitalized e-invoices themselves do not require prior invoice type verification or collection. If the platform temporarily cannot issue invoices, you should not continue waiting for so-called "verification effectiveness," but should check the remaining available quota, filing status, personnel permissions, and risk exceptions.
Fully digitalized e-invoices do not require invoice type verification; after real-name verification, the system automatically grants a quota, and whether invoicing is possible should be based on the remaining quota and current status. |
▍1. First, correct the premise: fully digitalized e-invoices do not require invoice type verification
Public Q&A from the State Taxation Administration clarifies that fully digitalized e-invoices do not require invoice type verification or invoice collection; after taxpayers complete real-name verification, they can issue them through the electronic invoice service platform. Tax authorities determine the total issuance amount quota based on factors such as risk level, tax credit rating, and actual business conditions. Therefore, there is no nationwide uniform period of "waiting several hours or days after invoice type verification approval before issuing fully digitalized e-invoices." Paper invoices may still involve the original invoice type verification and collection process and should be judged separately from fully digitalized e-invoices. Please refer toPublic reply of the Ningxia Tax Service, State Taxation Administration。
▍2. Why might you still be unable to issue an invoice? First check the quota and status
First check the total issuance amount quota, the amount already used this month, and the remaining available quota, then verify the current period filing, filing comparison, real-name identity, invoicing personnel permissions, specific business qualifications, and system prompts. Insufficient quota, being in a risk management status, incomplete related filings, or incomplete operator permissions may all affect issuance. Do not "test the channel" through fictitious transactions or arbitrary issuance of small-amount invoices; if you cannot determine the meaning of a prompt, contact the competent tax authority to verify.
▍3. What if the quota is insufficient? Apply for an adjustment based on real business operations
The total issuance amount quota can be adjusted periodically or temporarily by the system, or taxpayers can apply for manual adjustment based on actual business needs. When applying, materials that explain the real business situation should be submitted according to local electronic invoice service platform requirements, and tax authorities will review them in accordance with regulations. Sales contracts, orders, historical invoicing, and business growth can serve as clues for organizing materials, but transactions must not be fabricated to increase the quota. Official explanations on quota granting and adjustment can be found inRelevant guidelines of the State Taxation Administration。
▍4. Systems can assist with the process, but cannot replace review
Kailing Technology's automated output invoicing system can, within the scope permitted by enterprise authorization, interface support, and current platform rules, assist in connecting orders, invoicing channels, result write-back, exception to-dos, accounting review, and archive collection. The system cannot automatically bypass insufficient quota, risk control, or qualification issues, and invoicing results do not necessarily mean accounting entry has been completed; OCR recognition and document collection likewise require personnel review. Invoice type verification and collection processes for fully digitalized e-invoices and paper invoices should be managed separately to avoid applying paper invoice experience to fully digitalized e-invoices.
Keywords: fully digitalized e-invoice type verification, fully digitalized e-invoice issuance time, fully digitalized e-invoices do not require invoice type verification, total issuance amount quota, remaining available quota, quota adjustment, automated output invoicing, Kailing Technology
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing