
Online operation for fully digitalized e-invoice type verification? First distinguish: fully digitalized e-invoices themselves require no verification
Online operation for fully digitalized e-invoice type verification? First distinguish: fully digitalized e-invoices themselves require no verification
Searching for "online operation for fully digitalized e-invoice type verification," many enterprises are actually trying to solve two problems: whether they can issue fully digitalized e-invoices now, and what to do when the available quota is insufficient. Neither of these two problems should copy the "invoice type verification" approach from the paper invoice era. According to current fully digitalized e-invoice rules, purely fully digitalized e-invoices themselves require no traditional invoice type verification and no receipt, and the system manages invoicing usage through the total invoice quota.
Fully digitalized e-invoices themselves require no traditional invoice type verification; what truly needs attention is the invoicing identity, total invoice quota, and risk prompts. |
▍1. Do fully digitalized e-invoices still require invoice type verification?
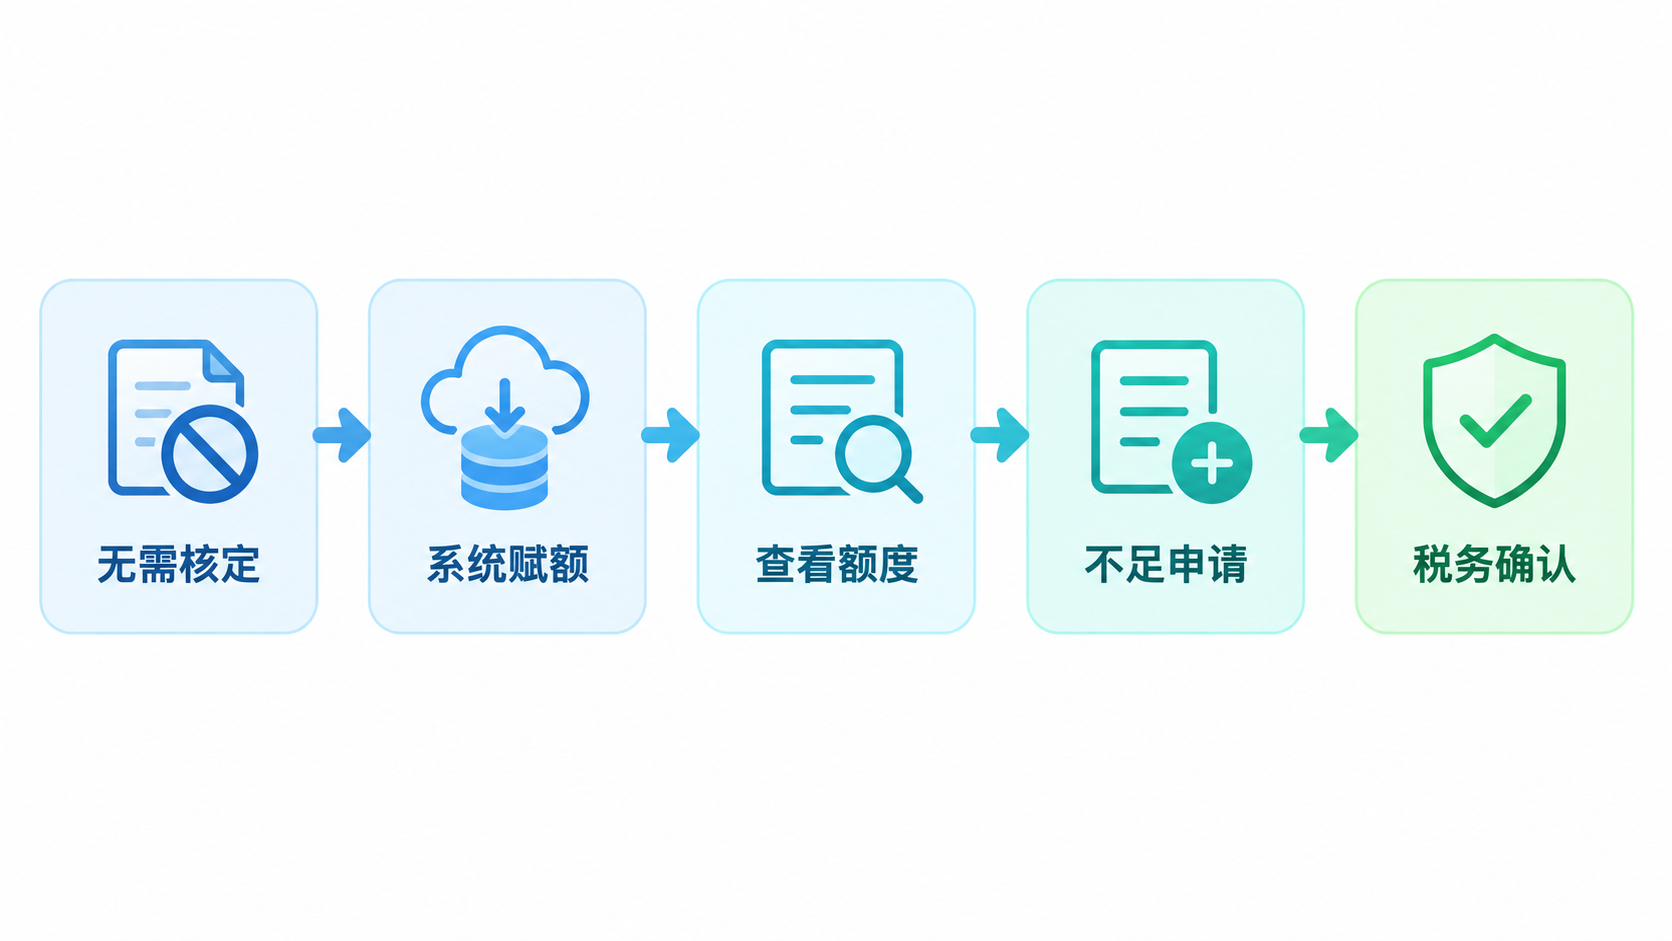
No need.Public reply from the tax authorityIt is clear that using fully digitalized e-invoices requires no tax control special equipment, no invoice type verification, and no need to receive fully digitalized e-invoices; the system will automatically grant a total invoice quota. Issued by the State Taxation AdministrationAnnouncement on the nationwide promotion of fully digitalized e-invoicesEffective from December 1, 2024, fully digitalized e-invoices have been officially promoted and applied nationwide.
▍2. Where exactly should you look online?
Enterprises should first log in to the nationally unified and standardized electronic tax bureau, and check the invoicing identity, total invoice quota, available quota, and risk prompts in the invoice business or electronic invoice service platform. Menu names may differ slightly by region, identity, and page version, and the competent tax authority and current system prompts shall prevail. Only if an enterprise also needs to use paper invoices, or handle other invoice usage needs, may matters such as the "invoice usage demand application" in the local electronic tax bureau be involved, and this cannot be confused with the issuance of purely fully digitalized e-invoices.
▍3. Are the total invoice quota and the "single-invoice limit" the same thing?
No. The total invoice quota is the overall upper limit on the invoice amount allowed to be issued within a calendar month, and is not equal to what was often called the single-invoice issuance limit in the past.Current reply from the tax authorityIt is explained that within the total invoice quota, taxpayers' invoicing is not subject to restrictions on the number of invoices or the single-invoice issuance limit. Therefore, when enterprises encounter "unable to issue invoices," they should first check the available quota for the current month, taxpayer status, and system risk prompts, rather than by default redoing invoice type verification.
▍4. What should you do when the quota is insufficient?
The total invoice quota for fully digitalized e-invoices has four adjustment methods: beginning-of-month quota adjustment, temporary quota adjustment, periodic quota adjustment, and manual quota adjustment.Public explanation by the State Taxation AdministrationFour types of adjustment mechanisms are introduced. When conditions are met, the system may adjust automatically; when there is a genuine temporary invoicing need but the quota is insufficient, you may apply for manual adjustment according to the prompts of the electronic tax bureau and submit genuine business materials. Whether an adjustment is made, the adjustment amount, and the processing time are subject to the tax authority's review and the system results, and it cannot be promised that "an application will definitely be approved."
▍5. What can an automatic invoicing system help with, and what can it not replace?
On the premise that the entity identity, business data, and authorization scope have been confirmed, Kailing Technology's automatic output invoice issuance, fully digitalized Leqi Direct Connection, and AI digital employee can assist in aggregating orders, verifying buyer information, preparing invoicing data, delivering invoices, and retaining processing records, reducing repeated entry. The system cannot replace tax authority quota granting, risk verification, or internal enterprise approval, nor can it bypass the quota control of the electronic invoice service platform; abnormal business should still be reviewed by authorized personnel.
Keywords: fully digitalized e-invoice type verification, online operation for fully digitalized e-invoices, total invoice quota, quota adjustment, electronic tax bureau, automatic output invoice issuance, fully digitalized Leqi, Kailing Technology
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing