010-6097 4119Book a Demo


A guide for enterprises to respond to fully digitalized e-invoice tax risks: detailed explanation of five major risks and prevention and control measuresPublished: 2025-01-16 17:27 With the full rollout of fully digitalized e-invoices, enterprise financial management has ushered in new opportunities, but also many challenges. Although the popularization of fully digitalized e-invoices improves financial efficiency, if enterprises fail to avoid potential risks in a timely manner, serious tax problems may very likely arise. The following are five major risks enterprises must guard against in the fully digitalized e-invoice era; a single misstep may lead to enormous tax risks. I. Risk of non-standard completion of the invoice remarks column - purchase of construction servicesThe invoice remarks column is an important part of invoice information, used to record additional transaction-related information such as project name, location, and project content. This information is crucial for tax management and auditing, helping tax authorities understand the enterprise's real transactions and prevent illegal acts such as tax evasion. 1. Tax RiskIf the remarks column of a purchased construction service invoice is filled in irregularly, it may prevent the tax authority from accurately understanding the enterprise's transaction situation, thereby triggering tax risks. For example, if the project name or location is not filled in the remarks column, the tax authority may consider that the transaction does not comply with tax law provisions and require the enterprise to pay additional taxes or face fines. 2. Financial riskNon-standard completion of the invoice remarks column may also distort an enterprise's financial data and cause trouble for financial management. For example, if the project content or amount is not filled in the remarks column, it may lead to inaccurate cost accounting and affect the enterprise's decisions and profitability. II. Tax risks behind a surge in input VAT invoices1. Risks of falsely issuing invoicesSome lawbreakers may exploit enterprises' demand for input VAT invoices to falsely issue special VAT invoices, thereby fraudulently obtaining export tax rebates or deducting input tax. This not only brings economic losses to enterprises but may also violate the law. 2. Risk of invoice content inconsistent with actual businessSome enterprises, in pursuit of growth in the number of input VAT invoices, may choose to cooperate with suppliers lacking legal qualifications, resulting in input VAT invoices whose contents do not match the actual business. In this case, the enterprise not only cannot enjoy the corresponding tax preferences, but may also have the invoices identified by tax authorities as "out-of-control invoices", further affecting the enterprise's normal operations. 3. Input VAT deduction riskBecause of an unreasonable surge in the number of input VAT invoices, enterprises may have excess input tax credits. This will reduce the enterprise's VAT burden, resulting in no tax payment or even enjoyment of excess input tax credit refunds. 4. Tax audit riskA surge in input VAT invoices often easily attracts the attention of tax authorities. Once listed as a key target of tax audits, enterprises will face strict tax inspections and may even incur adverse credit records, affecting long-term development. III. Surge in Output VAT Invoices and Tax Audit RiskA surge in output VAT invoices usually means increased sales for an enterprise, but it may also become a focus of tax authorities. Tax authorities compare information such as the enterprise's sales data and invoice issuance from previous years to assess whether there are illegal acts such as tax evasion or fraudulent invoicing. Once tax authorities believe there are suspicious points, they may initiate a tax audit procedure. IV. Risk of inconsistency between VAT filing and output VAT invoice amounts1. Tax RiskIf the VAT filing amount is inconsistent with the output VAT invoice amount, tax authorities may question the enterprise's tax filing and require the enterprise to provide explanations or corrections. If the enterprise cannot provide reasonable explanations or corrections, it may face tax penalties such as fines and late fees. 2. Tax RiskIf the VAT filing amount is inconsistent with the output VAT invoice amount, it may cause the enterprise's filing forms to be distorted, affecting the enterprise's financial condition and business decisions. V. Invoice voiding risks1. Tax Compliance RiskImproper voiding of invoices may lead to inaccurate tax information, thereby affecting the enterprise's tax compliance. If tax authorities discover a large number of non-standard voided invoices during inspection, they may question the enterprise, thereby triggering a tax audit. 2. Risk of Tax PenaltiesIf an enterprise deliberately voids invoices to evade taxes, once verified by the tax authorities, it will face severe tax penalties. This includes fines, late fees, and back taxes, and may even involve criminal liability.
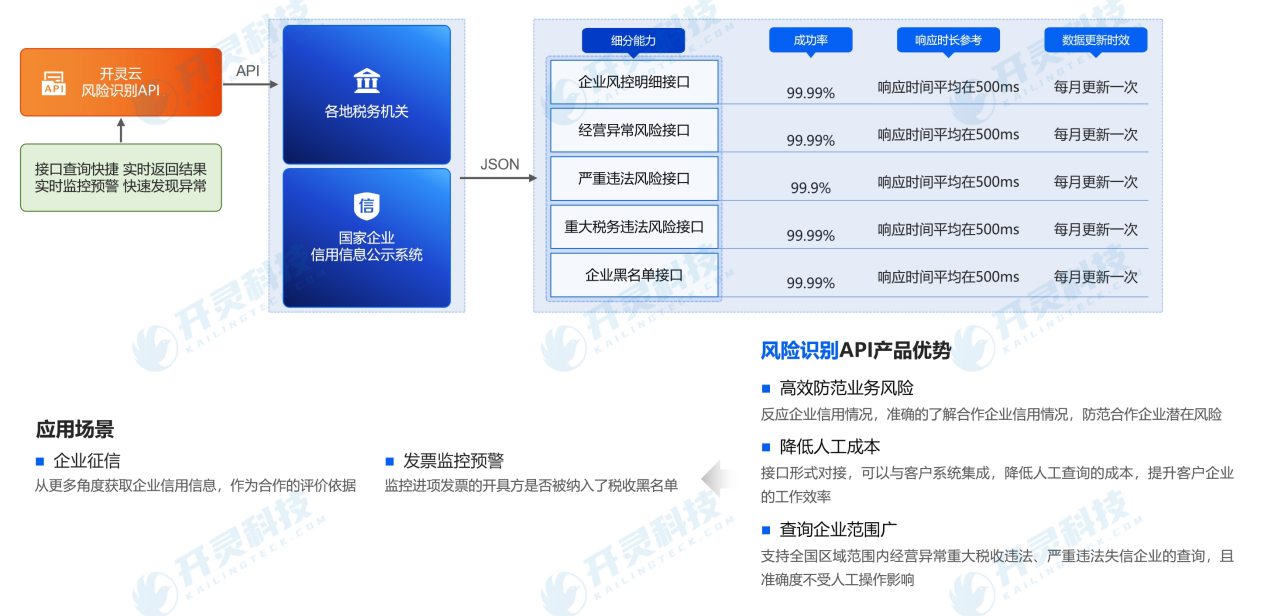
Enterprises should strengthen tax risk management and establish a complete tax risk control system to respond to changes in the tax collection and management environment under China Golden Tax Phase IV. ThroughKailing Tax Risk Control Monitoring System Solution, enterprises can promptly identify and resolve potential tax risks, improve financial management, reduce tax costs, and enhance market competitiveness.If your enterprise wants to learn more related information and tax solutions, welcome to contact Kailing Technology:https://www.kailingteck.com/h-col-114.html 。 As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: Solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output VAT invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, imaging OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system and other businesses, comprehensively advancing the digitalization process across various fields. If you have any business-finance-tax digital transformation needs, welcome to contact us. Beijing Kailing Technology will serve you wholeheartedly.
|