010-6097 4119Book a Demo


Who can and cannot be issued a reverse invoice? Kailing Technology's natural person verification interface automatically verifies and blocks directors, supervisors, and senior managers/sole proprietors before invoicingPublished: 2026-06-29 14:36 Reverse invoicing can only be issued to sellers of scrapped products/renewable resources with "individual" status; legal representatives, directors/supervisors/executives (directors, supervisors, senior managers), and registered individual industrial and commercial households cannot be individual sellers for reverse invoicing—issuing to the wrong party will be deemed false invoicing or entity non-compliance, facing tax supplements, fines, and even audit risks.How can the right person be selected before invoicing? This is Kailing Technology's approach with the individual verification interface:When reverse invoicing is initiated, the seller's real identity, business registration relationship, and registration status are verified in seconds; if a director, supervisor, senior manager, or registered sole proprietor is matched, it is blocked on the spot and no invoice is issued; eligible recipients are released compliantly and automatically logged. In one sentence — issue with confidence for those eligible, and block before invoicing for those not.
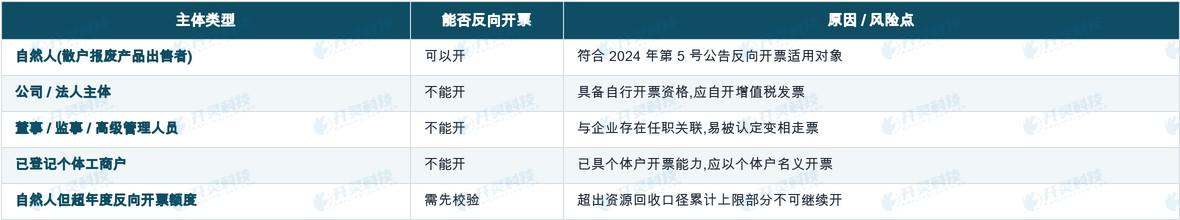
I. Most reverse invoicing risks arise from "invoicing the wrong target"Announcement No. 5 of 2024 of the State Taxation Administration (effective April 29, 2024) allows resource recycling enterprises to "reverse invoice" natural person sellers of scrapped products, solving the long-standing difficulty of individual sellers being unable to obtain invoices and recycling enterprises lacking input VAT invoices for a long time. However, the policy grants the qualification to "invoice natural persons," not an opening to "invoice anyone." The most commonly encountered pitfall in practice is precisely treating persons who should not be treated as natural persons as natural person sellers. Legal entity:Companies and enterprises themselves have their own invoicing qualifications and should issue VAT invoices themselves; they do not fall within the scope of natural persons for reverse invoicing. Directors, supervisors, and senior management (directors, supervisors, and senior management):Those who hold positions at the enterprise or have a specific affiliated relationship with the enterprise are excluded from natural persons eligible for reverse invoicing and are easily deemed to be conducting disguised invoice passing. Registered individual industrial and commercial households:Those that have completed industrial and commercial registration and have the ability to issue invoices themselves should issue invoices in the name of an individual business, rather than accepting reverse invoicing as an individual. Once these three types of entities are invoiced incorrectly, at best the invoice is deemed non-compliant and input VAT cannot be deducted, requiring tax payment; at worst it is characterized as false invoicing, facing fines and audits. The problem is that invoicing personnel cannot tell with the naked eye whether the other party is a supervisor of some company or has long been registered as a sole proprietor—this is precisely why the system must automatically verify before invoicing.
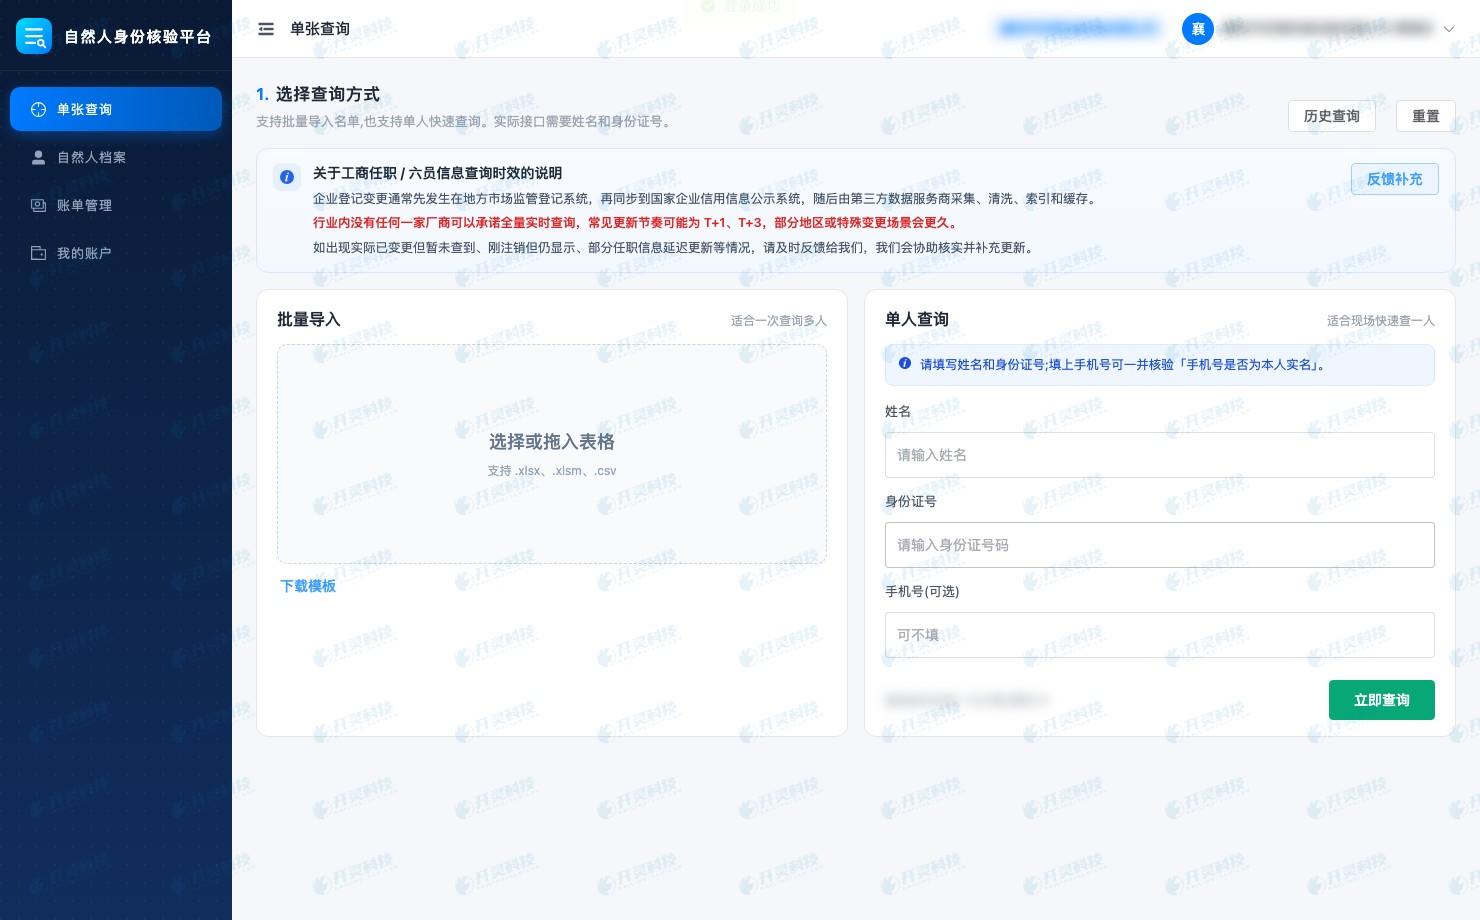
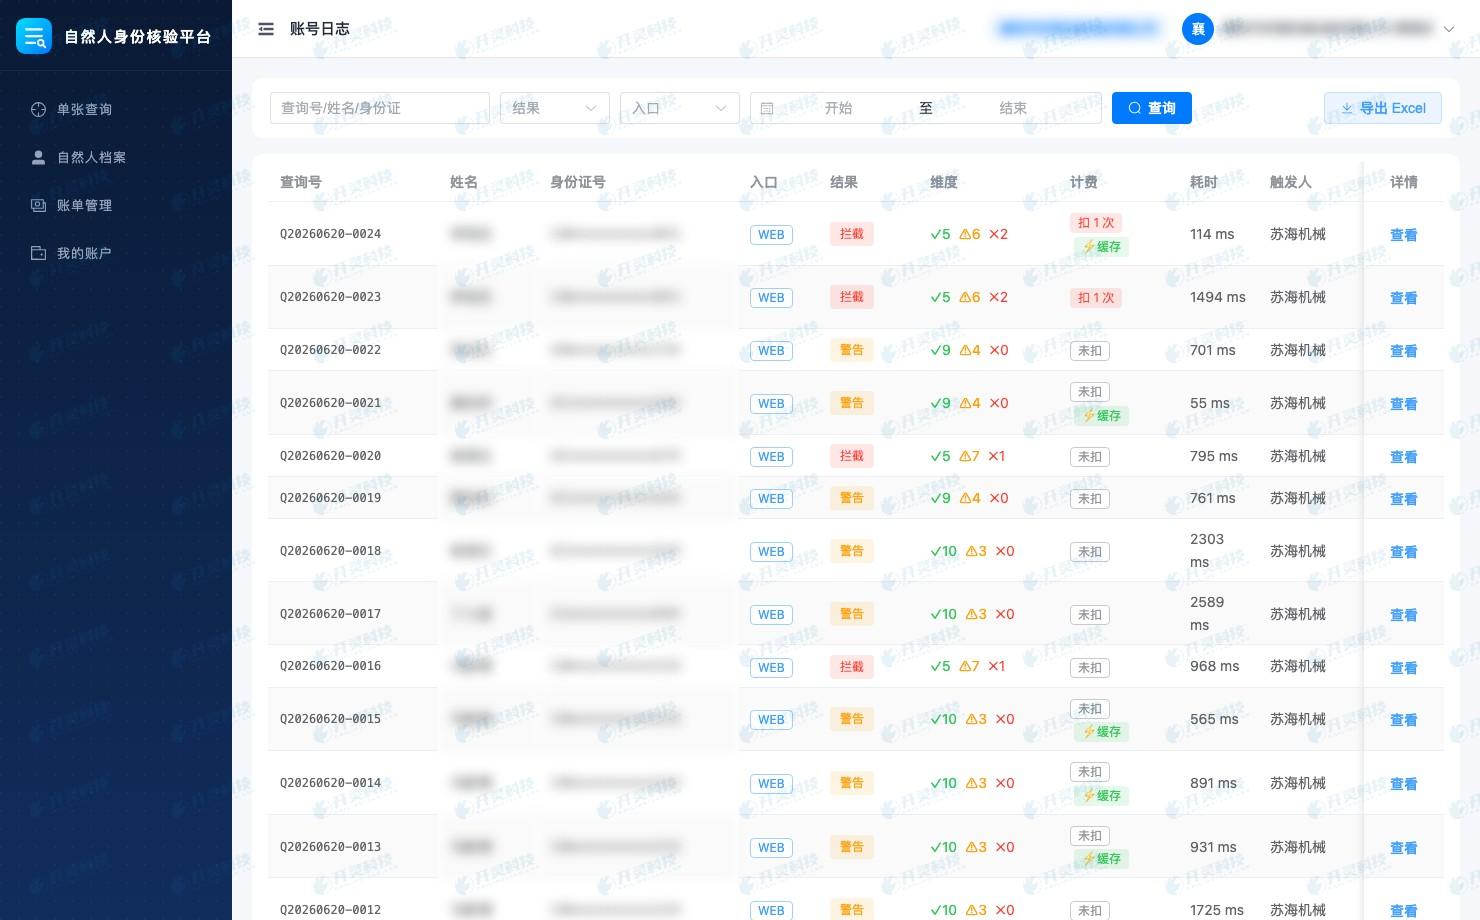
II. Kailing individual verification interface: a compliance gate for entity verification before invoice issuanceKailing Technology's individual identity verification platform is positioned as the "pre-invoicing risk control" for reverse invoicing/invoice issuance for individuals. It does not make invoicing decisions for you; rather, before the invoicing action actually occurs, it first answers clearly the question of "whether this person can issue an invoice." There are three core capabilities: Second-level verification of employment relationship and registration status:Integrate with business registration and individual income tax standards; by entering identity information, instantly determine whether a seller is a legal representative/supervisor or senior manager of an enterprise, or has already registered as an individual business, identifying ineligible entities on the spot. Annual reverse invoicing quota verification:Can verify an individual's annual reverse invoicing quota (cumulative upper limit under the resource recycling scope), avoiding compliance issues caused by a single individual's cumulative invoicing exceeding the limit. Historical query traceability:Every verification is recorded with a "pass / abnormal" result along with dimensions such as business registration positions, forming a traceable query ledger, providing evidence for later audits and internal reviews. Simply put, it turns the "entity judgment" that originally could only rely on experience and the other party's word into a standard action that can be checked with one click before invoicing, with results and traces.
III. From initiating invoicing to compliant release: how pre-invoicing verification and interception runAfter embedding verification into the invoicing process, entity compliance is no longer after-the-fact remediation but an unavoidable part of the process. The entire chain can be broken down into five steps:
The key to this process is placing interception at the "intercept upon hit" step—that is, before the invoicing action occurs. Compared with "invoice first, then remedy problems with red-letter reversal," pre-invoicing interception saves not only the trouble of red-letter reversal, but also blocks the risk of tax supplements and fines at the door in advance. Together with Kailing Technology's reverse invoicing systemFive-Flow IntegrationTraceability (self-verification flow, contract flow, business flow, tax flow, capital flow), and the entity verification result also becomes a self-verifiable link in the entire evidence chain.
Want reverse invoicing to "issue with confidence when it can be issued, and block before invoicing when it cannot be issued"? Welcome to learn about the Kailing Technology individual verification interface:https://www.kailingteck.com/h-col-127.html 。 As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: Solutions for businesses including sales contract management system, procurement contract management system, fully digitalized Leqi interface project, output automatic invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image OCR recognition system, automatic financial bookkeeping system, and electronic accounting archives system, comprehensively driving the digitalization process across various fields. If you have any business-finance-tax digital transformation needs, welcome to contact us. Beijing Kailing Technology will serve you wholeheartedly.
Keywords:reverse invoicing, individual verification API, director/supervisor/executive interception, individual industrial and commercial household, pre-invoicing compliance risk control, resource recycling、Agricultural product procurement |