
How much individual income tax on 50,000 yuan monthly invoicing by a sole proprietor? 2026 calculation and compliance points
How much individual income tax on 50,000 yuan monthly invoicing by a sole proprietor? 2026 calculation and compliance points
Knowing only that "50,000 yuan was invoiced in one month" is not enough to calculate the business income individual income tax for that month or the full year. The invoicing amount is sales data; the tax base for business income tax also depends on annual revenue, costs and expenses, collection method and tax already prepaid; VAT is yet another separate determination. Only by separating these sets of data can a verifiable result be obtained.
1. First distinguish invoicing amount, VAT and business income tax
The invoice amount does not equal profit, nor does it equal the taxable income of business income. If the sole proprietor is a small-scale VAT taxpayer, the threshold rules applicable from 2026 of 100,000 yuan monthly sales and 300,000 yuan quarterly sales for quarterly taxpayers must still be judged in light of the tax period, actual sales, invoice type and other applicable provisions; one cannot declare VAT exemption directly based only on "50,000 yuan invoiced", let alone infer that individual income tax is zero. General taxpayers, different businesses or consolidated calculation situations should be verified separately.
2. Business income is calculated on annual data
For individual industrial and commercial households under audit-based collection, the taxable income is calculated per tax law as total revenue for a tax year minus costs, expenses, taxes, losses, other expenditures and allowable prior-year losses. Expenditures must be related to production and operation, and true, complete and lawful vouchers and business evidence must be retained; one cannot simply conclude that "no invoice means no deduction at all", nor mix personal consumption into operating costs. For those under deemed collection, calculate according to the applicable method and deemed information determined by the competent tax authority, and do not apply the audit-based formula.
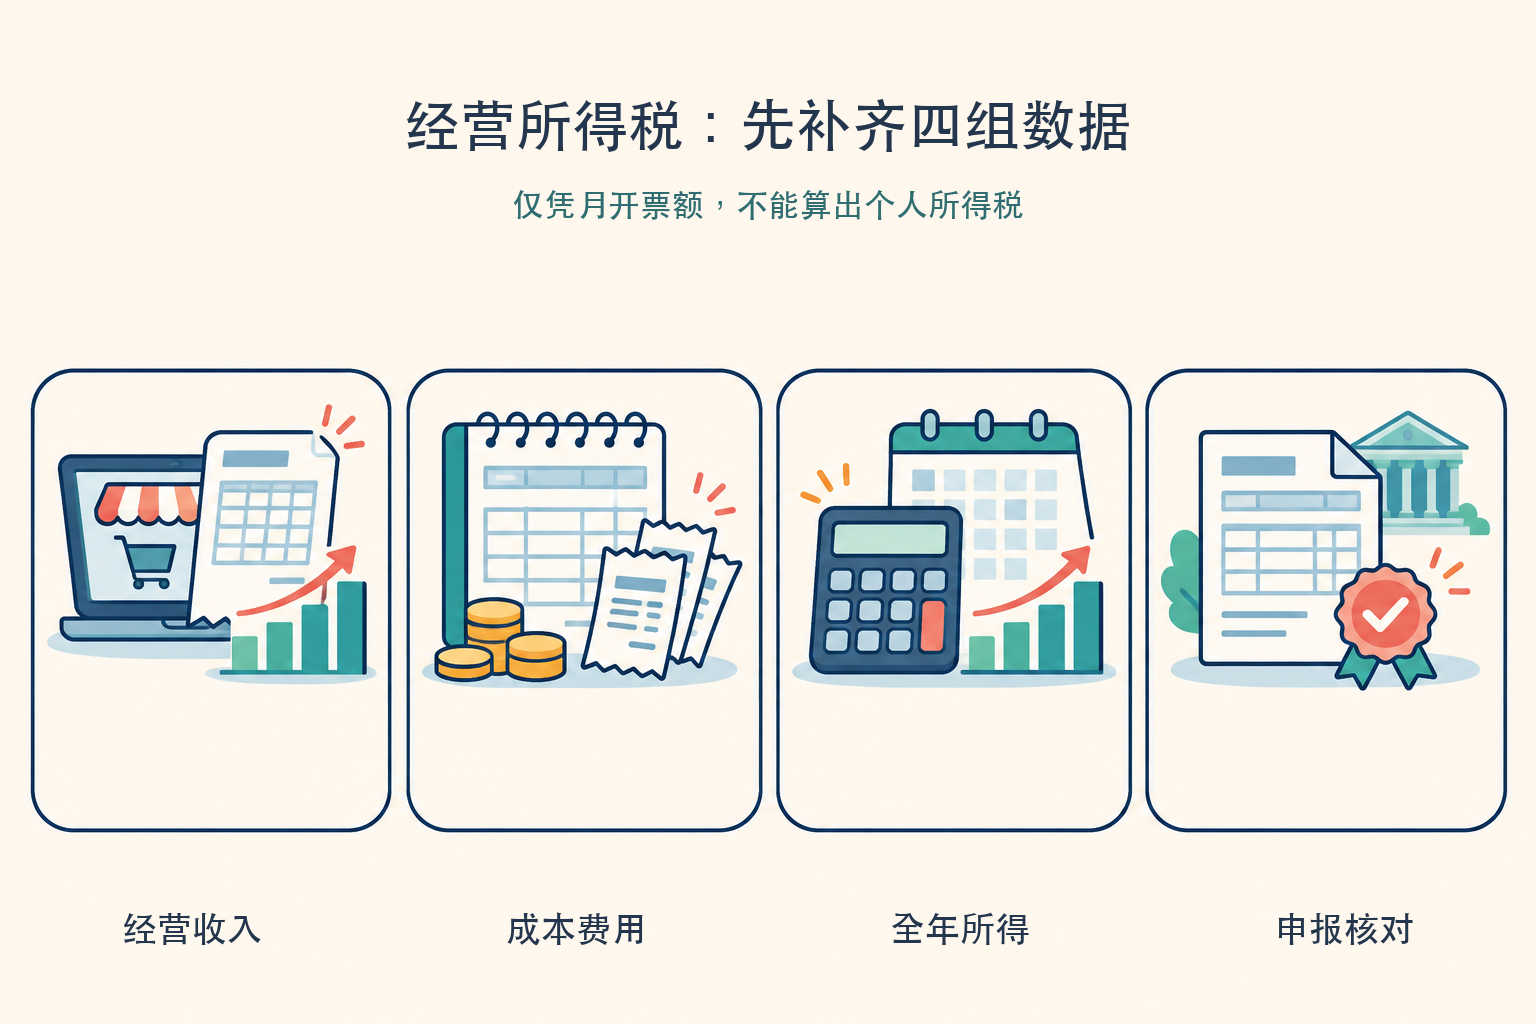
3. Complete these five items of information before trial calculation
At minimum, verify actual operating revenue and other business income for each month of the year, operating-related costs and expenses and allowable losses, audit-based or deemed collection method, tax already prepaid in the same tax year, and applicable preferential policies. Business income is calculated annually and prepaid monthly or quarterly; prepayment filing is generally handled within 15 days after the end of the month or quarter, and annual settlement is handled before March 31 of the year following the year the income is obtained. The actual filing path and deadline are subject to the current competent tax authority prompts.
4. After verifying preferences, see whether to pay or refund
Current policy provides that before December 31, 2027, individual industrial and commercial households enjoy a 50% reduction in individual income tax on the portion of annual taxable income not exceeding 2 million yuan, available under both audit-based and deemed collection. The preference applies to the tax amount calculated per regulations and cannot be understood as halving the invoicing amount or a fixed halving of the tax rate. The final tax payable, already prepaid and amount to be paid or refunded should be verified against the filing forms and tax authority rules.
5. Use tools to keep records and retain manual review
Kailing Technology's financial accounting and invoice-related products can serve as candidate tools for organizing sales, procurement and voucher data. Whether specific source data can be obtained, vouchers automatically generated or filing integrated depends on the actual product version, authorization, region and project implementation; business income tax should still be verified by the handling personnel against the collection method, tax calculation basis and filing results.
Therefore, there is no universal individual income tax amount for "50,000 yuan monthly invoicing". First form an annual trial calculation using business data, then verify it against the current filing forms and competent tax authority information.
Verification Basis
Ministry of Finance and State Taxation Administration 2026 VAT threshold announcement;"Measures for the Calculation of Individual Income Tax of Sole Proprietors";Announcement on issues concerning self-filing of individual income tax;Interpretation of the policy on halving individual income tax for individual industrial and commercial households。
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing