
Individual Income Tax Filing System Operation Guide: 2026 Full Withholding Client Workflow and Common Pitfalls
Individual Income Tax Filing System Operation Guide: 2026 Full Withholding Client Workflow and Common Pitfalls
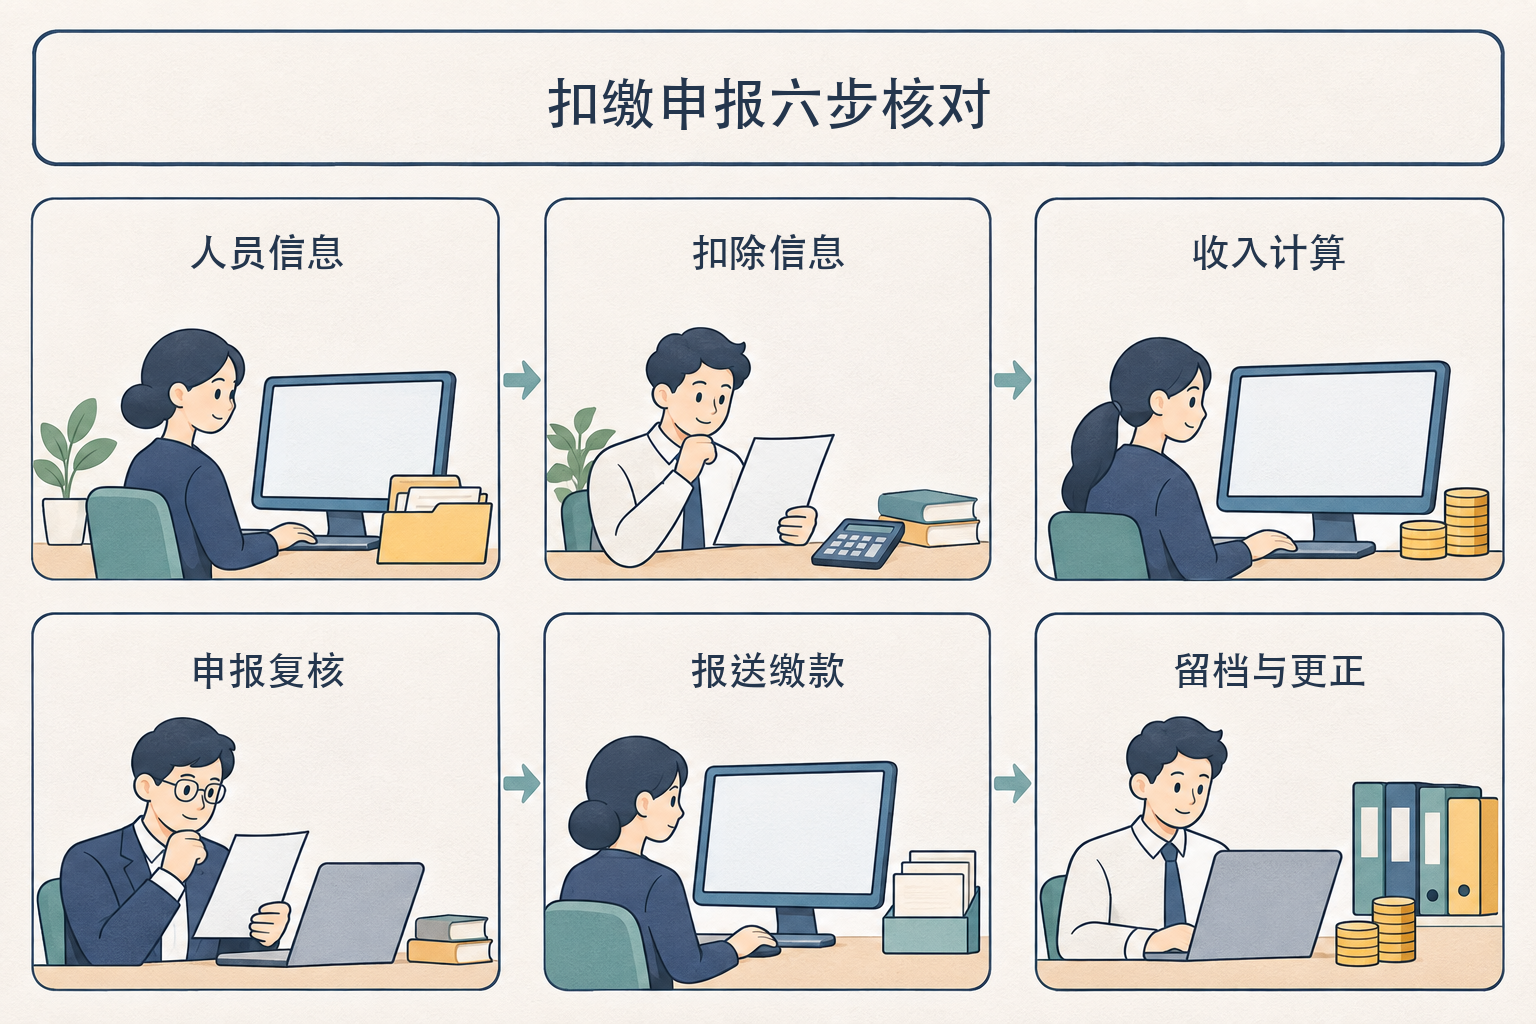
When withholding agents handle withholding filing for resident individuals' wages and salaries, they can verify in six steps: "personnel information—deduction information—income calculation—filing review—submission and payment—archiving and correction." The Measures for the Administration of Individual Income Tax Withholding Filing (Trial) provide that taxes withheld or collected monthly or each time shall be paid into the state treasury and filing forms submitted within 15 days of the following month; where the specific filing period falls on statutory holidays, the tax authorities' current notice shall prevail.
This guide uses common operations of the Natural Person Electronic Tax Bureau withholding client as its thread. Interfaces and available paths may vary by version, region and tax period, and current page prompts should be verified before operation. Kailing Technology's tax filing, risk control and electronic accounting archive solutions can serve as candidate tools for data organization and review; whether a specific interface, automatic data retrieval or submission capability is supported should be confirmed according to actual authorization and project acceptance, and filing responsibility remains with the withholding agent.
1. First Verify Personnel Information and Employment Start Dates
For new personnel, truthfully collect name, ID type and number, employment information, etc., complete submission and check feedback. If ID information does not match, check the original materials first and do not bypass validation merely by rewriting the payroll. When employees leave, report the departure date truthfully and submit; tax authority 2026 operational replies show that some new versions of the withholding client have removed the local "personnel status" field, so do not treat "mark as abnormal the month after departure" as a universal step. Personnel information changes and corrections of prior filings should also be handled separately.
2. Confirm the Year and Allocation of Special Additional Deductions
After employees report through channels such as the Individual Income Tax APP and designate the withholding agent, the employer downloads and updates the information in the withholding client. If it cannot be downloaded, first check the deduction year, designated employer, and whether name and ID information match. If deductions are to continue to be handled by the employer the following year, the taxpayer should confirm the next year's information each December; if not confirmed in time, the employer suspends deductions from January of the following year, and after confirmation can handle them according to regulations.
The current standard for the children's education special additional deduction is 2,000 yuan per child per month; parents may agree that one party deducts 100%, or each party deducts 50%; both parties cannot each deduct 100%. Housing loan interest and housing rent deductions cannot be enjoyed simultaneously in the same tax year, and verification should take into account the taxpayer and spouse's situation. Deduction eligibility and materials are truthfully reported by the taxpayer, and finance should not treat "the system will automatically prompt" as the sole control.
3. Verify Income and Tax Amounts Under the Cumulative Withholding Method
Resident individuals' wages and salaries are generally calculated monthly under the cumulative withholding method. Cumulative withholding taxable income = cumulative income - cumulative tax-exempt income - cumulative basic deduction - cumulative special deductions - cumulative special additional deductions - cumulative other deductions determined by law. Current period withholding tax payable = cumulative withholding taxable income × withholding rate - quick deduction - cumulative tax reduction and exemption amount - cumulative tax already withheld; if the result is negative, no refund is made for the time being. Generally, the cumulative basic deduction is calculated as 5,000 yuan per month multiplied by the number of months the taxpayer has been employed by the employer in the current year up to the current month; special policies should be verified separately.
Compare payroll, social insurance and housing fund details, deduction information and prior-period cumulative data to confirm the tax period and personnel scope. Back pay, post-departure income and annual one-time bonuses should be handled according to the nature of the income and current policy, and cannot be characterized solely by a single statement such as "merged into the current period" or "must be taxed separately." Eligible annual one-time bonuses may, until December 31, 2027, be taxed separately or merged into the comprehensive income of the year.
4. Review Before Submission, Handle Errors by Status After Submission
Before submission, verify the number of filers, total income, cumulative deductions, tax amount and ledgers, and confirm the operator and reviewer. If filing errors are found after successful submission, distinguish whether payment has been made within the filing period: tax authority operational replies indicate that where submission succeeded, payment has not been made and the filing period is still ongoing, the filing may be voided and resubmitted or corrected via paths permitted by the system; where payment has been made, or payment has not been made but the filing period has passed, the correction filing process should be followed. Correcting prior-period comprehensive income filings may require processing subsequent periods month by month, subject to the withholding client prompts and the competent tax authority's reply. Where overdue tax payment is involved, late fees are judged according to actual circumstances and regulations, and it cannot be asserted that every correction will incur late fees.
Retain filing forms, payment vouchers, personnel change records, deduction information and correction explanations, and manage access permissions in accordance with applicable accounting archive and personal information protection requirements. Electronic archive systems can help link related materials, but cannot replace filing verification and authenticity review of materials.
Verification Basis
State Taxation Administration Announcement No. 61 of 2018;State Taxation Administration Announcement No. 14 of 2023;Ministry of Finance and State Taxation Administration Announcement No. 30 of 2023;Guangxi Tax Authority 2026 Reply on Operations for Departed Personnel;Liaoning Tax Authority Reply on Correction Filing。
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing