
What to do when a sole proprietor's invoicing quota is exceeded? First distinguish quota, sales revenue and taxpayer status
When a sole proprietor says 'the invoicing quota is exceeded,' it usually may refer to three different things: insufficient available invoice quota for the month, sales revenue growth over consecutive operating periods, or the need to re-judge taxpayer registration status.
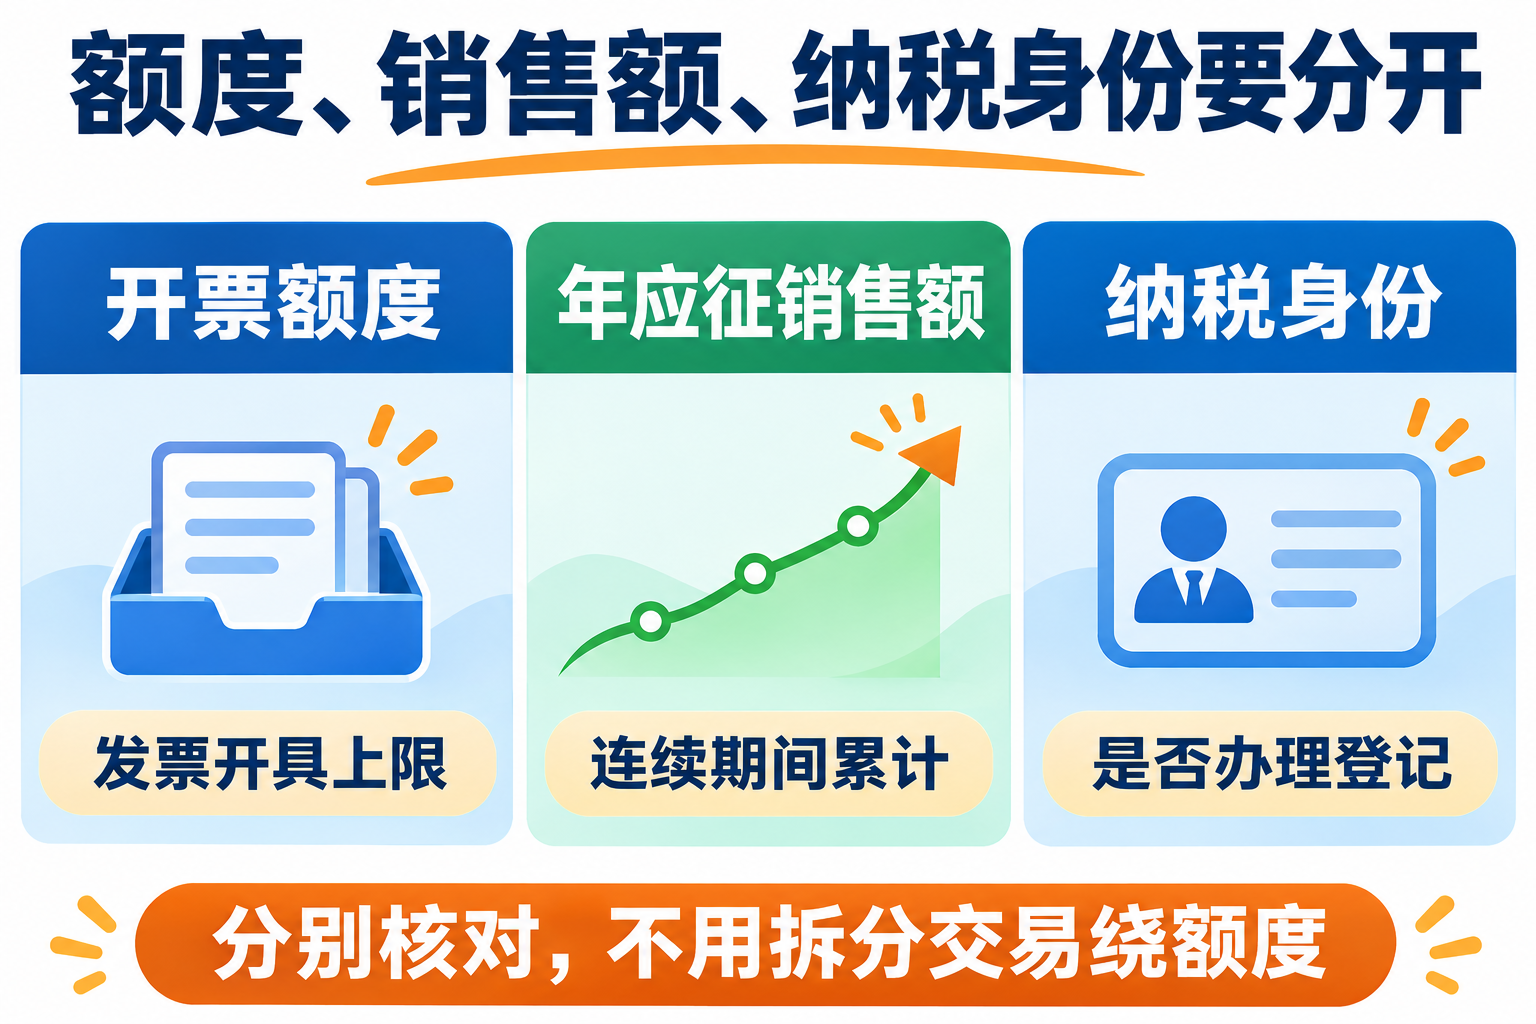
These three items are interrelated, but they are not the same indicator. The total invoice quota addresses "how much more can be invoiced this month"; annual VAT taxable sales are used to determine business scale; and taxpayer status relates to whether general taxpayer registration should be handled in accordance with regulations. Before handling, classify the issue first, so as to avoid mistakenly treating a quota adjustment as a status change, or using split transactions to conceal the true business scale.
Scenario 1: Only this month's available invoice quota is insufficient
First check the total invoice quota, used quota, remaining available quota, and adjustment records in the electronic tax bureau. The system has dynamic adjustment methods such as beginning-of-month, temporary, periodic, and manual adjustments; if automatic adjustment still cannot meet genuine business needs, you may apply for manual adjustment through the actual entry point of the local electronic tax bureau and submit materials that can prove the authenticity of the business and the invoicing needs. The adjustment result is verified by the tax authority based on the actual situation and does not mean that sales revenue or taxpayer status automatically changes.
Scenario 2: Sales revenue during consecutive operating periods has clearly grown
General taxpayer registration rules focus on annual VAT-taxable sales revenue. The public rules of the State Taxation Administration in 2026 clarify that annual taxable sales revenue is calculated cumulatively over an operating period of no more than twelve consecutive months or four quarters, and whether registration is required is judged according to current standards. Individual industrial and commercial households cannot look only at a single month, a single invoice or a single quota adjustment result. Filings, un-invoiced revenue, invoices, contracts and account books should be checked together to confirm whether the cumulative basis is complete.
Scenario 3: May reach the general taxpayer registration standard
If annual VAT taxable sales revenue reaches the current registration standard, you should determine and complete general taxpayer registration in accordance with regulations; whether exception circumstances apply, when to register, and from when to apply the general tax calculation method should be based on current laws and regulations and the reply of the competent tax authority. Conversely, even if the registration standard has not yet been reached, it does not mean you may split contracts, transfer revenue, or borrow other entities to issue invoices without genuine transactions.
Why can't quotas be circumvented by splitting entities?
The real business entity, contract performance, receipts and payments, delivery of goods or services, and tax filing should be consistent. Artificially splitting transactions to circumvent quota or registration requirements may cause invoice content to be inconsistent with the actual business, underreporting of income, or entity mismatch. The compliant path should be to first restore the real business, and then separately handle quota applications, income filing, and taxpayer registration.
How can enterprise systems provide verifiable assistance?
Internal systems can place quota balance, sales revenue for consecutive periods, uninvoiced revenue, contracts, and invoicing tasks into the same reconciliation checklist, flagging anomalies while retaining human judgment. When evaluating Kailing Technology related solutions, you should require on-site demonstration of data sources, authorization boundaries, definition explanations, and modification logs, and must not treat system prompts as the tax authority's registration conclusion, nor promote them as automatically avoiding quota limits.
Conclusion: Quota, sales amount, and tax status should be checked and handled separately. When invoicing demand exceeds the available quota, first check dynamic quota adjustment; when business scale grows, simultaneously check sales amount for consecutive periods; when the standard is reached, then handle registration in accordance with the law, and do not circumvent it by splitting transactions.
Official basis:State Taxation Administration: Dynamic adjustment of total invoice quota;State Taxation Administration: Matters concerning registration management of VAT general taxpayers;Tianjin Taxation: Definition of consecutive periods for annual taxable sales revenue。
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing