
What is the input VAT invoice comprehensive service platform? First distinguish official functions from enterprise tools
What is the input VAT invoice comprehensive service platform? First distinguish official functions from enterprise tools
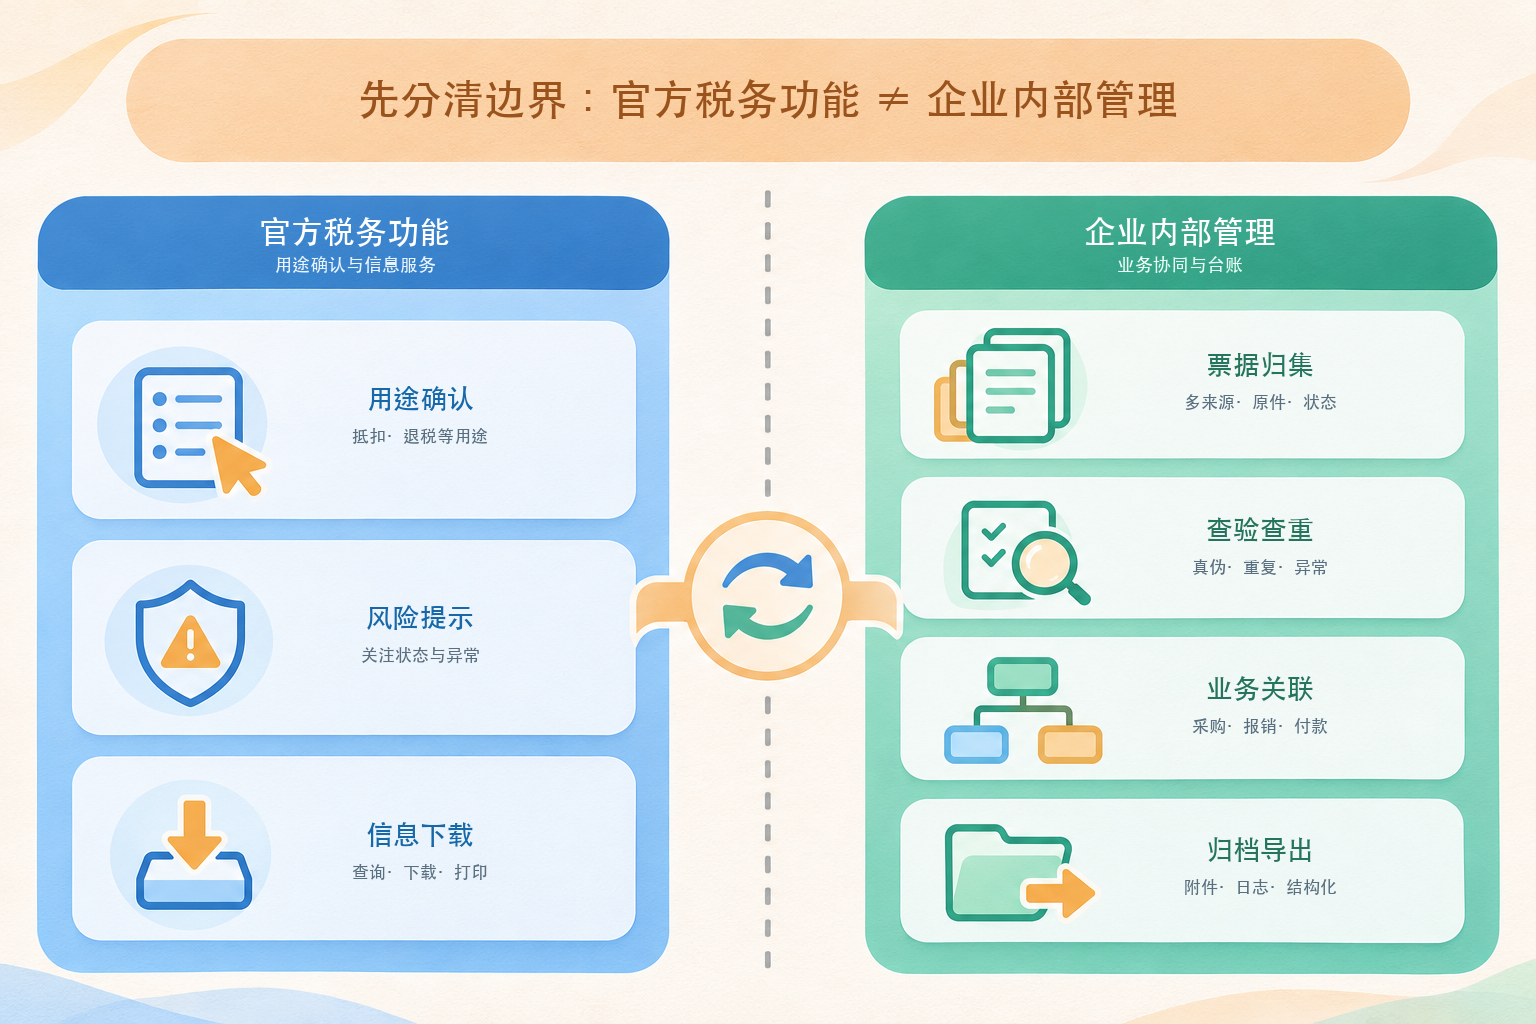
When searching for "input VAT invoice comprehensive service platform," first distinguish two types of objects: one is the official functions provided by tax authorities, such as invoice use confirmation, risk alerts, and information downloads; the other is input VAT invoice management software purchased by enterprises for internal collection, verification and duplicate checking, business association, and archiving. Official tax functions are not a commercial platform that can be freely purchased, and enterprise tools cannot replace statutory use confirmation and tax filing.
The original draft directly interpreted the keyword as commercial software selection and used "direct connection to the tax bureau to automatically obtain all invoice sources" as the first criterion, which easily confuses official services with enterprise products. After fully digitalized e-invoices were rolled out nationwide in 2024, the tax digital account took over some functions of the VAT invoice integrated service platform; the specific entry point and available matters should still be subject to the actual interface of the electronic tax bureau where the enterprise is located.
▍What problems do official functions mainly solve
The State Taxation Administration's public Q&A explains that when taxpayers obtain VAT deduction vouchers that meet requirements and need to use them for filing deductions, export tax rebates, or tax rebates on behalf of others, they should confirm the purpose through the tax digital account or the VAT invoice integrated service platform. The tax digital account also provides risk alerts, invoice query statistics, and information downloads. Enterprises should enter through the official website of the competent tax authority or the provincial electronic tax bureau and verify the current identity, permissions, and tax period.
▍What problems do enterprise internal management tools mainly solve
Enterprise tools serve procurement, reimbursement, payment, accounting, and archiving processes. Common tasks include receiving original files submitted by employees or suppliers, organizing invoices from multiple channels, verifying status and identifying duplicate submissions, associating invoices with orders, contracts, acceptance, reimbursement forms, payments, and vouchers, and retaining attachments and operation logs. These capabilities belong to enterprise internal control and do not mean the tax authority has recognized deduction eligibility.
▍Why "automatic acquisition of all invoice sources" cannot be treated as an unconditional promise
Which invoices an enterprise can obtain depends on lawful authorization, region, invoice type, interface availability, enterprise identity, version configuration, and implementation scope. Even if the official tax account can query a certain invoice, it does not mean commercial software can automatically synchronize original files, structured data, and status in all deployments; conversely, invoices uploaded by employees or received by email do not mean official purpose confirmation has been completed. During selection, the enterprise's real invoice types and failure scenarios must be demonstrated on site.
▍Four boundary tests should be done when selecting enterprise tools
First, the collection test: Use fully digitalized e-invoice original files, email attachments, employee submissions, and other vouchers actually used by the enterprise to verify whether original documents, sources, times, and structured fields can be retained.Second, the verification and duplicate-checking test: Submit normal invoices, duplicate invoices, red-flushed invoices, or invoices with abnormal status, and check whether the system explains the reason for the hit and provides a handling path.Third, the business association test: Verify the association of one invoice with multiple orders, multiple invoices with one order, returns and red-letter reversals, as well as with purchases, reimbursements, payments, and vouchers.Fourth, the exit test: Export the original files, fields, statuses, logs, and associations on site, and verify the formats, permissions, and batch capabilities.
▍How official purpose confirmation connects with enterprise processes
Enterprise tools may, within lawful interfaces and authorization scope, form pending lists, synchronize or record purpose status, and feed exceptions back to finance personnel; the period, selection, statistical confirmation, and filing results in official channels still need to be checked. When interfaces fail, permissions are insufficient, or status is out of sync, failure logs should be retained and manual review should be used; "system shows processed" cannot be treated as the sole evidence that statutory procedures are complete.
▍For which needs should Kailing Technology be evaluated
If an enterprise needs cross-source collection, verification and duplicate checking, multi-entity ledgers, or connection of input VAT invoices with procurement, reimbursement, and accounting archives, Kailing Technology's relevant solutions can be included as candidates; specific invoice types, invoice acquisition channels, tax interfaces, purpose confirmation, exception monitoring, deployment methods, and data export capabilities should be subject to the actual version, lawful authorization, demonstration, contract, and delivery list. Enterprises with small invoice volumes and simple processes may also first evaluate existing finance or expense control modules to avoid duplicate procurement.
Official basis:State Taxation Administration Q&A on channels for purpose confirmation of fully digitalized e-invoicesState that the relevant functions can be used through the tax digital account;Tax authority 2026 invoice selection Q&AList query, purpose status, and exception troubleshooting paths.
Keywords: input VAT invoice comprehensive service platform, tax digital account, invoice use confirmation, deduction selection, input VAT invoice management, invoice duplicate checking, invoice archiving, Kailing Technology
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing