
How do individuals issue invoices? 2026 compliant three-step pitfall avoidance for invoice issuance on behalf
How do individuals issue invoices? 2026 compliant three-step pitfall avoidance for invoice issuance on behalf
First determine the real business and the nature of the income, then prepare materials and apply for invoice issuance on behalf according to the requirements of the local tax authority, and finally the payer separately verifies VAT, individual income tax, and accounting archiving responsibilities. Obtaining an invoice only completes the voucher stage and does not mean all taxes have been settled.
When enterprises purchase consulting, design, transportation, leasing, and other services from individuals, it is easiest to mistake "issuing an invoice" for full compliance. In practice, contracts, performance, invoicing, payment, withholding, and archiving should be viewed as one evidence chain. Entry names, items eligible for invoice issuance on behalf, and required materials may differ by region, business type, and applicant identity, and the current requirements of the local electronic tax bureau or competent tax authority where the application is made should prevail.
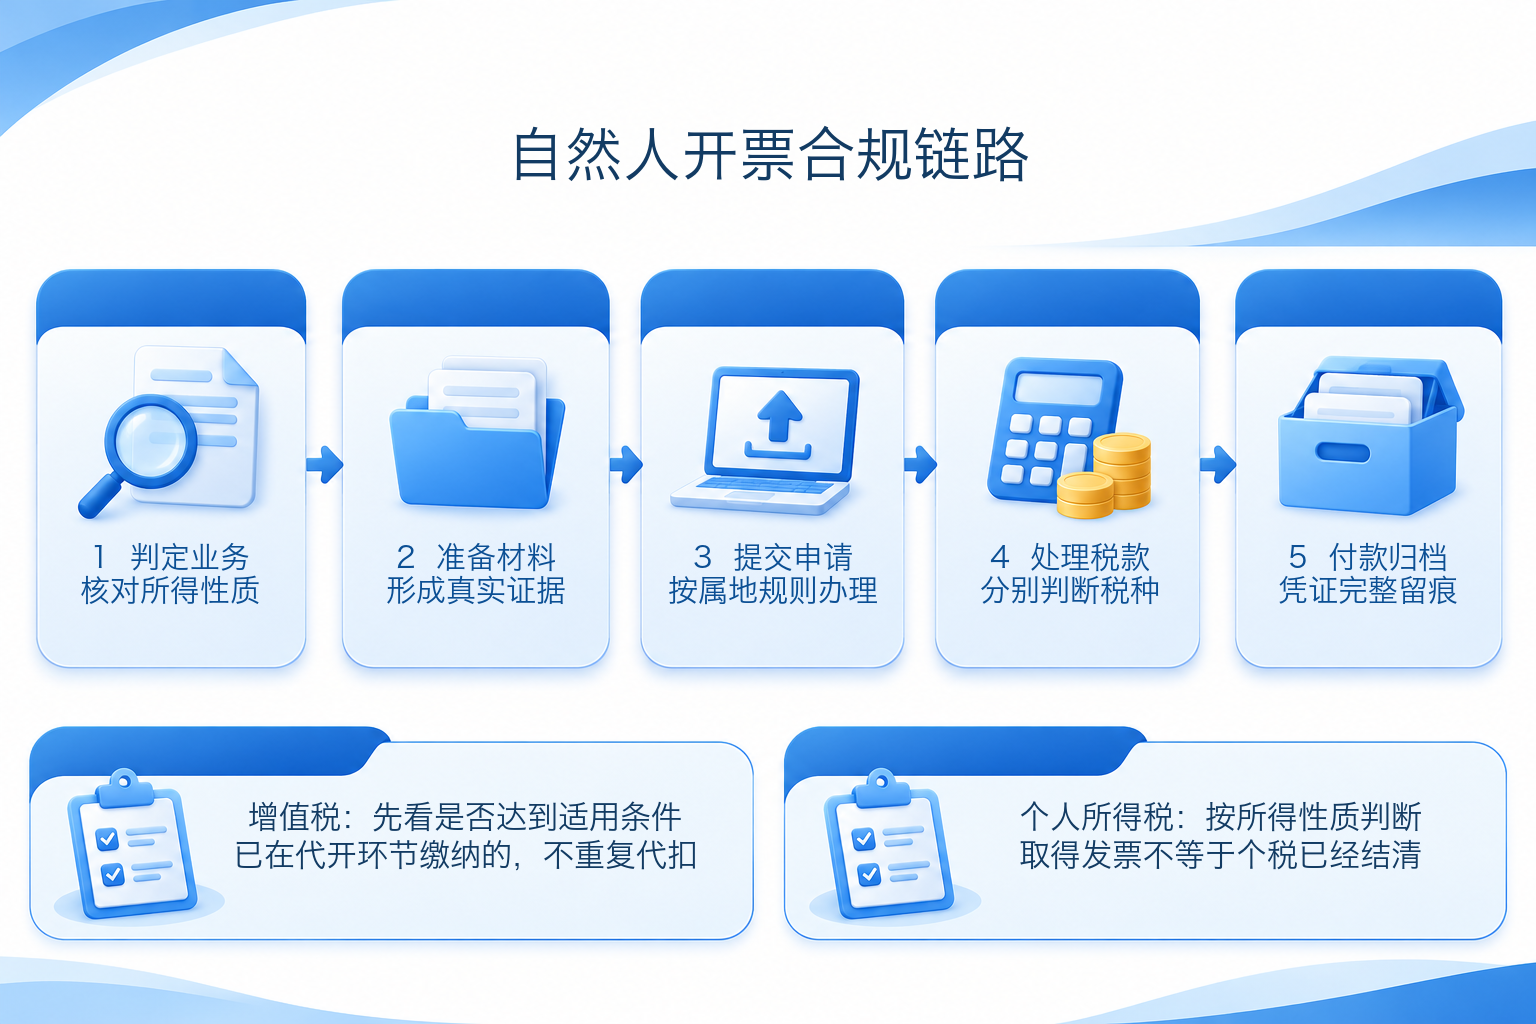
▍Step 1: First determine the nature of the transaction and income
First confirm whether the individual has an employment relationship with the payer, whether the service is completed independently, who bears the tools, costs, and business risks, and whether the business has the characteristics of continuous operation. The bases for determining wages and salaries, remuneration for labor services, and business income differ; you cannot rely only on the invoice item name, nor directly determine business income merely because the individual applied for an invoice. If the contract name is inconsistent with actual performance, the contract, acceptance, and settlement materials should first be corrected according to the real business.
▍Step 2: Prepare authentic materials and apply according to local rules
Typically, you should prepare the individual's identity information, the purchaser's invoicing information, contracts or orders, performance evidence such as service results or transport documents, settlement amounts, and payment collection information. The specific materials, processing channels, available items, and tax treatment are subject to the requirements of the competent tax authority. For occasional single transactions, you may first check the individual business section of the electronic tax bureau or local tax filing guidelines; for bulk business, you may use collaboration tools with real-business verification, permission audit trails, and material archiving capabilities, but tools cannot replace the tax authority's review and issuance authority.
▍Step 3: Determine VAT and individual income tax separately
From November 1, 2026, where a domestic entity and an individual conduct a taxable transaction that meets the regulations, and the individual's sales amount with a single withholding agent for the current transaction (day) reaches the per-transaction tax threshold, the domestic entity withholds VAT when paying the price in accordance with regulations; where the individual has already paid VAT at the invoice issuance on behalf stage or other stages, no duplicate withholding is made. This rule has clear applicable conditions and cannot be summarized as all transactions by individuals being uniformly withheld by the payer.
Individual income tax must be determined separately. Where the income is remuneration for labor services, author's remuneration, or royalties, the payer performs obligations under the current withholding and prepayment measures; whether it is business income should be determined based on registration, business substance, and the position of the competent tax authority. Invoices, tax payment certificates, and individual income tax withholding records cannot substitute for one another.
▍What problems should the system solve for batch processing?
The value of high-frequency scenarios lies not in "faster invoicing" but in forming a unified material checklist among business personnel, finance, and individuals, verifying identity and transaction information, recording submission, return, resubmission, and tax treatment results, and linking and archiving invoices, contracts, performance, payments, and withholding materials. Kailing Technology's related solutions can provide material collaboration, bulk processing, and archive linkage capabilities according to the enterprise's actual processes; the specific support scope, tax interfaces, and processing regions should be verified with real business samples before project implementation.
Implementation checklist: Whether the business characterization has a basis; whether the contract and performance are consistent; whether the invoicing channel meets local requirements; whether VAT reaches the withholding situation; whether individual income tax is determined separately; whether invoices, tax payment, payment, and withholding materials are completely linked.
Disclaimer: This article is general business reference and does not constitute tax advice. Handling rules and individual case facts may differ by location; actual handling should be based on the opinions of the competent tax authority and professionals.
Official basis:Ministry of Finance and State Taxation Administration Announcement No. 28 of 2026;Q&A of the Tianjin Municipal Tax Service of the State Taxation Administration, October 29, 2026;Withholding and prepayment guidelines related to State Taxation Administration Announcement No. 61 of 2018。
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing