
How is individual income tax withheld and remitted after a natural person issues an invoice? The 2026 three-step compliance method
How is individual income tax withheld and remitted after a natural person issues an invoice? The 2026 three-step compliance method
A natural person obtaining an invoice does not mean individual income tax has been settled. Before payment, enterprises should first determine the nature of the income based on the contract, identity, and business substance; where it is resident individual remuneration for personal services, author's remuneration, or royalties, the payer usually withholds and prepays according to regulations; where it is lawfully confirmed business income, it is filed under business income rules. From November 1, 2026, new domestic entity withholding rules for natural person VAT apply and must be judged separately from individual income tax.
The most dangerous practice in practice is to determine the tax item solely by looking at the invoice product name or remarks. The same "consulting service" may be labor independently provided by an individual, or business activities continuously carried out by a registered business entity; whether there is an employment relationship, who organizes the tools and risks, how the contract is agreed, and whether the business is independent and continuous all affect the judgment. An invoice is one piece of evidence, but it cannot replace the determination of the nature of income.
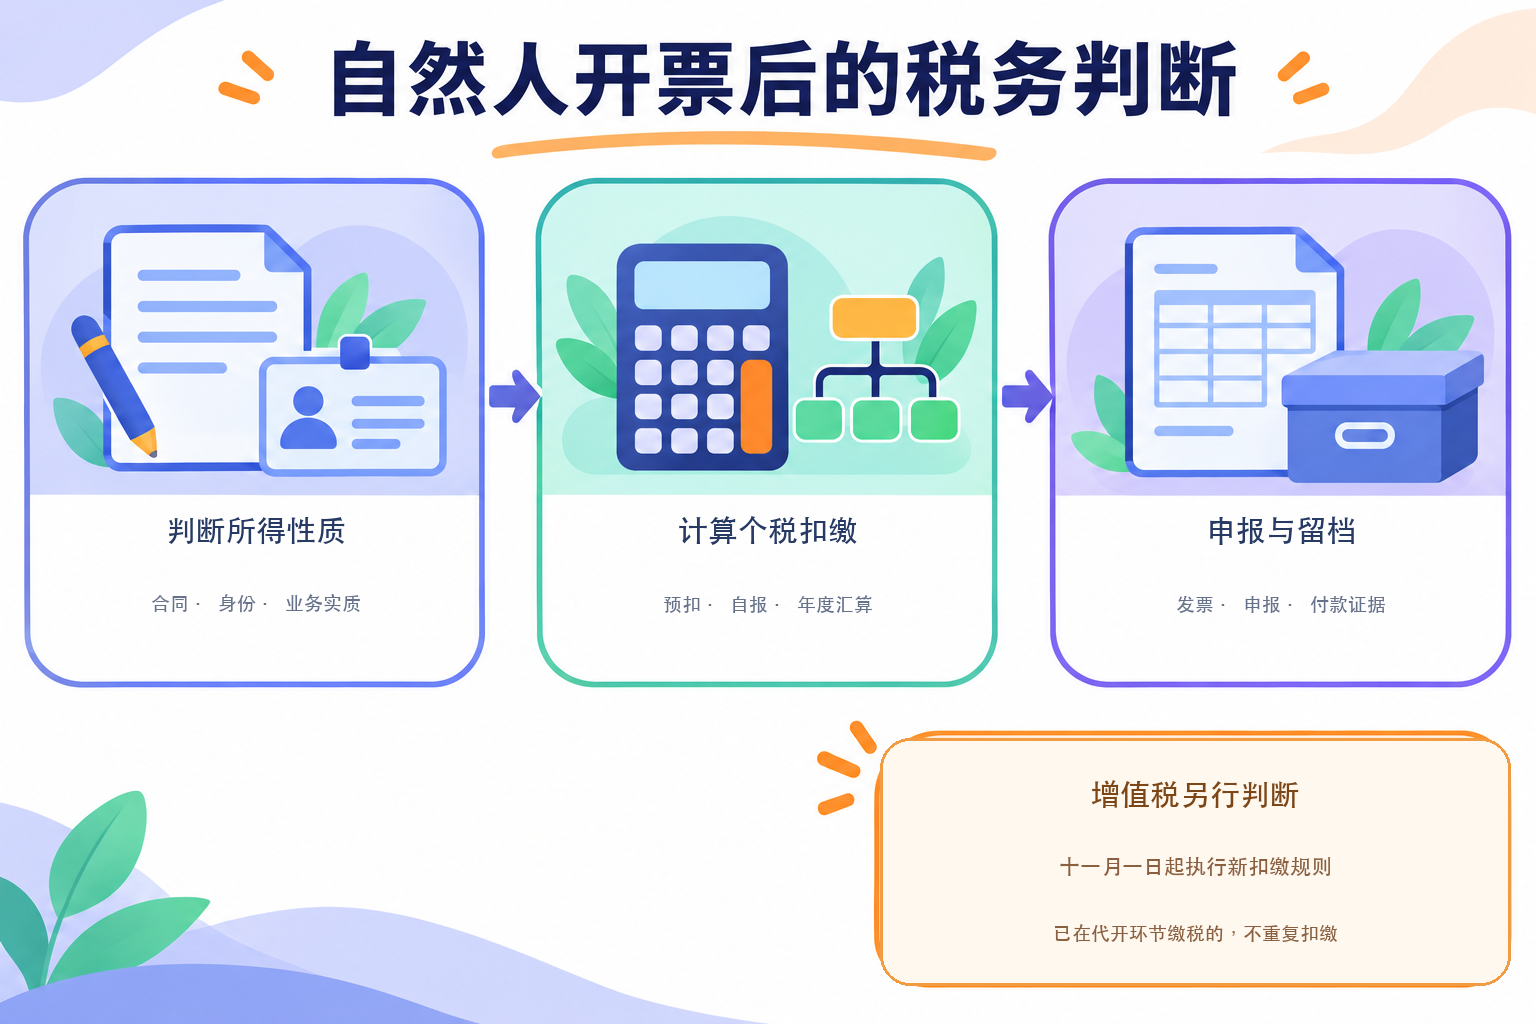
▍Step 1: First determine the nature of the income; do not mechanically apply tax rates based on invoice names
Article 9 of the Individual Income Tax Law stipulates that for individual income tax, the income earner is the taxpayer, and the unit or individual paying the income is the withholding agent; however, whether to withhold and how to calculate must also be combined with the income item. For resident individuals receiving labor remuneration, author's remuneration, and royalties, the payer withholds and prepays on a per-time or monthly basis, and the individual includes them in the annual comprehensive income settlement, with excess tax refunded and shortfall supplemented.
Business income is calculated annually, prepaid by the taxpayer after the end of each month or quarter, and settled before March 31 of the following year. However, "invoice issuance by a natural person" cannot be directly inferred as business income. Enterprises should verify the counterparty's registered identity, contractual rights and obligations, business continuity, and the position of the competent tax authority; special scenarios such as platform employment and reverse invoicing may also be subject to dedicated withholding or agency rules.
▍Step 2: For labor remuneration, calculate according to the official withholding method
State Taxation Administration Announcement No. 61 of 2018 stipulates that when withholding and prepaying individual income tax on resident individuals' labor remuneration, if each income does not exceed 4,000 yuan, the expense deduction is calculated at 800 yuan; if each income exceeds 4,000 yuan, the expense deduction is calculated at 20 percent of the income. Labor remuneration applies Individual Income Tax Withholding Rate Table 2, with withholding rates from 20 percent to 40 percent, plus quick deduction amounts.
"Each time" also cannot be simply understood as each invoice or each transfer. For one-time income, the income obtained from that item counts as one time; for continuous income from the same project, the income obtained within one month counts as one time. The public reply of the State Taxation Administration also clarified that income obtained from the same project within one month should be judged on a consolidated basis. Splitting invoices or payments while the business substance remains continuous does not automatically change the calculation basis.
Taking a resident individual receiving 10,000 yuan of labor remuneration at one time as an example, the income exceeds 4,000 yuan, so 20 percent of the expenses are deducted first, and the taxable income for withholding and prepayment is 8,000 yuan; the 20 percent withholding rate for this bracket applies, and the withheld tax is 1,600 yuan. This amount is only a withholding, not the final annual tax burden; after the resident individual's annual settlement, excess tax may be refunded or shortfall supplemented.
▍Step 3: Retain sufficient evidence in the payment, filing, and archiving stages
Tax withheld or collected by the withholding agent each month or each time shall be paid into the state treasury and the individual income tax withholding return shall be submitted within the fifteenth day of the following month. Enterprises shall retain natural person identity and taxpayer identification information, contracts, service results or acceptance, invoices, income item determination, calculation working papers, payment and filing payment records. If the tax authority or invoice remarks indicate that withholding is by the payer, this should also be included in the pre-payment check.
Kailing Technology's capabilities related to invoice issuance for individuals, expense control, filing, and electronic archiving can, on a project basis, collect business, invoice, and filing data and configure income items, withholding prompts, and voucher associations. Actual tax items, withholding results, and filings still require enterprises to review in light of business facts, the position of the competent tax authority, and system calculation results; "automatic matching" cannot be promoted as requiring no human judgment or guaranteeing no risk.
▍Special reminder: starting November 1, 2026, VAT must be judged separately
The Ministry of Finance and State Taxation Administration Announcement No. 28 of 2026 issued the Measures for the Administration of Domestic Entity Withholding and Remittance of Natural Person VAT, effective November 1, 2026. Where a natural person conducts a compliant taxable transaction, the domestic entity paying the price may become the VAT withholding agent and handle withholding of VAT and surcharges under the supporting filing rules.
Individual income tax and VAT are two separate taxes: even if the enterprise has determined who files the individual income tax, the VAT judgment cannot be omitted. If the individual has already paid VAT at the invoice issuance stage, the payer no longer withholds it repeatedly; if it was not paid at the invoice issuance stage and the transaction falls under the withholding measures, it should be handled according to the new rules. It is recommended to add an independent field for "whether VAT has been paid and whether withholding is required" in payment review.
▍Three common misconceptions
Misconception 1: "Once an invoice is obtained, no individual income tax needs to be withheld." An invoice cannot replace the withholding judgment. Misconception 2: "Each invoice is calculated separately as one instance." Continuous income from the same project may need to be consolidated by month. Misconception 3: "Business income is always withheld by the enterprise." Business income is usually filed by the taxpayer under business income rules, but special platforms, agency, or local collection scenarios should follow dedicated provisions and the position of the competent tax authority.
Official basis:"Individual Income Tax Law of the People's Republic of China"、State Taxation Administration Announcement No. 61 of 2018、2026 Q&A on invoice issuance for individuals' labor remuneration、Reply on continuous income from the same project、Ministry of Finance and State Taxation Administration Announcement No. 28 of 2026、Interpretation of natural person VAT withholding filing matters。
Learn about Kailing Technology's invoice issuance for individuals and tax digitalization solutions: www.kailingteck.com .
About Kailing Technology
As a national high-tech enterprise, Kailing Technology focuses on the digital and intelligent transformation of enterprise business-finance-tax and operations management, providing software products, system integration, implementation and delivery, and operational services for various government agencies, institutions, group enterprises, and SMEs.
The company has now formed ten core product lines, including: AI digital employee system, enterprise expense control management system, customer relationship management system, reverse invoicing management system, invoice issuance for individuals management system, electronic archives management system, tax fully digitalized e-invoice Leqi system, tax invoice management system, group tax filing system, and AI OCR recognition system. It is committed to connecting enterprise business, finance, tax, funds, and archive data to help customers improve operational efficiency, business-finance-tax compliance capabilities, and digital management levels.
If you have any business-finance-tax digital transformation needs, welcome to contact us. Beijing Kailing Technology will serve you wholeheartedly.
Keywords: natural person invoice issuance, withholding and remittance of individual income tax, individual income tax on remuneration for personal services, individual income tax on business income, VAT withholding, individual income tax filing, Kailing Technology
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing