
How much can a sole proprietor invoice without paying tax? First distinguish five layers of criteria
How much can a sole proprietor invoice without paying tax? First distinguish five layers of criteria
There is no "invoicing exemption amount" for individual industrial and commercial households that applies to all taxes, all invoice types and all modes of operation. The monthly or quarterly thresholds commonly cited mainly correspond to the sales preference for small-scale VAT taxpayers; individual income tax on business income is based on annual taxable income, and surcharges also depend on the VAT actually paid and local implementation. Invoicing quota, sales, taxable income and filing obligations must be judged separately.
The invoicing quota is an invoice management concept; the VAT threshold depends on sales in the tax period, while business income depends on annual revenue minus costs and expenses; the three cannot substitute for one another. |
▍1. First confirm status and tax period
Ministry of Finance and State Taxation Administration Announcement No. 19 of 2023stipulates that VAT small-scale taxpayers with monthly sales of 100,000 yuan or less (inclusive) are exempt from VAT, with the policy in effect until December 31, 2027; taxable sales revenue subject to a 3% levy rate continues to be levied at a reduced rate of 1%. For small-scale taxpayers filing quarterly, the corresponding quarterly sales not exceeding 300,000 yuan fall under the exemption basis. The State Taxation Administration's 2026Q&A on tax preferences for small and micro enterprisesThese current policies are also listed again.
Two facts must be verified before judgment: first, whether the entity is currently a small-scale taxpayer or a general taxpayer; second, whether the tax period determined by the competent tax authority is monthly or quarterly. General taxpayers cannot directly apply the small-scale taxpayer threshold; monthly filers cannot simply add three months of invoices and then apply the quarterly criterion.
▍2. Aggregate all sales, not just the invoiced amount
The VAT preference is judged using sales for the tax period, which is not equivalent to the invoice quota shown in the invoicing system, nor merely to general invoices already issued. Invoiced income, uninvoiced income and other taxable sales requiring combined judgment must all be aggregated under the applicable criterion; special matters such as tax-inclusive price conversion, differential taxation and sales of real estate must also be handled under specific rules.
Therefore, "no invoice means no sales" and "splitting income into the next quarter makes it exempt" are both incorrect understandings. The State Taxation Administration's 2026 public Q&A explicitly notes that artificial splitting of income lacking a reasonable commercial purpose may be adjusted by tax authorities. Taxpayers should recognize revenue according to genuine transactions, the time the tax obligation arises and valid vouchers.
▍3. For general and special invoices, check whether the exemption is waived
When a small-scale taxpayer meets the sales threshold, it may choose to waive the tax exemption for part or all of its sales revenue and issue VAT special invoices.Public response by the State Taxation Administration in 2025Example: a taxpayer may waive the exemption and pay tax only on the portion of sales revenue requiring special VAT invoices, while the remaining qualifying sales revenue may still enjoy the exemption.
This means that "issuing one special invoice" cannot be written as all sales in the entire period losing exemption, nor can the special invoice amount be understood as crowding out the exemption quota of general invoices. When actually invoicing, sales items, applicable policies, scope of exemption waiver, and tax handling should be recorded separately, and customer requirements and business materials should be retained.
▍4. There is no "invoicing exemption amount" for individual income tax on business income
"Individual Income Tax Law of the People's Republic of China"Business income is listed as taxable individual income. For sole proprietors under audit-based collection, business income is usually calculated as taxable income based on the balance of total annual income less costs, expenses and losses; under deemed collection, the method determined by the competent tax authority applies. The invoiced amount is only one piece of revenue-side information and cannot be multiplied directly by a tax rate to derive the tax amount.
Ministry of Finance and State Taxation Administration Announcement No. 12 of 2023stipulates that from 2023 to 2027, the portion of annual taxable income of individual businesses not exceeding 2 million yuan may be subject to individual income tax at half the rate. Whether tax is actually incurred depends on annual revenue, costs and expenses, collection method, and applicable benefits; VAT exemption does not mean individual income tax on business income is necessarily zero.
▍5. Exemption, zero filing and no filing obligation are not the same thing
Even when VAT exemption conditions are met, tax-exempt filing or material retention is usually still required according to registration information, tax period, and filing form requirements. Business income must also be handled through prepayment, annual settlement, or deemed filing according to the collection method. Zero filing, tax-exempt filing, and having no filing obligation are different statuses and cannot be chosen solely based on the invoice amount for the period.
Whether surcharges, stamp duty, property tax, urban land use tax, and others arise also depends on the specific transaction, assets, and actual tax paid. Announcement No. 12 of 2023 provides a 50% reduction on the "six taxes and two fees" for eligible small-scale taxpayers, small low-profit enterprises, and individual businesses, but this benefit cannot be expanded into a blanket exemption from all taxes.
▍6. Use a five-layer checklist to preserve filing evidence
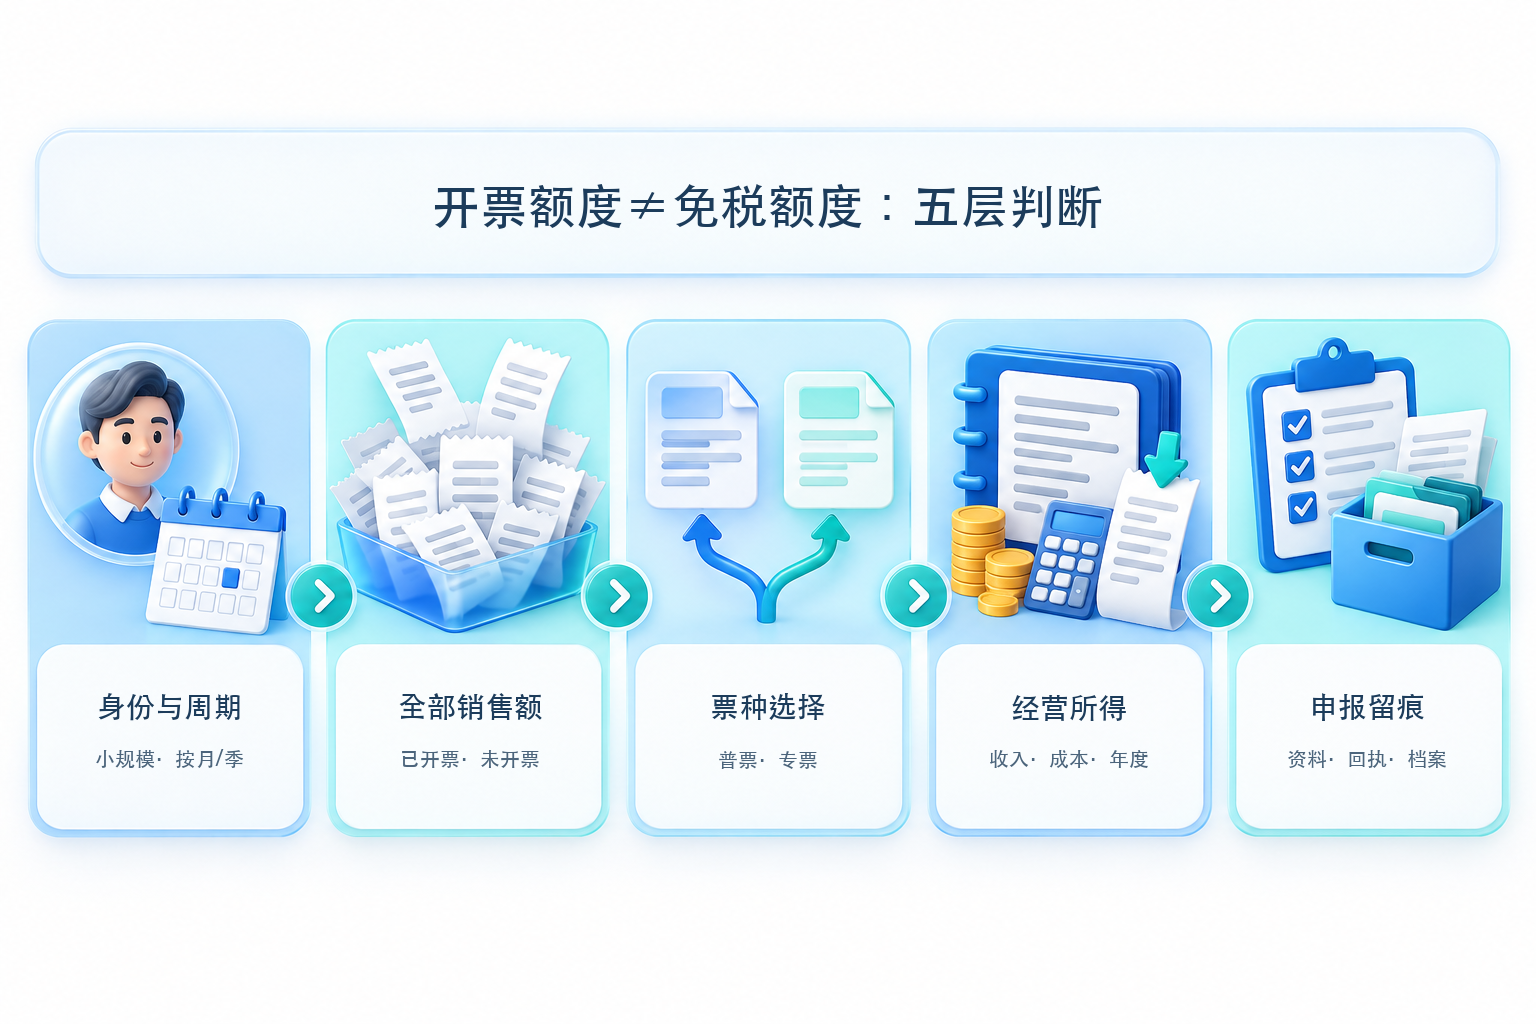
| Judgment layer | Needs verification | Retained materials |
| Status and period | Small-scale or general, monthly or quarterly | Registration information, tax type determination, filing deadline |
| Total sales | Invoiced, not invoiced, special business | Contracts, orders, receipts, revenue ledger |
| Invoice type selection | General invoices, special invoices, scope of exemption waiver | Invoicing records, customer requirements, policy basis |
| Business income | Annual revenue, costs and expenses, collection method | Accounting books, vouchers, expenses, and asset materials |
| Filing trail | Filing forms, tax amount, receipts, and corrections | Filing records, receipts, tax payment or exemption materials |
▍7. Software can assist in aggregation but cannot replace tax judgment
Kailing Business-Finance-Tax Cloud official pageCapability directions such as invoices, transaction records, vouchers, ledgers, filing working papers and receipt archiving are disclosed;Kailing AI OCRMay serve as a candidate for structured entry of documents. The actual tax types, regions, channels, authorization, rule versions and manual review points should be verified in the target environment. The system can help aggregate and keep records, but cannot replace judgment on taxpayer status, business authenticity, special transactions and ultimate tax liability.
(This article is compiled based on public policies of the State Taxation Administration as of October 28, 2026, and is for general information only; it does not constitute tax, accounting, or legal advice. Individual business conditions, collection methods, and regional implementation may differ; please check the latest policies before filing and consult the competent tax authority or professionals when necessary.)
Keywords: Sole proprietor invoicing quota, sole proprietor exemption amount, small-scale taxpayer VAT exemption, individual income tax on business income, special VAT invoice, tax filing, Kailing Technology
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing