Checklist of application materials for reverse invoicing of renewable resources; miss one item and you are stuck
Renewable resources reverse invoicing material checklist: first distinguish qualification application from per-transaction retention
"What to submit to apply for reverse invoicing qualification" and "what to keep for each purchase" are two different sets of materials. The former is used by resource recycling enterprises to report to the competent tax authority and apply to carry out business, while the latter is used to prove the natural person's identity, genuine purchase, transport and weighing, payment and invoicing chain. Mixing the two together easily leads to mistakenly thinking that all transaction attachments must be submitted for each application, or that after obtaining qualification there is no need to continue keeping business evidence.
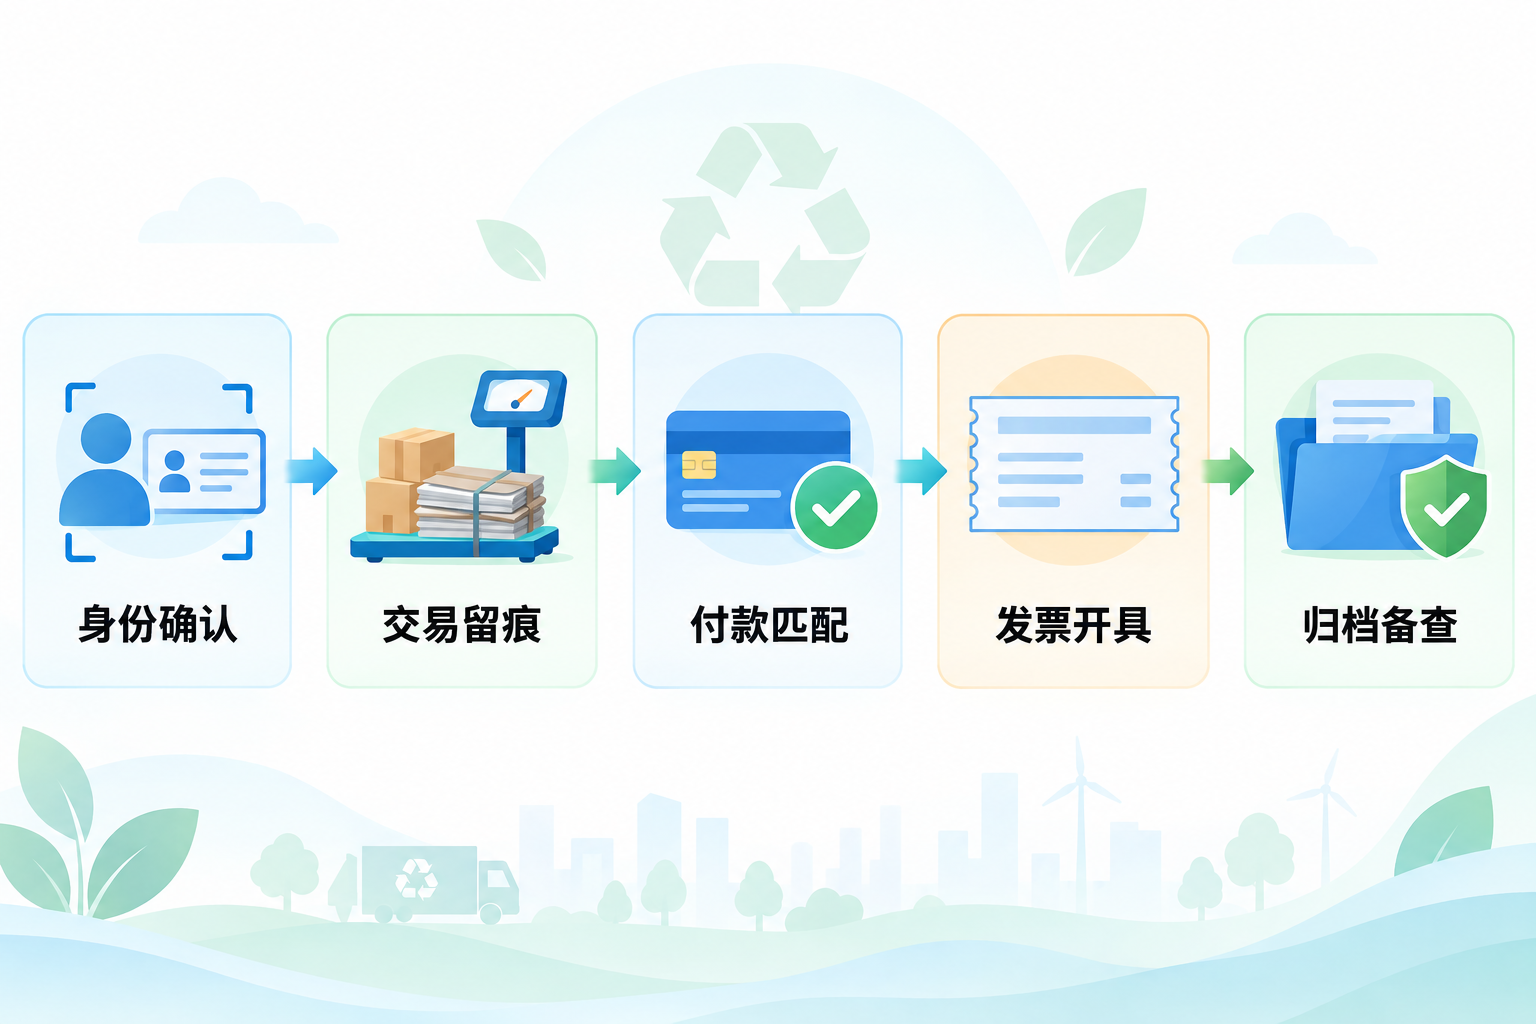
The compliance focus is not gathering a few pieces of paper, but enabling the seller, scrapped products, transaction amount, fund payment, invoice and ledger to corroborate each other. |
▍1. Qualification application: submit the application form first, then provide qualifications according to business type
According toCurrent service guide of the tax authority, a qualifying resource recycling enterprise that needs reverse invoicing should submit the "Resource Recycling Enterprise 'Reverse Invoicing' Application Form" to the competent tax authority. Those engaged in the collection of hazardous waste also need to provide a hazardous waste operating license; those engaged in the recycling of scrapped motor vehicles need to provide the qualification recognition certificate for scrapped motor vehicle recycling and dismantling enterprises; other resource recycling enterprises need to provide the renewable resource recycling operator filing registration certificate from the commerce department. The specific number of copies, online entry and verification methods are subject to the current requirements of the competent tax authority.
▍2. Seller scope: it cannot be written as simply "has not completed tax registration"
Based on the full text in effectState Taxation Administration Announcement No. 5 of 2024, the seller is a natural person who sells scrapped products they have used themselves or sells purchased scrapped products, and whose cumulative sales amount of "reverse invoicing" over no more than 12 consecutive months does not exceed 5 million yuan (excluding VAT). Enterprises should verify the genuine identity, contact information, nature of goods and cumulative sales amount, and continuously track applicable conditions; they cannot judge merely on the basis that there is "no tax registration".
▍3. First reverse invoicing: the seller's consent must be obtained and proof retained
When a resource recycling enterprise issues a reverse invoice to a certain seller for the first time, it should obtain their consent on reverse invoicing and tax filing on behalf matters, and retain relevant proof materials; if the seller does not consent, no reverse invoice may be issued to them. The system can record the consent time, handling personnel and material version, but cannot replace genuine authorization, nor may it issue invoices using another person's identity.
▍4. Per-transaction retention: contracts, transport, weighing, transfers and ledgers must correspond to each other
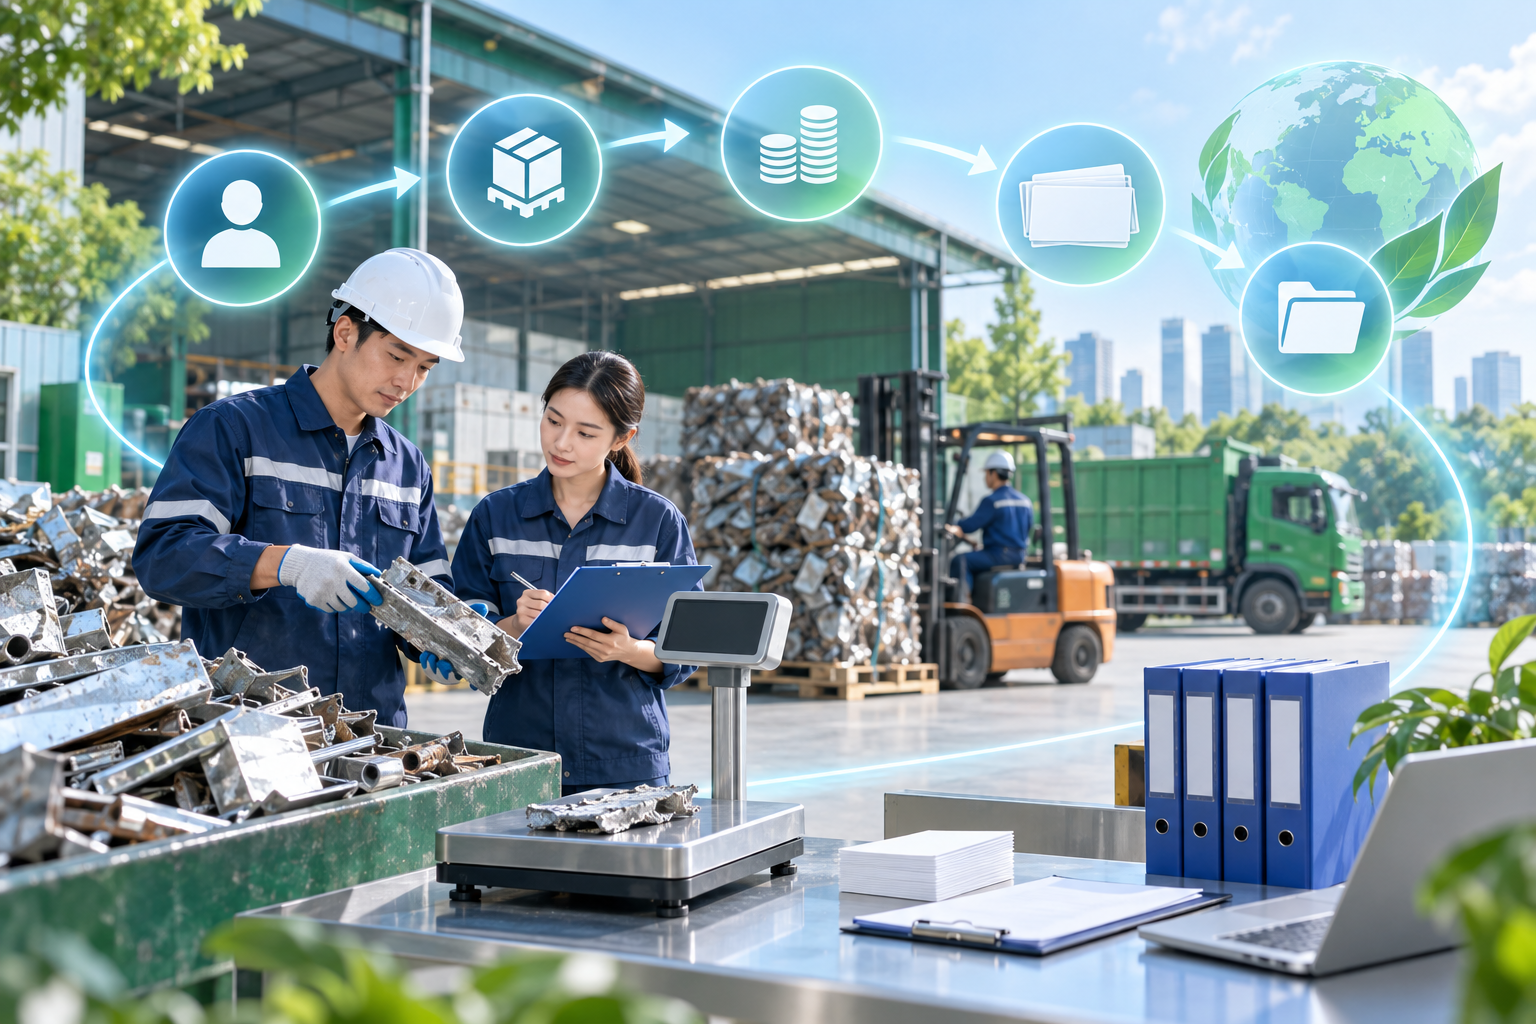
Announcement No. 5 requires enterprises to keep materials that can prove the authenticity of the business, including contracts or agreements for purchasing scrapped products, transport invoices or vouchers, cargo weighbridge tickets, transfer payment records, etc., and to establish a purchase ledger that records in detail the time, place, seller and contact information, name, quantity and price of scrapped products for each transaction; if existing ledgers or systems already contain this content, there is no need to create a duplicate ledger. Enterprises may associate materials by batch and provide discrepancy alerts, but anomalies still need to be verified by the handling personnel.
▍5. After invoicing: still need to complete tax filing on behalf and continuous verification
When a resource recycling enterprise issues reverse invoices to a seller, it should, as required, file VAT and surcharges and individual income tax on behalf of the seller, and submit the corresponding report forms and pay the taxes filed on behalf within the prescribed period. When returns, price adjustments or red-letter processing occur, the business reasons and before-and-after association records should be retained. Software can assist with collection, verification, reminders and archiving, but business authenticity, material authenticity and responsibility for paying taxes in accordance with the law are still borne by the relevant entities.
Implementation checklist: Qualification application form and corresponding qualifications; seller identity and contact information; proof of first consent; contract or agreement; transport vouchers; weighing records; transfer payment records; invoices and red-letter associations; per-transaction purchase ledger; tax filing on behalf report materials. Before submission, confirm the local handling standards again with the competent tax authority.
Keywords: renewable resources reverse invoicing, reverse invoicing application materials, resource recycling enterprise, natural person seller, purchase ledger, first consent, tax filing on behalf, scrapped products
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing