Can expert review fees be reverse invoiced? Determine the relationship first, then process the voucher
Can expert review fees be reverse invoiced? Usually the resource recycling "reverse invoicing" cannot be directly applied.
The reverse invoicing stipulated in State Taxation Administration Announcement No. 5 of 2024 applies to qualified resource recycling enterprises purchasing scrap products from individual scrap product sellers; experts providing review services do not fall within the scope of this policy. Enterprises should first determine the nature of the income based on the personnel relationship and actual services, then handle invoices or other compliant vouchers, individual income tax withholding and document retention.
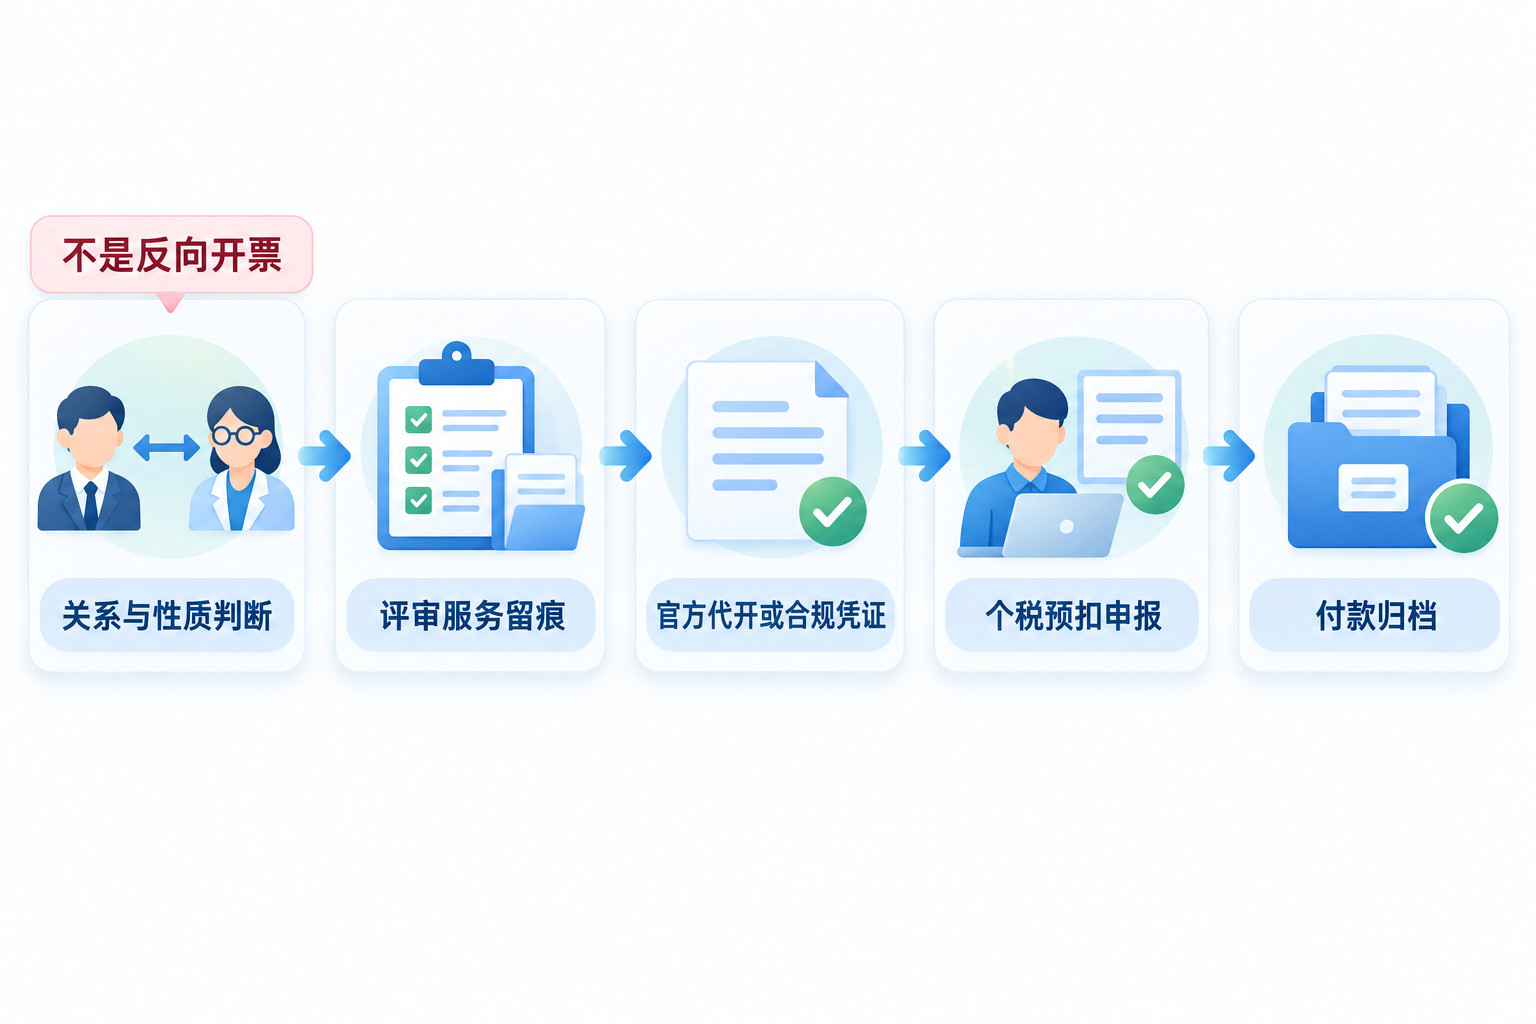
The correct order is "determine the relationship and business nature - prove the service is authentic - obtain compliant vouchers - fulfill individual income tax obligations - pay and archive", not first finding a system to issue the invoice. |
▍1. First determine whether it is wages and salaries or remuneration for labor services
"Expert review fee" is only a name for an expense; tax treatment still depends on the facts. If the expert has an employment relationship with the paying entity and the review falls within the scope of their duties, it may need to be treated as wages and salaries; if an external expert independently provides one-off or project-based review services, it is usually treated as remuneration for labor services. Enterprises should retain the engagement or review agreement, expert identity, service content, review records and deliverable materials, and must not judge the nature of the income based only on the payment note.
▍2. Expert review services do not fall under resource recycling reverse invoicing
The invoicing party, seller and scrap product scope of resource recycling reverse invoicing all have clear boundaries. Expert review is a service matter, different from scrap product acquisition, and is not an agricultural product acquisition invoice scenario. When an invoice is needed, it should be applied for issuance on behalf through the local electronic tax bureau, the relevant functions of the individual electronic tax bureau or a channel recognized by the tax authority; the specific entry point, materials and who may initiate it are subject to the current rules of the local competent tax authority.
▍3. Pre-tax deduction vouchers do not recognize only invoices for every amount
State Taxation Administration Announcement No. 28 of 2018stipulates that for domestic VAT taxable expenditures, where the counterparty is a taxpayer that has completed tax registration, an invoice is usually used as the pre-tax deduction voucher; where the counterparty is a unit that is not required by law to complete tax registration or an individual engaged in small sporadic business, an invoice issued on behalf by the tax authority as required may be used, or a payment receipt stating statutory information and internal vouchers. Enterprises should also retain contracts and agreements, expenditure basis and payment vouchers to prove authenticity, legality and relevance.
▍4. Issuing an invoice on behalf does not mean individual income tax handling is complete
According toMeasures for the Administration of Individual Income Tax Withholding and Filing, a withholding agent paying remuneration for labor services to a resident individual shall withhold and prepay tax on a per-time or monthly basis. Tax authorities2026 public Q&Aalso clarifies that when an individual applies for invoice issuance on behalf and remuneration for labor services is involved, the paying entity shall still handle full-staff full-amount withholding filing in accordance with the law. Enterprises cannot treat "the invoice has already been issued on behalf" as meaning the individual income tax obligation has ended.
▍5. The system can assist in aggregation, but cannot replace official issuance and tax judgment
Kailing TechnologyInvoice Issuance for Individuals SolutionWithin the scope permitted by enterprise authorization and local functions, it can assist in organizing expert information, service materials, invoice issuance application data, payment and withholding status; the final invoice should still be issued in accordance with the law by the tax authority or an official channel recognized by it. The system also cannot replace professional judgment on personnel relationships, the nature of income, pre-tax deduction conditions and withholding tax amounts.
▍6. Archiving must cover the complete service evidence chain
It is recommended to link by project the invitation letter or agreement, expert identity, recusal and approval records, review process or deliverables, compliant vouchers, payment receipts, individual income tax withholding records and anomaly explanations. Kailing TechnologyElectronic accounting archivesIt can assist in linking and retrieving these materials; OCR recognition results should be reviewed, and successful scanning or recognition does not mean the voucher is compliant, has been recorded, or that the expense can of course be deducted pre-tax.
Keywords: expert review fee, reverse invoicing, invoice issuance for individuals, remuneration for labor services, individual income tax withholding filing, pre-tax deduction voucher, electronic accounting archives, Kailing Technology
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing