Where do input VAT vouchers for renewable resource recycling come from? First look at the conditions for reverse invoicing
Where do input VAT vouchers for renewable resource recycling come from? First look at the conditions for reverse invoicing
The difficulty recycling enterprises face in obtaining invoices cannot be solved by "padding invoices"; compliant vouchers must be formed from genuine receipt, seller identity, payment, and tax and fee filing. When a natural person seller of scrapped products sells scrapped products to a qualifying resource recycling enterprise, the enterprise may apply for and implement reverse invoicing in accordance with regulations; however, there are clear boundaries for applicable targets, enterprise qualifications, consecutive sales amounts, invoice types, and tax filing agency.
Reverse invoicing addresses qualifying genuine scrapped product transactions, not a universal invoicing tool for all recycling expenditures. |
▍1. First confirm whether the enterprise is qualified for reverse invoicing
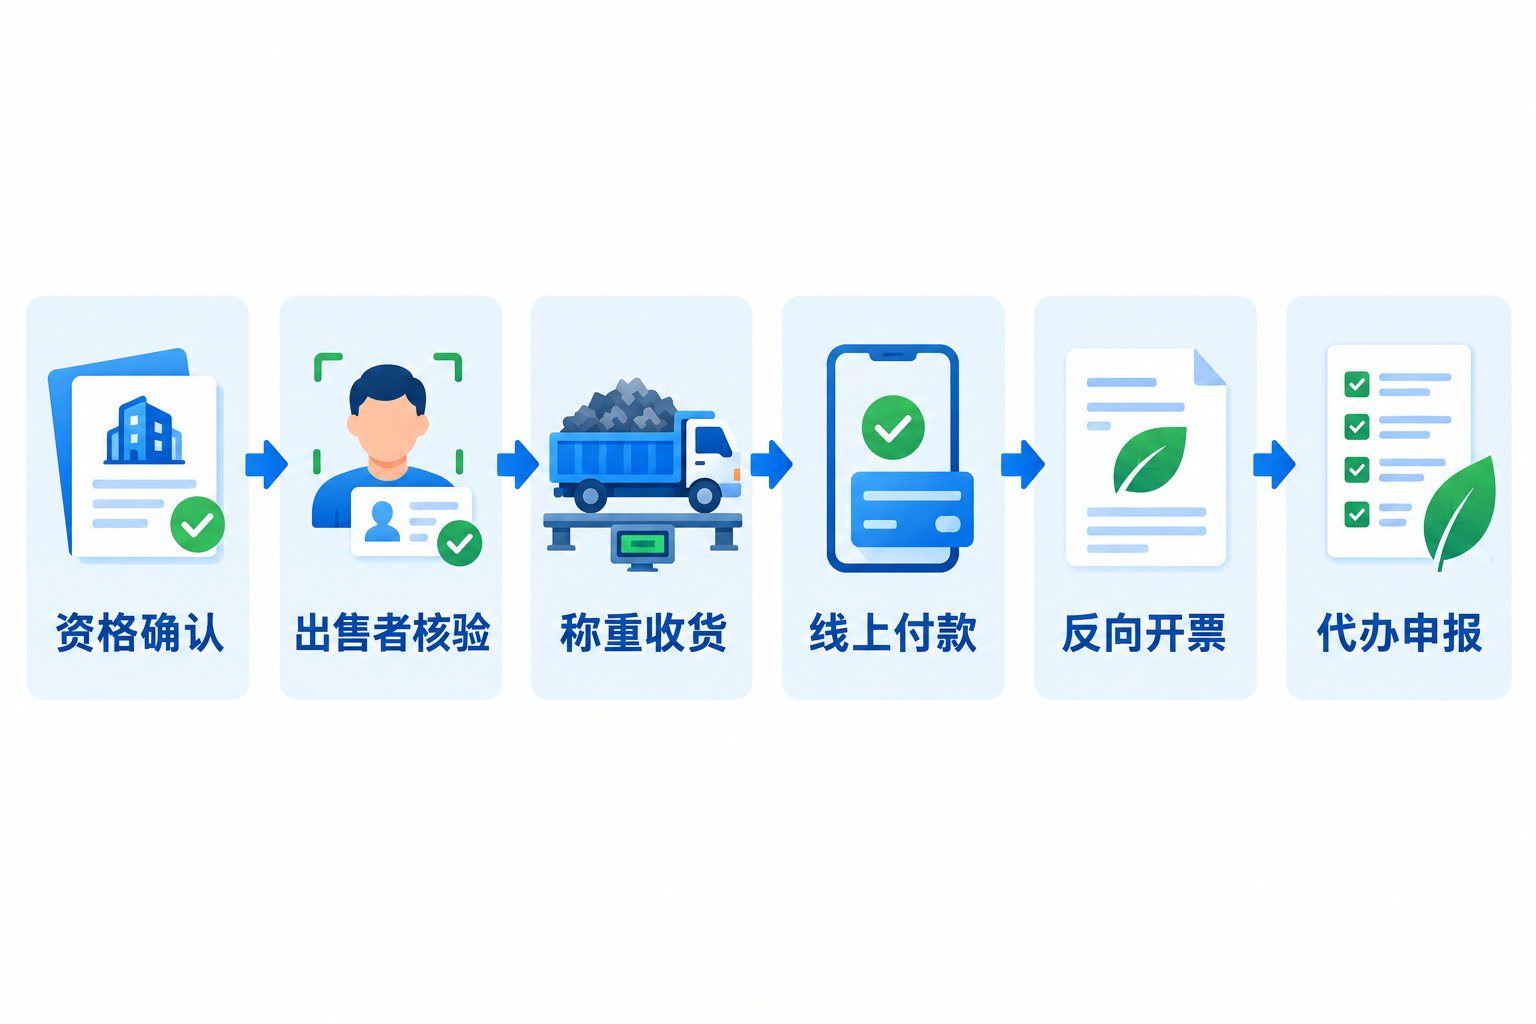
The State Taxation Administration's policy on reverse invoicing for resource recycling enterprises clarifies that enterprises need to submit an application to the competent tax authority and provide corresponding materials such as a hazardous waste operation permit, a qualification recognition certificate for scrapped motor vehicle recycling and dismantling enterprises, or a renewable resource recycling operator filing registration certificate from the commerce department. Only after completing the prescribed procedures can they issue invoices marked "scrapped product purchase" online through the electronic invoice service platform or the VAT invoice management system. SeeInterpretation of the State Taxation Administration's implementation measures for reverse invoicing。
▍2. Sellers and scrapped products also have applicable boundaries
The seller in the policy refers to a natural person who sells used scrapped products they have used themselves or sells acquired scrapped products, and whose cumulative sales amount through reverse invoicing does not exceed 5 million yuan over 12 consecutive months; scrapped products are products that have lost all or part of their original use value. Enterprises should verify the seller's identity, cumulative sales situation, and the nature of the goods, and cannot simply include legal persons, individual industrial and commercial households, or transactions that are not scrapped products into the same process.
▍3. Reverse invoicing must corroborate weighing, receipt, and payment
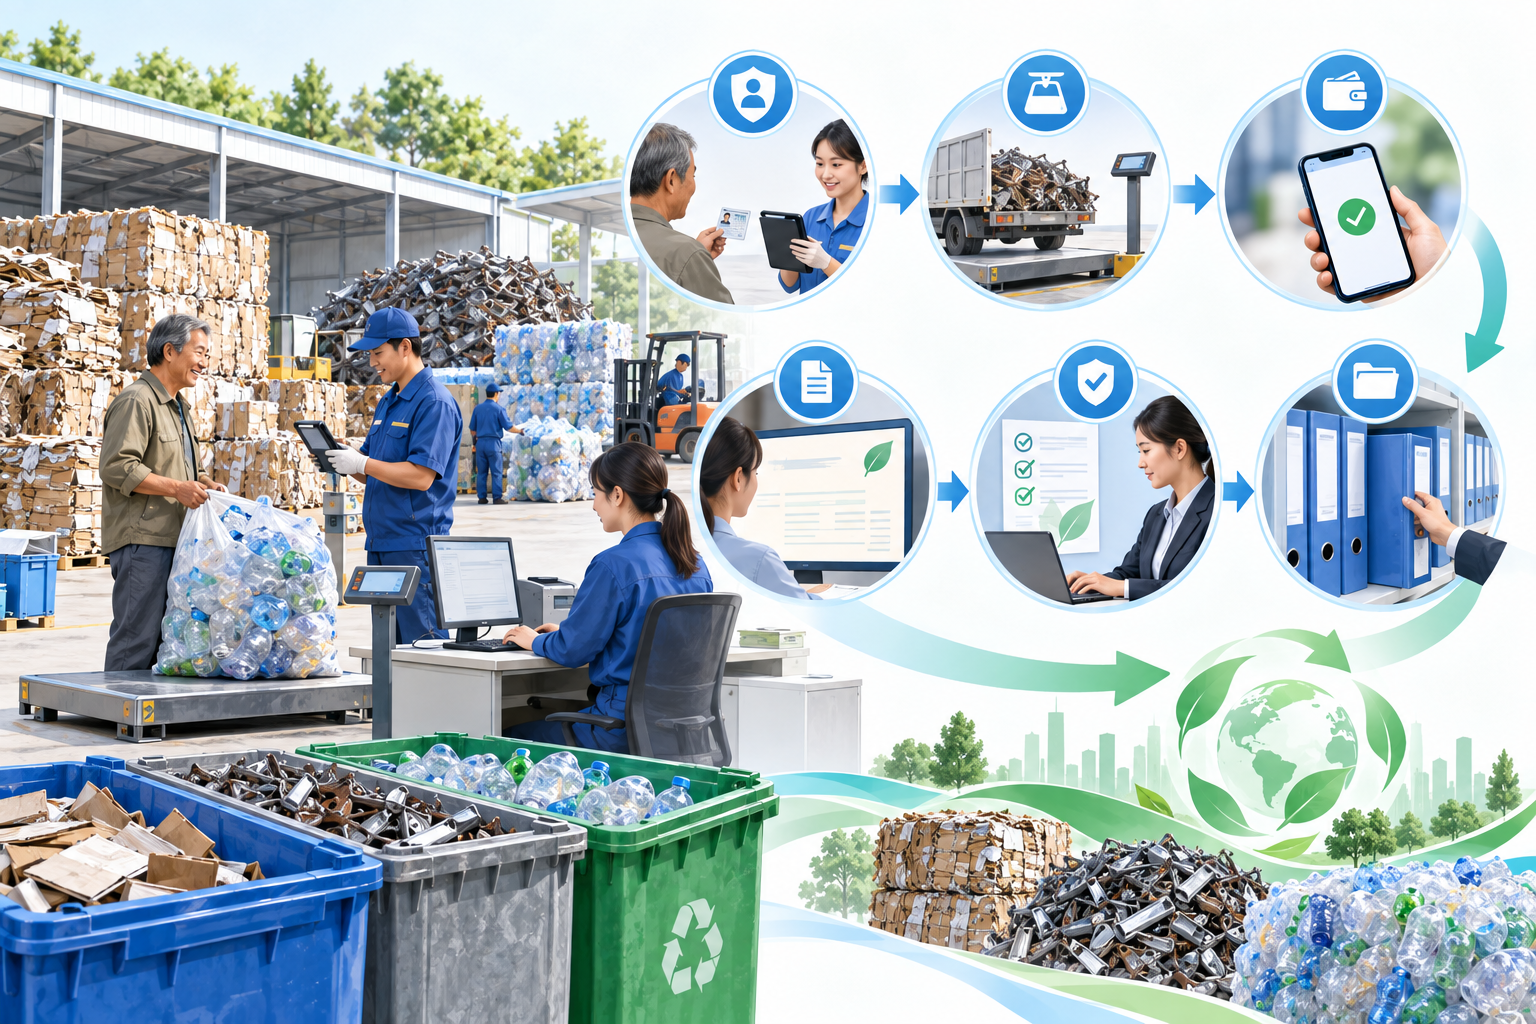
Acquisition batches should be linked to sellers, categories, weights, acceptance, settlement, online payments, and on-site materials. Kailing Technology's reverse invoicing-related systems can, based on the enterprise's implementation scope, aggregate these business records and associate invoices with specific receipt batches. System validation can only help detect abnormalities in identity, quantity and amount, or duplicate business; it cannot replace the enterprise's review of goods sources and transaction authenticity.
▍4. Special invoices, general invoices, and input VAT deduction must not be conflated
Resource recycling enterprises that apply the general tax calculation method may, in accordance with regulations, issue special VAT invoices or ordinary invoices through reverse invoicing; those that apply the simplified tax calculation method may only issue ordinary invoices through reverse invoicing. Qualifying special invoices obtained may be used to deduct the stated tax amount in accordance with regulations, and ordinary invoices may serve as pre-tax deduction vouchers for corporate income tax, but this does not automatically create an input VAT deduction. Enterprises should judge separately based on their own tax calculation method, invoice type, and business facts.
▍5. Enterprises must also handle tax and fee filing on behalf of sellers
After reverse invoicing, resource recycling enterprises should, according to regulations, handle VAT and surcharges, individual income tax, and other filing on behalf of sellers and pay the taxes and fees on their behalf. The 2026 VAT collection and administration announcement still clarifies that when individual sellers of scrapped products sell scrapped products through reverse invoicing, the resource recycling enterprise handles tax and fee filing on their behalf according to regulations. SeeState Taxation Administration Announcement No. 4 of 2026. Overdue or underpaid taxes may affect reverse invoicing qualification.
▍6. Invoice issuance for individuals and AI OCR can only solve problems within their respective scopes
Expenditures such as labor, transportation, or leasing should be handled through invoice issuance for individuals by qualified individuals according to the actual business and the channels of the local tax authority, with withholding filing responsibilities handled simultaneously; it cannot replace reverse invoicing for scrapped products. AI OCR can assist in recognizing fields on weighbridge tickets, receipts, and contracts, but these image materials themselves are not equivalent to VAT deduction vouchers. Enterprises should retain invoices, receipt, payment, approval, and filing records together to form a traceable evidence chain.
Keywords: renewable resource recycling input VAT vouchers, reverse invoicing, scrapped product purchase, seller verification, tax and fee filing on behalf, resource recycling enterprise, AI OCR, Kailing Technology
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing