
How is bookkeeping done for the 9% agricultural product deduction? Explained clearly in one article
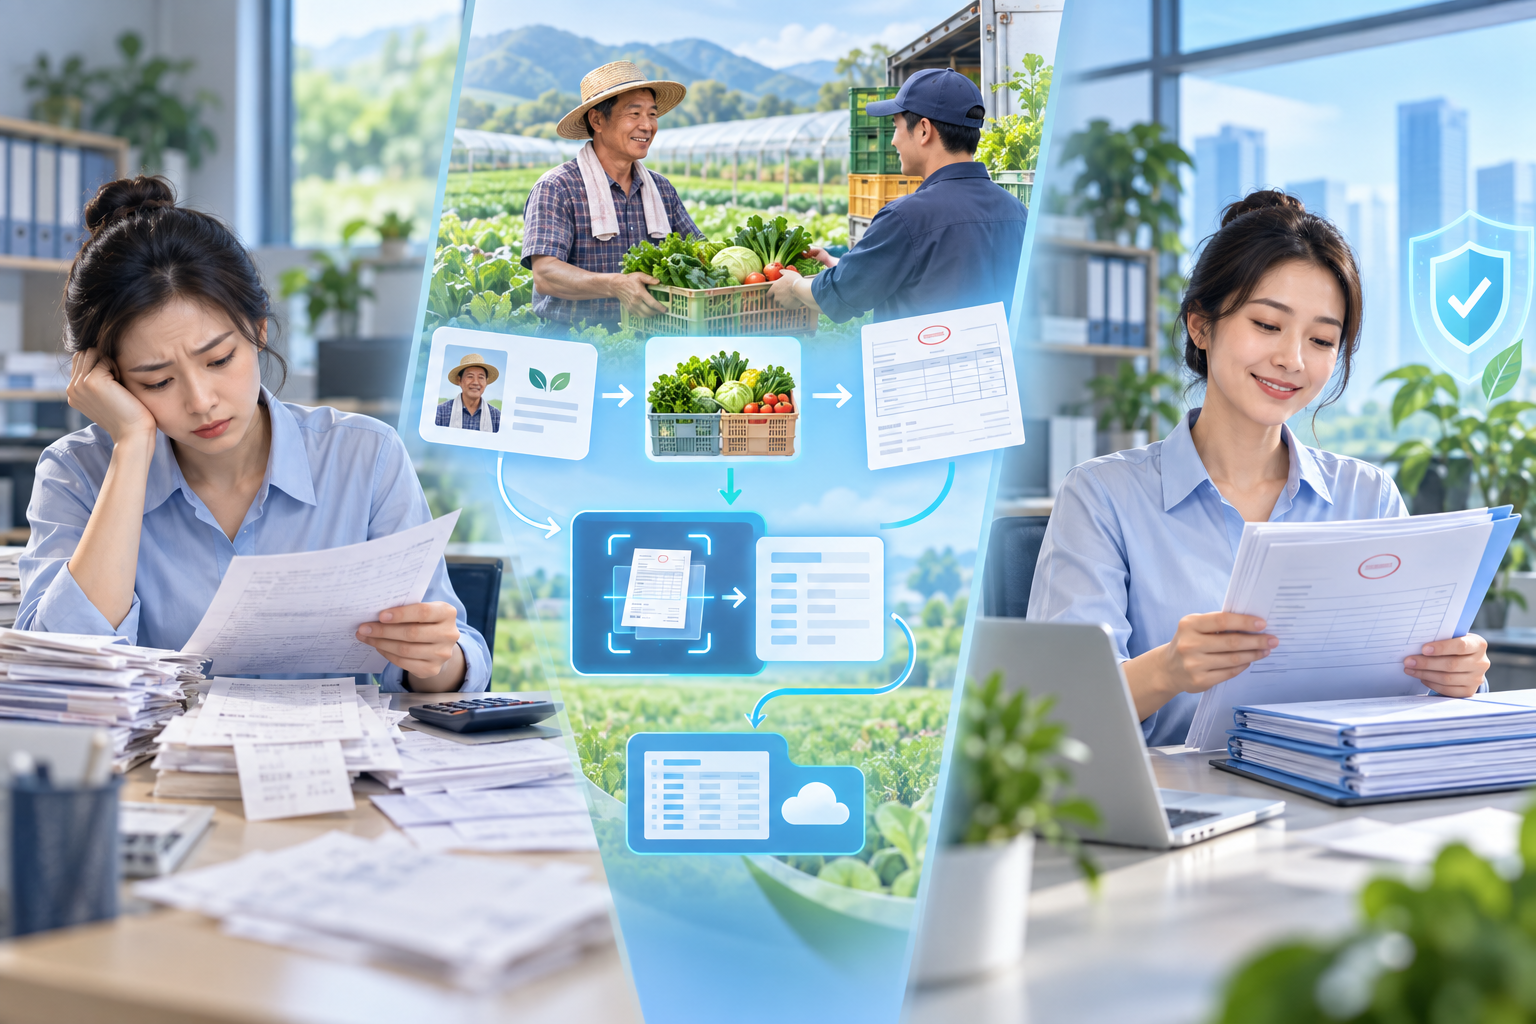
How is bookkeeping done for the 9% agricultural product deduction? From vouchers to filing, one article thoroughly explains compliance points and practical details
Many finance staff get headaches whenever they encounter agricultural product deductions: how should purchase invoices be issued? How is the 9% input tax calculated? Make one wrong step in the journal entry, and a tax bureau inquiry follows. In fact, as long as you grasp the three keys of "compliant vouchers, accurate calculation, timely filing," you can handle it with ease. Kailing Technology's reverse invoicing and AI OCR products are tailor-made for such scenarios.
"The difficulty of agricultural product deduction lies not in calculation, but in the authenticity and compliance of the vouchers." |
▍1. What is the policy basis for the 9% agricultural product deduction?
According to the Notice of the Ministry of Finance and the State Taxation Administration on Policies Concerning the Simplification and Merger of VAT Rates (Caishui [2017] No. 37) and subsequent provisions, where a taxpayer purchases agricultural products and obtains a special VAT invoice issued by a general taxpayer or a customs import VAT special payment certificate, the input VAT shall be the VAT amount stated on the face of the document; where an agricultural product purchase invoice or sales invoice is obtained (issued), the input VAT shall be calculated based on the agricultural product purchase price and a deduction rate of 9%. If used for producing goods subject to a 13% tax rate, an additional 1% deduction may be applied. Therefore, "purchase price × 9%" is the core formula, but the premise is that the voucher must be genuine and compliant.
▍II. How to issue purchase invoices? How does reverse invoicing simplify the process?
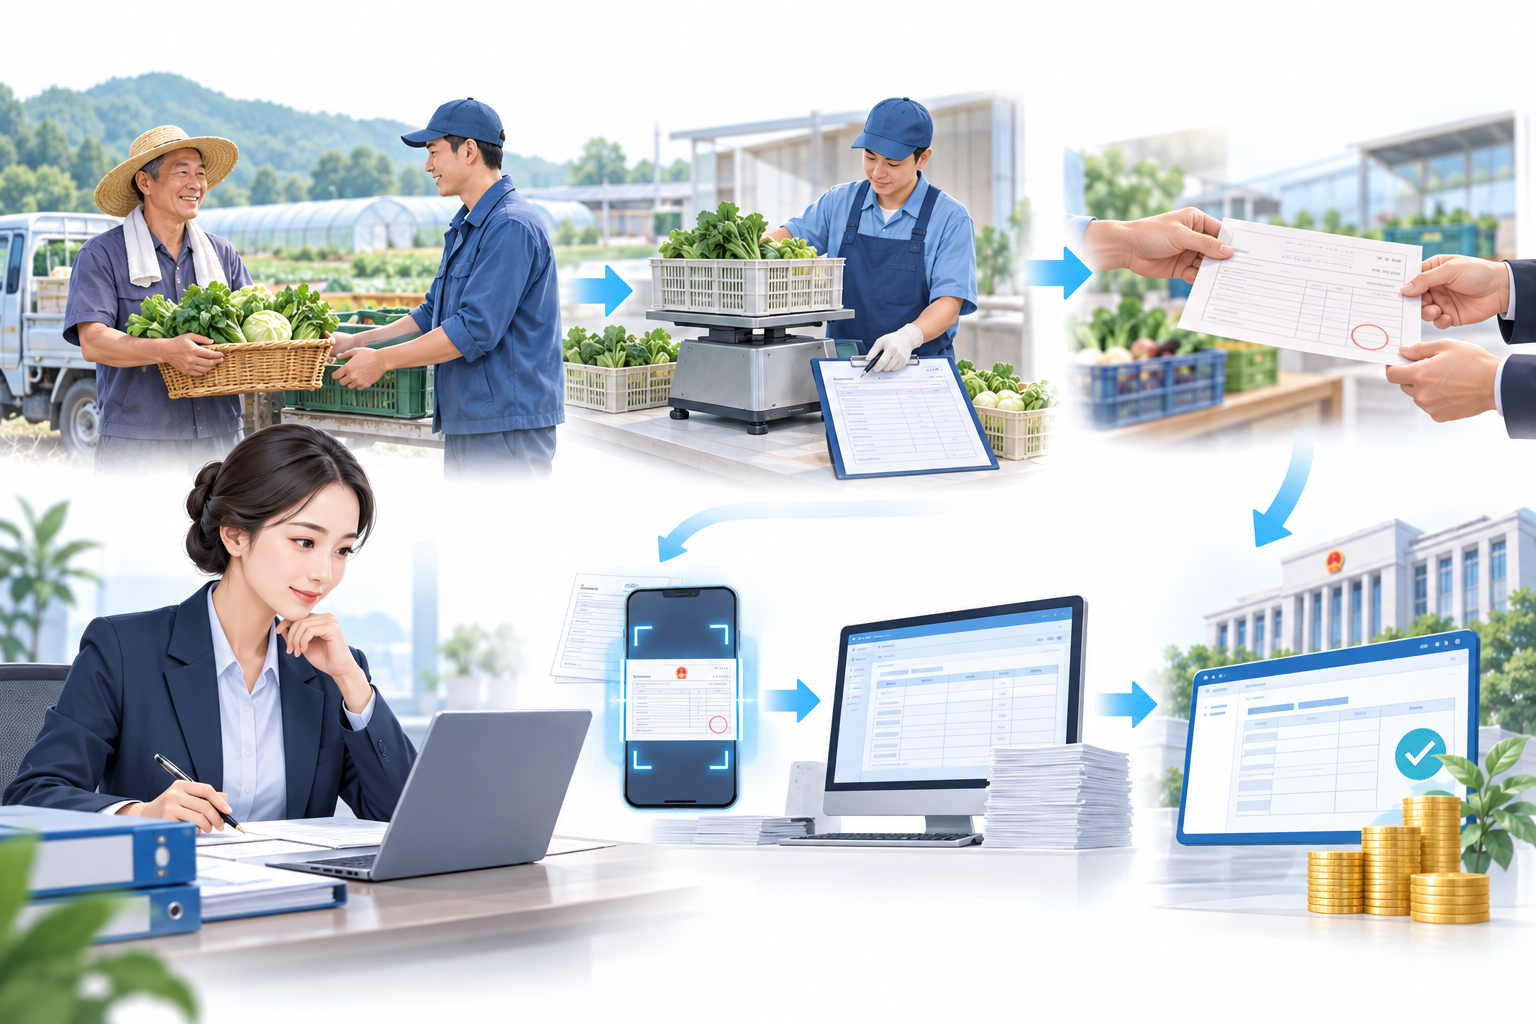
When issuing agricultural product purchase invoices independently, seller information, product name, quantity, unit price, etc. must be filled in transaction by transaction, and copies of ID cards, weighbridge tickets, and payment vouchers must be retained for inspection. Kailing Technology's reverse invoicing system is designed specifically for agricultural product purchase scenarios, supporting "invoice upon purchase" and automatically generating a five-flow-in-one ledger (contract flow, goods flow, invoice flow, fund flow, information flow), ensuring every deduction is traceable. The system seamlessly connects with the tax authority side, uploading invoicing data in real time, avoiding the problems of manual filling errors and omissions.
▍III. How to account for the 9% deduction? Key points for entries and filing
Assume a certain enterprise purchases agricultural products and pays a purchase price of 100,000 yuan. Then the calculated input tax amount = 100,000 × 9% = 9,000 yuan, and the cost is 91,000 yuan. The entry is as follows: Debit: Raw materials (or inventory goods) 91,000, Taxes payable - VAT payable (input tax amount) 9,000, Credit: Bank deposits (or accounts payable) 100,000. When filing, the amount and tax amount need to be filled in Column 6 "Agricultural product purchase invoice or sales invoice" of Annex (II) to the VAT tax return. Note that if used for deep processing, the 1% portion also needs to be reported in the additional deduction column.
▍IV. How to prevent tax risks in agricultural product deductions?
False issuance and inaccurate information on agricultural product purchase invoices are key audit targets of tax authorities. Enterprises should ensure the authenticity of purchase business and keep purchase vouchers, payment records, and logistics documents well. Kailing's tax risk control system can automatically scan filing data and warn on abnormal indicators, such as an excessively high deduction ratio or invoice product names inconsistent with the business scope. At the same time, AI OCR intelligent recognition technology can quickly collect invoice, weighing slip, and other document information, recognizing and recording immediately, reducing manual entry errors, ensuring consistency between accounts and invoices, and making every deduction stand up to scrutiny.
Keywords: 9% agricultural product deduction, agricultural product procurement invoices, input tax calculation, reverse invoicing, agricultural product bookkeeping, tax risks, AI OCR
As a comprehensive business-finance-tax digitalization solution service provider, Kailing Technology provides business-finance-tax management digital transformation products and operational services for various government agencies, institutions, and large, medium, and small enterprises. The product line includes: solutions for sales contract management system, procurement contract management system, fully digitalized Leqi interface project, automatic output invoicing system, reverse invoicing system, invoice issuance for individuals system, employee expense control and reimbursement system, input VAT invoice management system, supply chain collaborative reconciliation system, image AI OCR recognition system, automatic financial bookkeeping system, electronic accounting archives system, etc., comprehensively driving the digitalization process across various fields.
Consultation Hotline: 18513895936 / 010-60974119 Location: Beijing